


 |
市場調查報告書
商品編碼
2083337
獸醫診斷市場機會、成長要素、產業趨勢分析及2026-2035年預測。Veterinary Diagnostics Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球獸醫診斷市場預計到 2025 年將達到 53 億美元,預計到 2035 年將以 9.1% 的複合年成長率成長至 126 億美元。
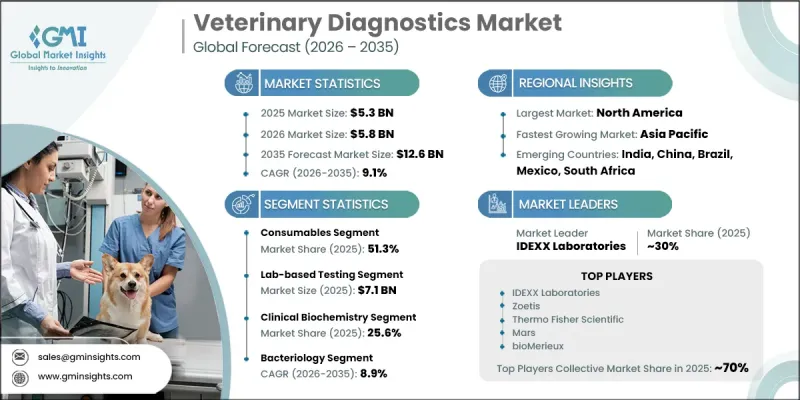
市場擴張的促進因素包括伴侶動物和家畜感染疾病、通用感染疾病和慢性病發病率的上升,以及人們對預防性獸醫保健意識的增強。疾病爆發頻率的增加持續加劇了對準確快速診斷解決方案的需求。近年來,在伴侶動物醫療保健成本不斷上漲和診斷技術持續進步的推動下,市場呈現穩定成長態勢。新興和跨境動物疾病負擔的加重進一步加速了對可靠檢測解決方案的需求。全球伴侶動物和家畜數量的成長也推動了整體市場需求。寵物飼養量持續成長,尤其是犬貓,飼主也更積極主動投資於定期健康檢查和預防性照護。同時,分子診斷、PCR、次世代定序、生物標記檢測和攜帶式即時檢測系統等技術的進步,正在提高疾病檢測的速度、準確性和可及性。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 53億美元 |
| 預計金額 | 126億美元 |
| 複合年成長率 | 9.1% |
預計到2025年,耗材市佔率將達到51.3%,並將在2026年至2035年間以9.2%的複合年成長率持續成長。其主導地位得益於耗材在整個診斷流程中的關鍵作用以及永續的收入結構。耗材包括試劑、診斷試劑盒、檢測盒、採血管、玻片、校正工具和品管品,廣泛應用於獸醫院、診所、診斷檢查室和實驗室。
預計到2035年,檢查室檢測市場規模將達71億美元。由於其能夠支持包括分子檢測、微生物分析、免疫檢測、毒理學篩檢和專業病理評估在內的先進診斷程序,該市場仍備受青睞。這些檢測需要先進的檢查室基礎設施、技術精湛的專業人員和受控環境,以確保疾病檢測的準確性和可靠性。
預計到2025年,北美獸醫診斷市佔率將達到46.5%。該地區的領先地位得益於其先進的獸醫基礎設施、較高的寵物擁有率、較高的診斷技術普及率以及創新動物健康技術的廣泛應用。此外,成熟的診斷公司、廣泛的檢查室網路和完善的獸醫體係也進一步增強了該地區的市場實力和永續成長。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 每個階段增加的價值
- 影響價值鏈的因素
- 影響產業的因素
- 促進因素
- 寵物飼養趨勢
- 食物中毒和通用感染疾病的發生率增加
- 理想的政府政策
- 伴隨診斷技術的進展
- 寵物保險的普及
- 產業潛在風險與挑戰
- 動物實驗成本高昂
- 獸醫護理自付費用低。
- 市場機遇
- 擴展即時診斷 (POC) 解決方案
- 人工智慧和數據分析在診斷領域的融合
- 促進因素
- 成長潛力分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格分析
- 對過去價格趨勢的分析
- 價格分析:依藥物類型
- 監理情勢
- 波特的分析
- PESTLE分析
- 人工智慧和生成式人工智慧對市場的影響
- 投資和資金籌措趨勢
- 未來市場趨勢
- 寵物數量統計數據
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估價與預測:依產品分類,2022-2035年
- 消耗品
- 裝置
- 軟體
第6章 市場估計與預測:依治療方式分類,2022-2035年
- 即時偵測(POC)
- 檢查室測試
第7章 市場估計與預測:依技術分類,2022-2035年
- 臨床生物化學
- 血糖監測
- 血氣和電解質分析
- 其他臨床生物化學檢驗
- 免疫診斷
- 橫向流動化驗
- ELISA
- 免疫檢測裝置
- 其他免疫學診斷測試
- 分子診斷
- PCR
- 微陣列
- 其他分子診斷測試
- 血液學
- 尿液檢查
- 醫學影像(包括人工智慧輔助)
- 其他技術
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 細菌學
- 病理
- 寄生蟲學
- 其他用途
第9章 市場估計與預測:依動物類型分類,2022-2035年
- 伴侶動物
- 狗
- 貓
- 馬
- 其他伴侶動物
- 家畜
- 牛
- 豬
- 家禽
- 其他牲畜
第10章 市場估價與預測:依最終用途分類,2022-2035年
- 獸醫醫院和診所
- 診斷實驗室
- 居家醫療
- 其他最終用戶
第11章 市場估價與預測:按地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第12章:公司簡介
- Agrolabo
- Bio-Rad Laboratories
- bioMerieux
- BioNote
- Biochek
- Eurolyser Diagnostica
- Fujifilm
- GD Animal Health(Royal GD)
- IDEXX Laboratories
- IDvet
- INDICAL Bioscience
- MEGACOR Diagnostik
- Mindray Animal Medical Technology
- Neogen
- QIAGEN
- Randox Laboratories
- Thermo Fisher Scientific
- Virbac
- Zoetis
The Global Veterinary Diagnostics Market was valued at USD 5.3 billion in 2025 and is estimated to grow at a CAGR of 9.1% to reach USD 12.6 billion by 2035.
Market expansion is driven by the rising incidence of infectious, zoonotic, and chronic diseases across both companion and livestock animal populations, along with growing awareness of preventive veterinary healthcare. The increasing frequency of disease outbreaks continues to reinforce the need for accurate and rapid diagnostic solutions. Over recent years, the market has shown consistent growth, supported by higher expenditure on companion animal healthcare and continuous advancements in diagnostic technologies. The growing burden of emerging and transboundary animal diseases is further accelerating demand for reliable testing solutions. Rising global populations of companion animals and production livestock are also strengthening overall market demand. Pet ownership is increasing steadily, particularly for dogs and cats, while owners are showing greater willingness to invest in routine wellness screening and preventive care. At the same time, technological progress in molecular diagnostics, PCR-based methods, next-generation sequencing, biomarker assays, and portable point-of-care systems is improving the speed, precision, and accessibility of disease detection.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $5.3 Billion |
| Forecast Value | $12.6 Billion |
| CAGR | 9.1% |
The consumables segment accounted for a 51.3% share in 2025 and continues to grow at a CAGR of 9.2% during 2026-2035. This dominance is driven by its essential role across diagnostic workflows and its recurring revenue structure. Consumables include reagents, diagnostic kits, assay cartridges, blood collection tubes, slides, calibration tools, and control materials, which are widely used across veterinary hospitals, clinics, diagnostic laboratories, and research centers.
The lab-based testing segment is projected to reach USD 7.1 billion by 2035. This segment remains widely preferred due to its ability to support advanced diagnostic procedures, including molecular testing, microbiological analysis, immunoassays, toxicology screening, and specialized pathology evaluations. These tests require advanced laboratory infrastructure, skilled professionals, and controlled environments to ensure high accuracy and reliability in disease detection.
North America Veterinary Diagnostics Market held 46.5% share in 2025. The region's dominance is supported by advanced veterinary healthcare infrastructure, high pet ownership levels, strong diagnostic adoption rates, and widespread use of innovative animal health technologies. The presence of established diagnostic companies, extensive laboratory networks, and well-developed veterinary care systems further reinforces regional market strength and sustained growth.
Key industry participants include Zoetis, IDEXX Laboratories, bioMerieux, Bio-Rad Laboratories, Thermo Fisher Scientific, Neogen, QIAGEN, Virbac, Randox Laboratories, Fujifilm, Mindray Animal Medical Technology, BioNote, IDvet, INDICAL Bioscience, MEGACOR Diagnostik, Eurolyser Diagnostica, Agrolabo, Biochek, and GD Animal Health (Royal GD). Companies in the veterinary diagnostics market are strengthening their market position by focusing on continuous innovation in diagnostic technologies that improve the speed, accuracy, and reliability of test results. Many players are expanding their portfolios with advanced molecular diagnostics, multiplex testing platforms, and automated laboratory systems. Strategic collaborations with veterinary clinics, hospitals, and diagnostic laboratories are helping companies improve distribution reach and service integration. Firms are also investing heavily in research and development to introduce next-generation sequencing, biomarker-based assays, and portable diagnostic solutions. Expansion into emerging markets with growing pet populations and livestock industries is another key focus area.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research approach
- 1.3 Quality commitments
- 1.3.1 GMI AI policy & data integrity commitment
- 1.3.1.1 Source consistency protocol
- 1.3.1 GMI AI policy & data integrity commitment
- 1.4 Research trail & confidence scoring
- 1.4.1 Research trail components
- 1.4.2 Scoring components
- 1.5 Data collection
- 1.5.1 Partial list of primary sources
- 1.6 Data mining sources
- 1.6.1 Paid sources
- 1.6.1.1 Sources, by region
- 1.6.1 Paid sources
- 1.7 Base estimates and calculations
- 1.7.1 Base year calculation for any one approach
- 1.8 Forecast model
- 1.8.1 Quantified market impact analysis
- 1.8.1.1 Mathematical impact of growth parameters on forecast
- 1.8.1 Quantified market impact analysis
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Business trends
- 2.2.2 Product trends
- 2.2.3 Modality trends
- 2.2.4 Technology trends
- 2.2.5 Application trends
- 2.2.6 Animal type trends
- 2.2.7 End use trends
- 2.2.8 Regional trends
- 2.3 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Value addition at each stage
- 3.1.3 Factors affecting the value chain
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Growing trend of adopting pet animals
- 3.2.1.2 Rising prevalence of foodborne and zoonotic diseases
- 3.2.1.3 Favorable government initiatives
- 3.2.1.4 Advancements in companion diagnostics
- 3.2.1.5 Increasing adoption of pet insurance
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Prohibitive cost associated with animal tests
- 3.2.2.2 Low out of pocket expenditure on veterinary care
- 3.2.3 Market opportunities
- 3.2.3.1 Expansion of point-of-care (POC) diagnostic solutions
- 3.2.3.2 Integration of AI and data analytics in diagnostics
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technological and innovation landscape
- 3.4.1 Current technological trends
- 3.4.2 Emerging technologies (Driven by Primary Research)
- 3.5 Pricing analysis (Driven by Primary Research)
- 3.5.1 Historic price trend analysis
- 3.5.2 Pricing analysis, by drug type
- 3.6 Regulatory landscape (Driven by Primary Research)
- 3.6.1 North America
- 3.6.2 Europe
- 3.6.3 Asia Pacific
- 3.6.4 Latin America
- 3.6.5 MEA
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Impact of AI and Generative AI on the market (Driven by Primary Research)
- 3.10 Investment and funding landscape (Driven by Primary Research)
- 3.11 Future market trends (Driven by Primary Research)
- 3.12 Pet population statistics
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Merger and acquisition
- 4.6.2 Partnership and collaboration
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Product, 2022 - 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Consumables
- 5.3 Instruments
- 5.4 Softwares
Chapter 6 Market Estimates and Forecast, By Modality, 2022 - 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Point-of-care testing (POC)
- 6.3 Lab-based testing
Chapter 7 Market Estimates and Forecast, By Technology, 2022 - 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Clinical biochemistry
- 7.2.1 Glucose monitoring
- 7.2.2 Blood gas and electrolyte analysis
- 7.2.3 Other clinical biochemistry tests
- 7.3 Immunodiagnostics
- 7.3.1 Lateral flow assays
- 7.3.2 ELISA
- 7.3.3 Immunoassay analyzers
- 7.3.4 Other immunodiagnostic tests
- 7.4 Molecular diagnostics
- 7.4.1 PCR
- 7.4.2 Microarrays
- 7.4.3 Other molecular diagnostic tests
- 7.5 Hematology
- 7.6 Urinalysis
- 7.7 Diagnostic imaging (inclusive of AI assisted)
- 7.8 Other technologies
Chapter 8 Market Estimates and Forecast, By Application, 2022 - 2035 ($ Mn)
- 8.1 Key trends
- 8.2 Bacteriology
- 8.3 Pathology
- 8.4 Parasitology
- 8.5 Other applications
Chapter 9 Market Estimates and Forecast, By Animal Type, 2022 - 2035 ($ Mn)
- 9.1 Key trends
- 9.2 Companion animals
- 9.2.1 Dogs
- 9.2.2 Cats
- 9.2.3 Horses
- 9.2.4 Other companion animals
- 9.3 Farm animals
- 9.3.1 Cattle
- 9.3.2 Swine
- 9.3.3 Poultry
- 9.3.4 Other farm animals
Chapter 10 Market Estimates and Forecast, By End Use, 2022 - 2035 ($ Mn)
- 10.1 Key trends
- 10.2 Veterinary hospitals and clinics
- 10.3 Diagnostic labs
- 10.4 Home care settings
- 10.5 Other end users
Chapter 11 Market Estimates and Forecast, By Region, 2022 - 2035 ($ Mn)
- 11.1 Key trends
- 11.2 North America
- 11.2.1 U.S.
- 11.2.2 Canada
- 11.3 Europe
- 11.3.1 Germany
- 11.3.2 UK
- 11.3.3 France
- 11.3.4 Italy
- 11.3.5 Spain
- 11.3.6 Netherlands
- 11.4 Asia Pacific
- 11.4.1 China
- 11.4.2 Japan
- 11.4.3 India
- 11.4.4 Australia
- 11.4.5 South Korea
- 11.5 Latin America
- 11.5.1 Brazil
- 11.5.2 Mexico
- 11.5.3 Argentina
- 11.6 Middle East and Africa
- 11.6.1 South Africa
- 11.6.2 Saudi Arabia
- 11.6.3 UAE
Chapter 12 Company Profiles
- 12.1 Agrolabo
- 12.2 Bio-Rad Laboratories
- 12.3 bioMerieux
- 12.4 BioNote
- 12.5 Biochek
- 12.6 Eurolyser Diagnostica
- 12.7 Fujifilm
- 12.8 GD Animal Health (Royal GD)
- 12.9 IDEXX Laboratories
- 12.10 IDvet
- 12.11 INDICAL Bioscience
- 12.12 MEGACOR Diagnostik
- 12.13 Mindray Animal Medical Technology
- 12.14 Neogen
- 12.15 QIAGEN
- 12.16 Randox Laboratories
- 12.17 Thermo Fisher Scientific
- 12.18 Virbac
- 12.19 Zoetis

 2026-2034年全球獸醫診斷市場規模、佔有率、趨勢和成長分析報告
 獸用穿戴裝置市場:預測至 2034 年 - 按產品、動物類型、技術、連接方式、應用、最終用戶、分銷管道和地區分類的全球分析
 獸用免疫診斷市場-2026-2032年全球市場預測獸醫診斷設備市場-全球市場預測(2026-2032年)獸醫診斷市場:2026-2032年全球市場預測(依產品類型、動物種類、檢測類型、檢體類型、技術、疾病類型和最終用戶分類)
 2026年全球獸用快速症狀聚合酵素鏈鎖反應(PCR)檢測板市場報告
 獸醫診斷服務市場分析及預測(至2035年):類型、產品類型、服務、技術、組件、應用、最終用戶、設備、解決方案、交付形式
 獸用免疫診斷市場-全球產業規模、佔有率、趨勢、機會與預測:按產品類型、按動物類型分類,2021-2031年
 獸醫診斷市場報告:按產品類型、技術、動物種類、疾病、最終用戶和地區分類(2026-2034 年)
 獸醫診斷市場規模、佔有率和趨勢分析報告:按產品、動物、檢測類別、最終用途、地區和細分市場預測(2026-2033 年)