


 |
市場調查報告書
商品編碼
2083297
可攜式逆變發電機市場機會、成長促進因素、產業趨勢分析及2026-2035年預測Portable Inverter Generator Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球可攜式逆變發電機市場預計到 2025 年將達到 55 億美元,年複合成長率為 5.2%,到 2035 年將達到 91 億美元。
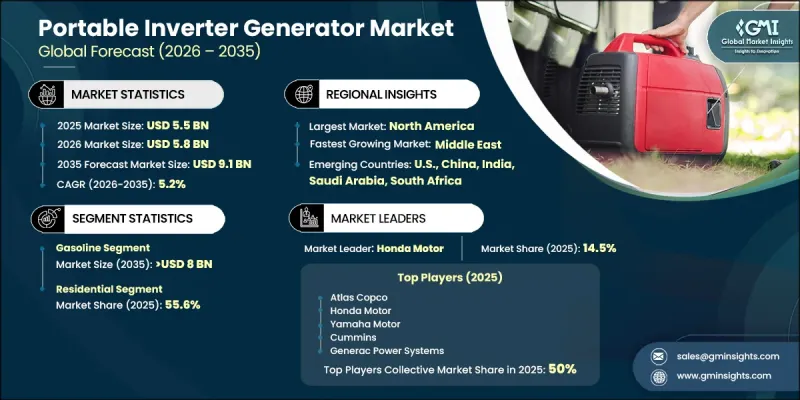
電力供應不穩定、停電頻率增加以及基礎建設持續推進所推動的消費者偏好轉變,共同塑造了這個市場格局。可攜式逆變發電機正從單純的備用電源設備發展成為住宅、商業和休閒娛樂等各種場景下不可或缺的電力解決方案。在緊急情況和離網環境下,對可靠電力的需求日益成長,推動了全球市場的滲透。對緊湊、節能、低排放電力系統的日益依賴,進一步加速了市場需求。此外,智慧監控能力的提升、安全機制的改進以及運作效率的提高,也增強了產品的吸引力。對更清潔的替代能源的日益關注以及更嚴格的排放法規,也在影響產品的創新,而偏遠和發展中地區對電氣化日益成長的需求,則持續支撐著市場的持續成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 起始金額 | 55億美元 |
| 預測金額 | 91億美元 |
| 複合年成長率 | 5.2% |
預計2035年,汽油動力可攜式逆變發電機市場規模將達80億美元。該市場發展勢頭強勁,主要得益於其在封閉和對噪音敏感的環境中安靜運行的特性。這些產品因其易於儲存燃料、減少加油麻煩、設計緊湊和維護簡單而備受青睞。其成本績效和操作柔軟性使其在住宅、商業和休閒領域得到廣泛應用,進一步推動了市場擴張。
預計到2025年,住宅市場將佔據55.6%的市場佔有率,這主要得益於人們對電力可靠性的日益關注以及應對緊急情況準備的不斷加強。攜帶式逆變可攜式在家庭中的應用日益普及,尤其是在電網基礎設施不穩定或易受極端天氣影響的地區,因為它們即使在停電期間也能提供穩定的電力供應。其運作安靜、便於攜帶以及與敏感電子設備的兼容性,持續推動它們在家庭備用電源領域的應用。
美國可攜式逆變發電機市場預計2025年將達到18億美元。建設活動的活性化和偏遠地區商業場所的擴張推動了對可靠緊急電源解決方案的需求,以確保即使在電網故障期間也能維持業務連續性。燃油效率的提高、噪音的降低以及符合環保標準的引擎設計等技術進步,進一步促進了美國市場的成長。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 原物料供應及採購分析
- 生產能力評估
- 供應鏈韌性與風險因素
- 配電網路分析
- 影響產業的因素
- 成長促進因素
- 產業潛在風險與挑戰
- 監理情勢
- 成長潛力分析
- 波特的分析
- PESTLE分析
- 成本結構分析:可攜式逆變發電機
- 新機會與趨勢
- 數位化和物聯網整合
- 未開發市場和應用領域的成長
- 投資分析及未來展望
- 價格趨勢分析
- 按地區
- 額定功率
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧最佳化生產
- 預測性維護和故障檢測
第4章 競爭情勢
- 介紹
- 企業市佔率分析:按地區分類
- 北美洲
- 歐洲
- 亞太地區
- 中東
- 非洲
- 拉丁美洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場規模及預測:額定功率,2022-2035年
- 小於1千伏安
- 1 kVA~2 kVA
- 2 kVA~3 kVA
- 3 kVA~4 kVA
- 超過 4 千伏安
第6章 市場規模及預測:依動力來源分類,2022-2035年
- 汽油
- 柴油引擎
- 其他
第7章 市場規模及預測:依應用領域分類,2022-2035年
- 住宅
- 戶外運動
- 建造
- 其他
第8章 市場規模及預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 俄羅斯
- 英國
- 德國
- 法國
- 西班牙
- 奧地利
- 義大利
- 亞太地區
- 中國
- 澳洲
- 印度
- 日本
- 韓國
- 印尼
- 馬來西亞
- 泰國
- 越南
- 菲律賓
- 新加坡
- 中東
- 沙烏地阿拉伯
- UAE
- 卡達
- 土耳其
- 伊朗
- 阿曼
- 非洲
- 埃及
- 奈及利亞
- 阿爾及利亞
- 南非
- 莫三比克
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 智利
第9章:公司簡介
- A-iPower Corp.
- Atlas Copco
- Briggs & Stratton
- Caterpillar
- Champion Power Equipment
- Changzhou ITC Power Equipment Manufacturing Co.
- Cummins
- Deere & Company
- DuroMax Power Equipment
- Generac Power Systems
- Himalayan Power Equipments
- HIMOINSA
- Honda Motor
- Kirloskar
- Kohler
- Mitsubishi Heavy Industries
- Wacker Neuson
- WEN Products
- Westinghouse Electric Corporation
- Yamaha Motor
The Global Portable Inverter Generator Market was valued at USD 5.5 billion in 2025 and is estimated to grow at a CAGR of 5.2% to reach USD 9.1 billion by 2035.
The market is shaped by recurring power supply instability, rising frequency of outages, and evolving consumer preferences supported by ongoing infrastructure development. Portable inverter generators have shifted from being optional backup devices to essential power solutions across residential, commercial, and recreational use cases. Their growing role in providing reliable electricity during emergencies and off-grid situations is strengthening market adoption globally. Increasing reliance on compact, fuel-efficient, and low-emission power systems is further accelerating demand. In addition, advancements in smart monitoring features, improved safety mechanisms, and enhanced operational efficiency are expanding product appeal. Growing emphasis on cleaner energy alternatives and stricter emission norms is also influencing product innovation, while rising electrification needs in remote and developing regions continue to support sustained market expansion.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $5.5 Billion |
| Forecast Value | $9.1 Billion |
| CAGR | 5.2% |
The gasoline-powered portable inverter generators segment is expected to reach USD 8 billion by 2035. This segment is gaining strong traction due to its suitability for quiet operation in enclosed and noise-sensitive environments. These units are valued for their easy fuel storage, reduced refueling inconvenience, compact structure, and simplified maintenance requirements. Their cost-effectiveness and operational flexibility make them widely applicable across residential, commercial, and recreational settings, further driving segment expansion.
The residential segment accounted for 55.6% share in 2025, supported by rising concerns over power reliability and increasing preparedness for emergency situations. Households are increasingly adopting portable inverter generators due to their ability to deliver stable electricity during outages, particularly in areas with unstable grid infrastructure and exposure to extreme weather conditions. Their quiet operation, portability, and compatibility with sensitive electronic devices continue to reinforce their adoption in home backup applications.
U.S. Portable Inverter Generator Market was valued at USD 1.8 billion in 2025. Growth in construction activities and expansion of remote operational sites are driving demand for reliable backup power solutions to ensure uninterrupted operations during grid failures. Technological improvements, including enhanced fuel efficiency, reduced noise output, and environmentally compliant engine designs, are further supporting market expansion across the country.
Key industry participants include Yamaha Motor, Cummins, Caterpillar, Honda Motor, Generac Power Systems, Kohler, Briggs & Stratton, Atlas Copco, Deere & Company, Mitsubishi Heavy Industries, Westinghouse Electric Corporation, Wacker Neuson, HIMOINSA, Kirloskar, Champion Power Equipment, WEN Products, DuroMax Power Equipment, A-iPower Corp., Changzhou ITC Power Equipment Manufacturing Co., and Himalayan Power Equipments. Companies in the portable inverter generator market are strengthening their competitive position by focusing on advanced product innovation, improved fuel efficiency, and reduced emissions. Manufacturers are investing heavily in smart generator technologies featuring remote monitoring, automated load management, and enhanced safety systems. Expanding product portfolios to address residential, commercial, and recreational applications is also a key focus area. Firms are increasing their distribution networks and strengthening online sales channels to improve market reach. Strategic collaborations with energy solution providers and equipment rental companies are further enhancing adoption. In addition, companies are optimizing engine design and integrating lightweight materials to improve portability and user convenience.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research trail & confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Market estimates & forecasts parameters
- 1.8 Forecast model
- 1.8.1 Quantified market impact analysis
- 1.8.1.1 Mathematical impact of growth parameters on forecast
- 1.8.1 Quantified market impact analysis
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
- 1.10 Market definitions
Chapter 2 Executive Summary
- 2.1 Industry synopsis, 2022 - 2035
- 2.1.1 Business trends
- 2.1.2 Power rating trends
- 2.1.3 Power source trends
- 2.1.4 Application trends
- 2.1.5 Regional trends
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Raw material availability & sourcing analysis
- 3.1.2 Manufacturing capacity assessment
- 3.1.3 Supply chain resilience & risk factors
- 3.1.4 Distribution network analysis
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls & challenges
- 3.3 Regulatory landscape
- 3.4 Growth potential analysis
- 3.5 Porter's analysis
- 3.5.1 Bargaining power of suppliers
- 3.5.2 Bargaining power of buyers
- 3.5.3 Threat of new entrants
- 3.5.4 Threat of substitutes
- 3.6 PESTEL analysis
- 3.6.1 Political factors
- 3.6.2 Economic factors
- 3.6.3 Social factors
- 3.6.4 Technological factors
- 3.6.5 Legal factors
- 3.6.6 Environmental factors
- 3.7 Cost structure analysis of portable inverter generator
- 3.8 Emerging opportunities & trends
- 3.9 Digitalization & IoT integration
- 3.10 Growth in untapped markets & applications
- 3.11 Investment analysis & future prospects
- 3.12 Price trend analysis (USD/Unit) (Driven by Primary Research)
- 3.12.1 By region (Driven by Primary Research)
- 3.12.2 By power rating (Driven by Primary Research)
- 3.13 Impact of AI & Generative AI on the market (Driven by Primary Research)
- 3.13.1 AI-Driven production optimization (Driven by Primary Research)
- 3.13.2 Predictive maintenance & fault detection (Driven by Primary Research)
Chapter 4 Competitive Landscape, 2026
- 4.1 Introduction
- 4.2 Company market share analysis, by region, 2025
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Middle East
- 4.2.5 Africa
- 4.2.6 Latin America
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans & funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Size and Forecast, By Power Rating, 2022 - 2035 (USD Million & '000 Units)
- 5.1 Key trends
- 5.2 < 1 kVA
- 5.3 1 kVA - 2 kVA
- 5.4 > 2 kVA - 3 kVA
- 5.5 > 3 kVA - 4 kVA
- 5.6 > 4 kVA
Chapter 6 Market Size and Forecast, By Power Source, 2022 - 2035 (USD Million & '000 Units)
- 6.1 Key trends
- 6.2 Gasoline
- 6.3 Diesel
- 6.4 Others
Chapter 7 Market Size and Forecast, By Application, 2022 - 2035 (USD Million & '000 Units)
- 7.1 Key trends
- 7.2 Residential
- 7.3 Outdoor sports
- 7.4 Construction
- 7.5 Others
Chapter 8 Market Size and Forecast, By Region, 2022 - 2035 (USD Million & Units)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Russia
- 8.3.2 UK
- 8.3.3 Germany
- 8.3.4 France
- 8.3.5 Spain
- 8.3.6 Austria
- 8.3.7 Italy
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 Australia
- 8.4.3 India
- 8.4.4 Japan
- 8.4.5 South Korea
- 8.4.6 Indonesia
- 8.4.7 Malaysia
- 8.4.8 Thailand
- 8.4.9 Vietnam
- 8.4.10 Philippines
- 8.4.11 Singapore
- 8.5 Middle East
- 8.5.1 Saudi Arabia
- 8.5.2 UAE
- 8.5.3 Qatar
- 8.5.4 Turkey
- 8.5.5 Iran
- 8.5.6 Oman
- 8.6 Africa
- 8.6.1 Egypt
- 8.6.2 Nigeria
- 8.6.3 Algeria
- 8.6.4 South Africa
- 8.6.5 Mozambique
- 8.7 Latin America
- 8.7.1 Brazil
- 8.7.2 Mexico
- 8.7.3 Argentina
- 8.7.4 Chile
Chapter 9 Company Profiles
- 9.1 A-iPower Corp.
- 9.2 Atlas Copco
- 9.3 Briggs & Stratton
- 9.4 Caterpillar
- 9.5 Champion Power Equipment
- 9.6 Changzhou ITC Power Equipment Manufacturing Co.
- 9.7 Cummins
- 9.8 Deere & Company
- 9.9 DuroMax Power Equipment
- 9.10 Generac Power Systems
- 9.11 Himalayan Power Equipments
- 9.12 HIMOINSA
- 9.13 Honda Motor
- 9.14 Kirloskar
- 9.15 Kohler
- 9.16 Mitsubishi Heavy Industries
- 9.17 Wacker Neuson
- 9.18 WEN Products
- 9.19 Westinghouse Electric Corporation
- 9.20 Yamaha Motor

 全球可攜式逆變發電機市場規模、佔有率、趨勢及成長分析報告(2026-2034年)
 可攜式逆變發電機市場規模、佔有率和成長分析:按燃料類型、輸出功率、相數、應用、最終用戶、分銷管道和地區分類-2026-2033年產業預測
 可攜式逆變發電機市場-全球產業規模、佔有率、趨勢、機會、預測:按功率等級、電源、最終用戶、地區和競爭格局分類,2021-2031年
 全球汽油可攜式逆變發電機市場全球建築可攜式逆變發電機市場全球柴油可攜式逆變發電機市場
 柴油攜帶式逆變發電機市場機會、成長動力、產業趨勢分析及 2025-2034 年預測建築攜帶式逆變發電機市場機會、成長動力、產業趨勢分析及 2025-2034 年預測