

 |
市場調查報告書
商品編碼
2083253
烤麵包機市場機會、成長要素、產業趨勢分析及 2026-2035 年預測。Toaster Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球烤麵包機市場預計到 2025 年將達到 44 億美元,年複合成長率為 5.5%,到 2035 年將達到 75 億美元。
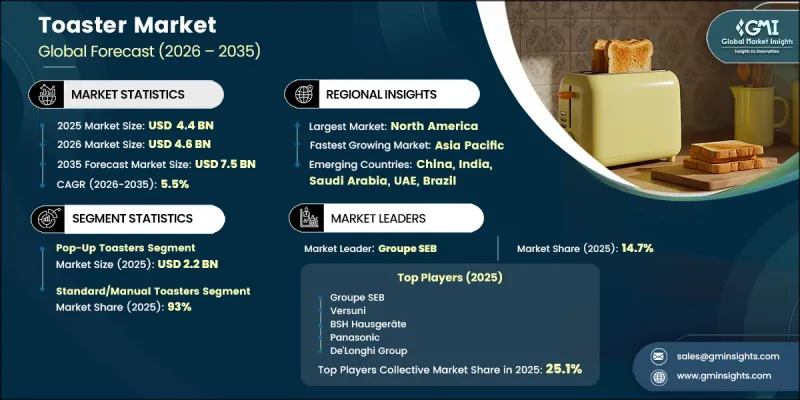
這種成長模式是由住宅環境中互聯廚房生態系統的並行發展以及開發中國家有組織的餐飲服務網路的擴張共同塑造的。儘管北美和西歐等成熟市場仍然是最大的收入來源,但亞太地區正崛起為最具活力的成長區域,這得益於都市區密度的上升、中等收入家庭的擴大以及酒店業和快餐連鎖店(QSR)網路的快速發展。亞洲、非洲和拉丁美洲城市人口的成長擴大了家用電器的消費群,而透過智慧家居系統實現的數位整合正在烤麵包機市場創造新的產品類型。同時,全球飯店業的復甦和食品服務連鎖店的持續擴張也推動了對商用烤麵包機解決方案的需求。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 44億美元 |
| 預測金額 | 75億美元 |
| 複合年成長率 | 5.5% |
彈出式烤麵包機市場價值 22 億美元,佔市場佔有率的 51%,預計到 2035 年將以 5.5% 的複合年成長率成長。該市場保持其主導地位,是因為它被廣泛用作家庭中最主要、最經濟實惠的烤麵包解決方案,並且在成熟市場中得到了大規模安裝的支持,這些市場的更換需求持續推動著穩定的需求。
預計到2025年,手排和標準烤麵包機市場規模將達到40億美元,佔市場佔有率的93%。其主導地位歸功於其操作簡便、經濟實惠且易於購買,使其成為全球住宅和商用用戶的首選。
北美烤麵包機市場價值 14 億美元,佔市場佔有率的 33%,預計到 2035 年將以 5.2% 的複合年成長率成長。美國引領區域需求,這得益於家用電器頻繁的更換週期以及涵蓋實體店和線上銷售管道的成熟的高階零售生態系統。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 機會
- 成長潛力分析
- 價格趨勢
- 對過去價格趨勢的分析
- 定價策略:按業務類型分類
- 監理框架
- 產品安全標準與認證(UL、CE、ETL、BIS、PSE)
- 能源效率法規(能源之星、歐盟生態設計指令)
- 符合RoHS和WEEE要求:有害物質管制
- 智慧家庭設備的資料隱私和物聯網安全相關法規(GDPR、CCPA)
- 主要國家的貿易政策、關稅和進出口法規
- 監理藍圖:2030 年前的未來變化
- 波特五力分析
- PESTLE分析
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 人工智慧和生成式人工智慧對市場的影響
- 人工智慧正在改變傳統的經營模式。
- 按客戶群分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 消費行為分析
- 購買模式
- 偏好分析
- 不同地區的消費行為差異
- 電子商務對購買決策的影響
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 彈出式烤麵包機
- 可烤兩片麵包的彈出式烤麵包機
- 四片式彈出式烤麵包機
- 寬槽彈出式烤麵包機
- 烤麵包機
- 普通烤麵包機
- 對流式烤麵包機
- 帶氣炸功能的烤箱
- 輸送機式烤麵包機
- 電動輸送機烤麵包機
- 瓦斯動力輸送機式烤麵包機
- 其他(烤麵包機/帕尼尼烤架等)
第6章 市場估計與預測:依技術分類,2022-2035年
- 標準/手動烤麵包機
- 智慧/連網烤麵包機
第7章 市場估計與預測:依價格區間分類,2022-2035年
- 價格低廉(100美元以下)
- 中價位(100-299美元)
- 高價位(超過300美元)
第8章 市場估算與預測:依最終使用者分類,2022-2035年
- 住宅
- 商業的
- 飯店和住宿
- 食品服務業
- 教育機構
第9章 市場估價與預測:依通路分類,2022-2035年
- 線上
- 電子商務
- 公司網站
- 離線
- 超級市場/大賣場
- 文具書店
- 其他(例如學校和校園商店的供應鏈管理)
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 荷蘭
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 全球主要公司
- Breville Group
- BSH Hausgerate
- De'Longhi
- Groupe SEB
- Hamilton Beach Brands
- Spectrum Brands(Russell Hobbs)
- Versuni
- 本地公司
- Bajaj Electricals
- Gorenje
- Havells India
- Midea
- Panasonic
- Severin Elektrogerate
- Taurus
- 新興企業和專業公司
- Balmuda
- Dualit
- Hatco Corporation
- Magimix SNC
- Middleby Corp
- Revolution Cooking
- Tineco
The Global Toaster Market was valued at USD 4.4 billion in 2025 and is estimated to grow at a CAGR of 5.5% to reach USD 7.5 billion by 2035.
The growth pattern is shaped by the parallel rise of connected kitchen ecosystems in residential environments and the expansion of organized foodservice networks in developing economies. Mature markets such as North America and Western Europe continue to contribute the largest revenue base, while Asia Pacific is emerging as the most dynamic growth region due to rising urban density, expanding middle-income households, and rapid development of hospitality and quick-service restaurant networks. Expanding urban populations across Asia, Africa, and Latin America are widening the consumer base for home appliances, while digital integration through smart home systems has created an upgraded product category within the toaster landscape. At the same time, the recovery of global hospitality and the continued scaling of foodservice chains are reinforcing demand for commercial-grade toasting solutions.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $4.4 Billion |
| Forecast Value | $7.5 Billion |
| CAGR | 5.5% |
The pop-up toasters segment accounted for USD 2.2 billion, representing 51% share and registering a CAGR of 5.5% through 2035. This segment maintains dominance due to its widespread use in households as the primary and most affordable bread-toasting solution, supported by a large installed base in mature markets where replacement purchases remain a consistent driver of demand.
The manual and standard toasters segment reached USD 4 billion in 2025, accounting for 93% share. Their leadership is attributed to simple functionality, cost efficiency, and widespread availability, making them the preferred option across both residential and commercial end users globally.
North America Toaster Market captured USD 1.4 billion, capturing 33% share and projected to grow at a CAGR of 5.2% through 2035. The United States leads regional demand, driven by frequent appliance replacement cycles and a well-established premium retail ecosystem spanning both physical and online distribution channels.
Key companies operating in the global toaster market include Breville Group, Groupe SEB, BSH Hausgerate, De'Longhi, Hamilton Beach Brands, Spectrum Brands (Russell Hobbs), Versuni, Midea, Panasonic, Bajaj Electricals, Havells India, Gorenje, Severin Elektrogerate, Taurus, Balmuda, Dualit, Hatco Corporation, Magimix SNC, Middleby Corporation, Revolution Cooking, and Tineco. Companies in the toaster market are focusing on product innovation centered around energy efficiency, faster heating performance, and improved durability to enhance consumer appeal. Many manufacturers are integrating smart connectivity features and digital controls to align with evolving connected kitchen ecosystems. Strategic expansion of product portfolios across budget, mid-range, and premium categories is helping companies target diverse consumer groups across regions. Strong emphasis is being placed on expanding distribution through e-commerce platforms and organized retail networks to improve market penetration. Partnerships with hospitality and foodservice operators are strengthening commercial demand visibility.
Table of Contents
Chapter 1 Methodology and scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Product type
- 2.2.3 Technology
- 2.2.4 Price range
- 2.2.5 End users
- 2.2.6 Distribution channel
Chapter 3 Industry insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls & challenges
- 3.2.3 Opportunities
- 3.3 Growth potential analysis
- 3.4 Price trends
- 3.4.1 Historical price trend analysis
- 3.4.2 Pricing strategy by player type
- 3.5 Regulatory framework
- 3.5.1 Product Safety Standards & Certifications (UL, CE, ETL, BIS, PSE)
- 3.5.2 Energy Efficiency Regulations (Energy Star, EU Ecodesign Directive)
- 3.5.3 RoHS & WEEE Compliance:Hazardous Substance Restrictions
- 3.5.4 Smart Appliance Data Privacy & IoT Security Regulations (GDPR, CCPA)
- 3.5.5 Trade Policies, Tariffs & Import/Export Regulations by Key Country
- 3.5.6 Regulatory Roadmap: Upcoming Changes Through 2030
- 3.6 Porter's five forces analysis
- 3.7 PESTEL analysis
- 3.8 Trade Data Analysis (Based on Paid Database) (HS Code: 851672)
- 3.8.1 Import/export volume & value trends
- 3.8.2 Key trade corridors & tariff impact
- 3.9 Impact of AI & generative AI on the market
- 3.9.1 AI-driven disruption of traditional business models
- 3.9.2 GenAI use cases & adoption roadmap by customer segment
- 3.9.3 Risks, limitations & regulatory considerations
- 3.10 Future market trends
- 3.11 Technology and innovation landscape
- 3.11.1 Current technological trends
- 3.11.2 Emerging technologies
- 3.12 Consumer behavior analysis
- 3.12.1 Purchasing patterns
- 3.12.2 Preference analysis
- 3.12.3 Regional variations in consumer behavior
- 3.12.4 Impact of e-commerce on buying decisions
Chapter 4 Competitive landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Latin America
- 4.2.5 MEA
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates & Forecast, By Product Type, 2022 - 2035 ($Billion, Thousand Units)
- 5.1 Key trends
- 5.2 Pop-up toasters
- 5.2.1 2-slice pop-up toasters
- 5.2.2 4-slice pop-up toasters
- 5.2.3 Wide-slot pop-up toasters
- 5.3 Toaster ovens
- 5.3.1 Standard toaster ovens
- 5.3.2 Convection toaster ovens
- 5.3.3 Air fryer toaster ovens
- 5.4 Conveyor toasters
- 5.4.1 Electric conveyor toasters
- 5.4.2 Gas-powered conveyor toasters
- 5.5 Others (toaster grills / panini press etc.)
Chapter 6 Market Estimates & Forecast, By Technology, 2022 - 2035 ($Billion, Thousand Units)
- 6.1 Key trends
- 6.2 Standard/manual toasters
- 6.3 Smart/connected toasters
Chapter 7 Market Estimates & Forecast, By Price Range, 2022 - 2035 ($Billion, Thousand Units)
- 7.1 Key trends
- 7.2 Low (below $100)
- 7.3 Medium ($100-$299)
- 7.4 High ($300 and above)
Chapter 8 Market Estimates & Forecast, By End Users, 2022 - 2035 ($Billion, Thousand Units)
- 8.1 Key trends
- 8.2 Residential
- 8.3 Commercial
- 8.3.1 Hospitality & lodging
- 8.3.2 Food service establishments
- 8.3.3 Education institute
Chapter 9 Market Estimates & Forecast, By Distribution Channel, 2022 - 2035 ($Billion, Thousand Units)
- 9.1 Key trends
- 9.2 Online
- 9.2.1 E-commerce
- 9.2.2 Company websites
- 9.3 Offline
- 9.3.1 Supermarkets/hypermarket
- 9.3.2 Specialty stationery & bookstores
- 9.3.3 Others (school supply chains & campus stores etc.)
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 ($Billion, Thousand Units)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Spain
- 10.3.5 Italy
- 10.3.6 Netherlands
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 Japan
- 10.4.3 India
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 MEA
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Key Players
- 11.1.1 Breville Group
- 11.1.2 BSH Hausgerate
- 11.1.3 De'Longhi
- 11.1.4 Groupe SEB
- 11.1.5 Hamilton Beach Brands
- 11.1.6 Spectrum Brands (Russell Hobbs)
- 11.1.7 Versuni
- 11.2 Regional Players
- 11.2.1 Bajaj Electricals
- 11.2.2 Gorenje
- 11.2.3 Havells India
- 11.2.4 Midea
- 11.2.5 Panasonic
- 11.2.6 Severin Elektrogerate
- 11.2.7 Taurus
- 11.3 Emerging/Niche Specialists
- 11.3.1 Balmuda
- 11.3.2 Dualit
- 11.3.3 Hatco Corporation
- 11.3.4 Magimix SNC
- 11.3.5 Middleby Corp
- 11.3.6 Revolution Cooking
- 11.3.7 Tineco


