


 |
市場調查報告書
商品編碼
2083056
傾斜式旋翼機市場商機、成長要素、產業趨勢分析及2026-2035年預測。Tilt-Rotor Aircraft Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

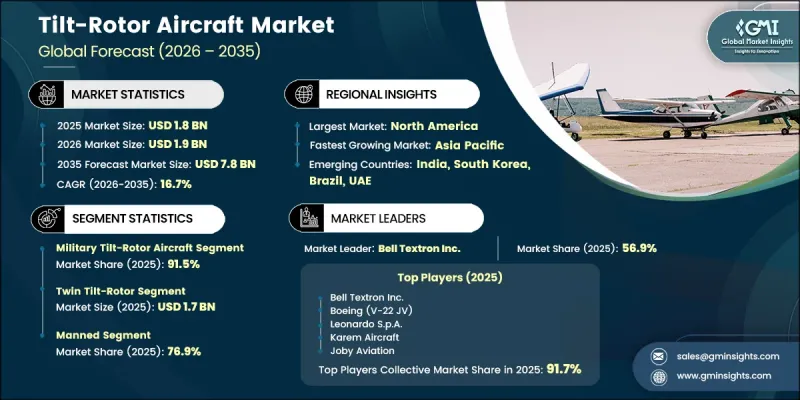
2025年全球傾斜式旋翼機市場價值為18億美元,預計2035年將以16.7%的複合年成長率成長至78億美元。
隨著國防機構持續投資研發兼具垂直起降能力及固定翼飛機速度及航程的先進飛機,全球傾斜式旋翼機市場正經歷強勁成長。對增強戰術性機動性的需求不斷成長、軍用航空部隊的現代化以及在特殊任務領域的部署不斷擴大,都為市場創造了機會。人道主義空中行動、長途商業運輸和海上物流服務領域日益成長的需求也推動了該行業的發展。此外,技術的不斷進步正在加速下一代傾傾斜式旋翼機的研發,這些飛機具有更高的運作效率、更強的可靠性和更優異的飛行性能。對航空創新和飛機現代化項目的投入增加,進一步推動了市場擴張。隨著製造商不斷開發適用於國防和商業應用的先進平台,預計在預測期內,傾轉傾斜式旋翼市場的需求結構將更加廣泛和多元化。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 18億美元 |
| 預計金額 | 78億美元 |
| 複合年成長率 | 16.7% |
隨著製造商將研發重心拓展至多個應用領域,傾斜式旋翼機產業正不斷突破傳統的以國防為中心的結構。對民用認證項目、自主飛行技術和先進飛機平台的持續投入,正為市場成長創造新的機會。現代數位線傳飛行控制系統已成為主流設計方案,在複雜飛行機動中提供更高的精度和穩定性,同時提升飛機的整體性能和運作安全性。持續的技術創新正在重塑飛機發展策略,並增強全球傾斜式旋翼機市場的長期發展前景。
到2025年,軍用傾斜式旋翼機市場佔有率將達到91.5%。國防機構的積極採購持續鞏固了該領域的主導地位,因為軍方優先考慮兼具垂直起降能力和高速前飛能力的飛機。軍用傾傾斜式旋翼機能夠在多種任務環境下高效運行,並提供卓越的作戰柔軟性,這使其與傳統飛機區分開來。預計較長的專案週期、持續的採購週期以及不斷進行的飛機現代化改造將使該領域在整個預測期內保持主導地位。
預計2025年,雙傾轉傾斜式旋翼機市場規模將達17億美元。其主導地位反映了該機型作為現有生產項目和在研機型首選技術配置,在業界廣受認可。長期營運經驗證明了其高可靠性、耐久性和可維護性,贏得了採購機構和航空管理部門的廣泛信賴。均衡的飛行性能、成熟的技術、完善的維護能力和全面的飛行員訓練體系,持續鞏固該機型在軍事和新興商業應用領域的主導地位。
到2025年,北美將佔據傾斜式旋翼機市場86.4%的佔有率。該地區的成長持續得益於對先進垂直起降飛機的持續投資,以及旨在提升航空能力的長期國防現代化舉措。持續的採購項目、不斷擴大的技術投資以及強大的製造能力,確保北美繼續保持傾傾斜式旋翼機研發、生產和部署的領先地位。預計這些因素將在未來幾十年進一步鞏固該地區的市場領導地位。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 高速垂直起降戰術機動性的需求日益成長
- 擴展專用於作戰和防禦任務的應用
- 擴大在人道援助和拯救生命的航空運輸行動中的應用。
- 擴大商業航空貨運在離岸和偏遠地區的使用。
- 老舊直升機機隊的更新換代正在加速進行中。
- 產業潛在風險與挑戰
- 高昂的初始成本和生命週期營運成本
- 技術複雜性與運作安全風險
- 市場機遇
- 混合動力與永續推進技術的發展
- 自主和可選控制傾斜式旋翼機的擴展
- 促進因素
- 成長潛力分析
- 監理情勢
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 市場集中度分析
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的發展趨勢
第5章 市場估算與預測:依平台類型分類,2022-2035年
- 軍用傾斜式旋翼機
- 民用及商用傾斜式旋翼機
第6章 市場估算與預測:依轉子配置分類,2022-2035年
- 雙傾轉傾斜式旋翼
- 四傾斜式旋翼
第7章 市場估價與預測:依自動駕駛等級分類,2022-2035年
- 有人值守
- 可選車輛(OPV)
- 完全自主
第8章 市場估算與預測:依驅動技術分類,2022-2035年
- 常規型(渦軸/渦旋螺旋槳)
- 混合動力型(渦輪軸+電動馬達)
- 全電動
第9章 市場估計與預測:依應用領域分類,2022-2035年
- 軍事/國防
- 商業/私人
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 俄羅斯
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 全球主要公司
- Bell Textron Inc.
- Boeing(V-22 JV)
- Leonardo SpA
- Karem Aircraft
- Joby Aviation
- 該地區的主要公司
- 北美洲
- Archer Aviation Inc.
- 亞太地區
- Shenzhen UAT Air
- Aerofugia
- TCab Tech
- 北美洲
- 小眾玩家/顛覆者
- Zuri
The Global Tilt-Rotor Aircraft Market was valued at USD 1.8 billion in 2025 and is estimated to grow at a CAGR of 16.7% to reach USD 7.8 billion by 2035.
The global tilt-rotor aircraft market is experiencing strong growth as defense organizations continue investing in advanced aircraft capable of combining vertical takeoff and landing with the speed and range of fixed-wing platforms. Rising demand for enhanced tactical mobility, modernization of military aviation fleets, and expanding deployment across specialized mission profiles are creating favorable market opportunities. The industry is also benefiting from increasing interest in humanitarian aviation operations, commercial transportation across remote locations, and offshore logistics services. In addition, continuous technological advancements are accelerating the development of next-generation tilt-rotor aircraft featuring improved operational efficiency, greater reliability, and enhanced flight performance. Growing investments in aviation innovation and aircraft modernization programs are further strengthening market expansion. As manufacturers continue to develop advanced platforms capable of serving both defense and commercial applications, the tilt-rotor aircraft market is expected to transition toward a broader and more diversified demand landscape throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $1.8 Billion |
| Forecast Value | $7.8 Billion |
| CAGR | 16.7% |
The tilt-rotor aircraft industry continues to evolve beyond its traditional defense-focused structure as manufacturers expand development efforts across multiple application areas. Ongoing investments in civil certification programs, autonomous flight technologies, and advanced aircraft platforms are creating new opportunities for market growth. Modern digital fly-by-wire flight control systems have become the preferred design approach, providing greater precision and stability during complex flight operations while improving overall aircraft performance and operational safety. Continuous technological innovation is reshaping aircraft development strategies and strengthening the long-term outlook for the global tilt-rotor aircraft market.
The military tilt-rotor aircraft segment held a 91.5% share in 2025. Strong procurement activities by defense organizations continue to support the segment's leadership position as military operators prioritize aircraft capable of combining vertical lift capability with high-speed forward flight. The ability to operate efficiently across multiple mission environments while delivering superior operational flexibility continues to distinguish military tilt-rotor platforms from conventional aircraft. Long program durations, sustained procurement cycles, and continued fleet modernization initiatives are expected to maintain the segment's dominant position over the forecast period.
The twin tilt-rotor segment generated USD 1.7 billion in 2025. Its leadership reflects broad industry acceptance as the preferred engineering configuration across existing production programs and aircraft currently under development. Years of operational experience have demonstrated strong reliability, durability, and maintainability, supporting widespread confidence among procurement agencies and aviation authorities. Balanced flight performance, proven engineering maturity, well-established maintenance capabilities, and comprehensive pilot training infrastructure continue to reinforce the segment's leadership across both military and emerging commercial applications.
North America Tilt-Rotor Aircraft Market accounted for 86.4% share in 2025. Regional growth continues to be driven by sustained investments in advanced vertical lift aircraft and long-term defense modernization initiatives focused on improving aviation capabilities. Ongoing procurement programs, expanding engineering investments, and strong manufacturing capacity continue to position North America as the leading center for tilt-rotor aircraft development, production, and deployment. These factors are expected to reinforce the region's market leadership well into the coming decades.
Major companies operating in the global tilt-rotor aircraft market include Bell Textron Inc., Leonardo S.p.A., Boeing (Vertical Lift / Rotorcraft Systems), Shenzhen UAT Air, Joby Aviation Inc., Archer Aviation Inc., Aerofugia, TCab Tech, Karem Aircraft Inc., and Zuri. Companies operating in the tilt-rotor aircraft market are strengthening their market position through continuous investment in advanced aircraft technologies, research and development, and next-generation flight systems. Manufacturers are focusing on improving aircraft efficiency, operational reliability, flight safety, and mission flexibility to address evolving defense and commercial aviation requirements. Strategic collaborations with government agencies, defense organizations, aerospace suppliers, and technology partners are helping companies accelerate product development and secure long-term contracts. Businesses are also expanding engineering capabilities and investing in autonomous flight technologies, digital flight control systems, and advanced propulsion solutions to enhance competitive differentiation.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Platform type trends
- 2.2.2 Rotor configuration trends
- 2.2.3 Autonomy level trends
- 2.2.4 Propulsion technology trends
- 2.2.5 Application trends
- 2.2.6 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing requirement for high-speed vertical lift tactical mobility
- 3.2.1.2 Expansion of dedicated combat and defense mission applications
- 3.2.1.3 Rising adoption in humanitarian and life-saving air mobility operations
- 3.2.1.4 Increasing utilization in offshore and remote commercial aviation logistics
- 3.2.1.5 Accelerating replacement of legacy helicopter fleets
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High acquisition and lifecycle operating costs
- 3.2.2.2 Technical complexity and operational safety risks
- 3.2.3 Market opportunities
- 3.2.3.1 Development of hybrid-electric and sustainable propulsion technologies
- 3.2.3.2 Expansion of autonomous and optionally piloted tilt-rotor platforms
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Platform Type, 2022 - 2035 (USD Million & Units)
- 5.1 Key trends
- 5.2 Military tilt-rotor aircraft
- 5.3 Civil/Commercial tilt-rotor aircraft
Chapter 6 Market Estimates and Forecast, By Rotor Configuration, 2022 - 2035 (USD Million & Units)
- 6.1 Key trends
- 6.2 Twin tilt-rotor
- 6.3 Quad tilt-rotor
Chapter 7 Market Estimates and Forecast, By Autonomy Level, 2022 - 2035 (USD Million & Units)
- 7.1 Key trends
- 7.2 Manned
- 7.3 Optionally piloted (OPV)
- 7.4 Fully autonomous
Chapter 8 Market Estimates and Forecast, By Propulsion Technology, 2022 - 2035 (USD Million & Units)
- 8.1 Key trends
- 8.2 Conventional (turboshaft/turboprop)
- 8.3 Hybrid-electric (turboshaft + electric motor)
- 8.4 All-electric
Chapter 9 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Million & Units)
- 9.1 Key trends
- 9.2 Military and Defense
- 9.3 Commercial and Civil
Chapter 10 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million & Units)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Spain
- 10.3.5 Italy
- 10.3.6 Russia
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 Middle East and Africa
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Key Players
- 11.1.1 Bell Textron Inc.
- 11.1.2 Boeing (V-22 JV)
- 11.1.3 Leonardo S.p.A.
- 11.1.4 Karem Aircraft
- 11.1.5 Joby Aviation
- 11.2 Regional key players
- 11.2.1 North America
- 11.2.1.1 Archer Aviation Inc.
- 11.2.2 Asia Pacific
- 11.2.2.1 Shenzhen UAT Air
- 11.2.2.2 Aerofugia
- 11.2.2.3 TCab Tech
- 11.2.1 North America
- 11.3 Niche Players/Disruptors
- 11.3.1 Zuri


