


 |
市場調查報告書
商品編碼
2083047
汽車防盜器市場機會、成長要素、產業趨勢分析及2026-2035年預測Automotive Immobilizer Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

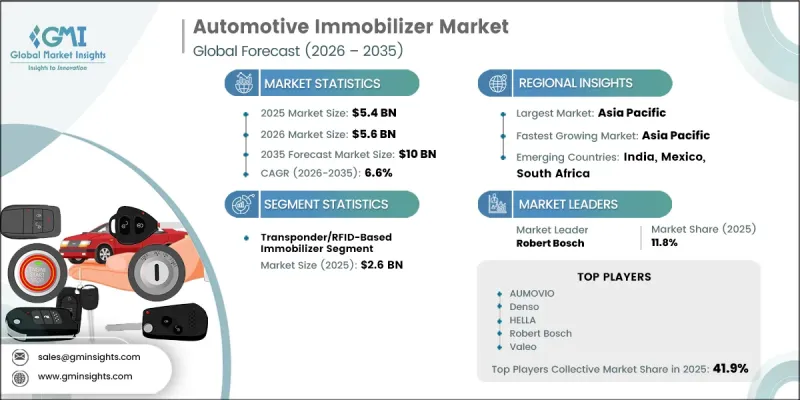
全球汽車防盜器市場預計到 2025 年將價值 54 億美元,預計到 2035 年將以 6.6% 的複合年成長率成長至 100 億美元。
人們對車輛安全和防盜的日益關注,推動了原廠配套市場(OEM)和售後市場對先進防盜技術的需求持續成長。日益嚴格的車輛安全法規,以及消費者對防盜技術的認知不斷提高,為全球汽車防盜市場創造了有利的成長機會。該產業正經歷從傳統安全解決方案轉型為更智慧、更強大的車輛保護系統的過程,這些系統具有更強大的安全功能和更先進的功能。聯網汽車技術的不斷進步,促使製造商整合基於軟體的安全功能,從而實現遠端系統管理和未來的系統升級。這些技術進步正在重塑市場的整體競爭格局,並提升下一代防盜解決方案的價值提案。同時,多個地區不斷完善的法律規範正在加速原廠安裝車輛安全系統的普及,進一步推動了市場的長期擴張。隨著汽車製造商持續優先考慮整合式電子安全技術,預計汽車防盜市場將在預測期內保持穩定成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 54億美元 |
| 預計金額 | 100億美元 |
| 複合年成長率 | 6.6% |
汽車防盜系統與聯網汽車平台的整合正成為影響市場發展的最重要趨勢之一。製造商日益關注支援遠端功能和未來空中下載 (OTA) 軟體升級的軟體主導安全系統,這推動了車輛保護技術在產品生命週期內的持續演進。這項轉變不僅提升了對技術先進的電子安全解決方案的需求,也促進了多個技術領域產品價值的提升,並重塑了供應商之間的競爭格局。此外,多個國家的汽車保險政策正逐步從獎勵性安裝轉向強制安裝,這為汽車防盜系統製造商創造了更多機會。
預計到2025年,基於應答器/RFID的防盜系統市場規模將達26億美元,市佔率高達48.7%。這一主導地位反映了其作為全球汽車生產標準車輛安全技術的廣泛認可。長期的產業應用、完善的服務體系、經濟的更換成本以及廣泛的監管認可,共同促成了基於應答器和RFID的防盜系統持續佔據主導地位。其久經考驗的可靠性和成本效益,也持續支撐著全球汽車產業的強勁需求。
預計到2025年,OEM銷售管道將佔據顯著的市場佔有率,這主要得益於日益嚴格的監管要求以及防盜系統作為標準車輛安全設備的普及。汽車製造商與零件供應商之間的長期供應協議持續影響該領域的競爭格局,供應商則受益於已建立的技術合作關係和平台整合能力。隨著汽車製造商在車輛開發中越來越重視整合電子安全技術,汽車製造商與零件供應商之間的緊密合作仍然是支撐OEM通路持續成長的關鍵因素。
預計到2025年,亞太地區汽車防盜系統市場規模將達21億美元,市佔率將達38.1%。國內汽車產量的持續成長、監管合規要求的不斷提高以及龐大的現有車輛保有量,將繼續支撐整車製造商和售後市場對汽車防盜系統的需求。對汽車製造業的持續投資以及先進汽車安全技術的日益普及,預計將在預測期內進一步鞏固該地區的市場領先地位。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 新興市場汽車竊盜案的增加正在推動對售後配件的需求。
- 已開發國家OEM生產的防盜器市場滲透率已接近飽和。
- 強制保險覆蓋範圍的擴大推動要素。
- 電動車防盜系統架構的差異以及售後市場營運商的新進機
- 產業潛在風險與挑戰
- OEM市場的成熟導致已開發國家新設備安裝量下降。
- 數位連接防盜系統中的網路安全漏洞
- 市場機遇
- 電動車(EV)的廣泛普及
- 對售後汽車安全解決方案的需求不斷成長
- 擴大人工智慧防盜技術的應用
- 促進因素
- 技術與創新展望
- 最新科技趨勢
- 基於RFID的防盜器
- 應答器鑰匙系統
- ECU 鎖定
- 新興技術
- 基於智慧型手機的數位鑰匙
- 使用生物識別的車輛認證
- 人工智慧驅動的車輛安全系統
- 最新科技趨勢
- 成長潛力分析
- 價格分析
- 對過去價格趨勢的分析
- 依球員類型分類的定價策略(高級球員、超值球員、成本加成球員)
- 監理情勢
- 北美洲
- 美國 - NHTSA(國家公路交通安全管理局)
- 加拿大 - 加拿大創新、科學與經濟發展部 (ISED)
- 歐洲
- 歐盟委員會(EU-EC)
- 德國 - KBA (Kraftfahrt-Bundesamt)
- 亞太地區
- 中國工信部
- 日本國土交通省
- 印度 - BIS(印度標準局/運輸部)
- LATAM
- 巴西 - CONTRAN(國家交通委員會)
- 巴西 - DENATRAN/SENATRAN
- 中東和非洲
- GCC-GSO(海灣合作理事會標準組織)
- 阿拉伯聯合大公國標準化與計量局 (UAE-ESMA)
- 北美洲
- 波特的分析
- PESTLE分析
- 貿易數據分析
- 進出口量及進口額趨勢
- 主要貿易路線及關稅的影響
- 生產能力和生產情況
- 設備產能:按地區和主要生產商分類
- 運轉率和擴張計劃
- 成本細分分析
- 專利分析
- 竊盜趨勢和車輛安全威脅分析
- 案例研究
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 預測假設和情境分析
- 基本案例:驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境:宏觀經濟與產業的順風
- 悲觀情景:宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
- 按公司規模進行基準測試
- 排名分類標準與遴選標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
第5章 市場估計與預測:依技術分類,2022-2035年
- 應答器/RFID防盜器
- 被動式應答器系統
- 主動應答器系統
- 滾動碼防盜器
- 固定代碼系統
- 動態滾動弦系統
- GPS/遠端資訊處理整合式防盜器
- 獨立式GPS防盜器
- 車隊遠端資訊處理整合防盜器
- OBD連接埠類型防盜器
- 生物識別固定器
- 指紋認證
- 臉部認證/語音識別
- 其他
第6章 市場估算與預測:依銷售管道分類,2022-2035年
- OEM
- 售後市場
- 新車售後市場
- 二手車售後市場
第7章 市場估價與預測:依車輛類型分類,2022-2035年
- 搭乘用車
- 掀背車
- 轎車
- SUV
- 商用車輛
- 輕型商用車(LCV)
- 中型商用車(MCV)
- 重型商用車(HCV)
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 瑞典
- 波蘭
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 泰國
- 越南
- 印尼
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 智利
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第9章:公司簡介
- 世界公司
- AUMOVIO
- Robert Bosch
- Denso
- Valeo
- Hella
- Lear
- ZF Friedrichshafen
- Alps Alpine
- Tokai Rika
- Aisin
- Mitsubishi Electric
- Marquardt
- 當地公司
- Asahi Denso
- Scorpion Automotive
- Pandora Security
- Dynamco
- Ravelco
- 新興企業
- Teltonika Telematics
- Synaptics
- Goodix Technology
The Global Automotive Immobilizer Market was valued at USD 5.4 billion in 2025 and is estimated to grow at a CAGR of 6.6% to reach USD 10 billion by 2035.
Rising concerns regarding vehicle security and theft prevention continue to accelerate demand for advanced immobilizer technologies across both original equipment manufacturers (OEMs) and the aftermarket. Increasing regulatory emphasis on vehicle safety, coupled with growing consumer awareness of anti-theft technologies, is creating favorable growth opportunities for the global automotive immobilizer market. The industry is also witnessing a gradual transition from conventional security solutions toward more intelligent vehicle protection systems that deliver stronger security capabilities and enhanced functionality. Continuous advancements in connected vehicle technologies are encouraging manufacturers to integrate software-enabled security features capable of supporting remote management and future system upgrades. These technological developments are reshaping competitive dynamics across the market while increasing the value proposition of next-generation immobilizer solutions. At the same time, evolving regulatory frameworks across several regions are encouraging wider adoption of factory-installed vehicle security systems, further supporting long-term market expansion. As automotive manufacturers continue to prioritize integrated electronic security technologies, the automotive immobilizer market is expected to maintain steady growth throughout the forecast period.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $5.4 Billion |
| Forecast Value | $10 Billion |
| CAGR | 6.6% |
The integration of automotive immobilizers with connected vehicle platforms is becoming one of the most significant trends influencing market development. Manufacturers are increasingly focusing on software-driven security systems that support remote functionality and future over-the-air software upgrades, allowing vehicle protection technologies to evolve throughout the product lifecycle. This transition is reshaping supplier competition by increasing demand for technologically advanced electronic security solutions while supporting higher product values across multiple technology categories. In addition, regulatory policies governing vehicle insurance in several countries are progressively moving from incentive-based adoption toward mandatory installation requirements for insurance eligibility, creating additional opportunities for automotive immobilizer manufacturers.
The transponder/RFID-based immobilizer segment generated USD 2.6 billion, holding 48.7% share in 2025. Its leading position reflects widespread acceptance as a standard vehicle security technology across global automotive production. Long-term industry adoption, extensive service infrastructure, affordable replacement costs, and broad regulatory acceptance have contributed to the continued dominance of transponder and RFID-based immobilizer systems. Their proven reliability and cost efficiency continue to support strong demand across the global automotive sector.
The OEM sales channel segment captured a significant share in 2025, supported by expanding regulatory requirements and the increasing integration of immobilizer systems as standard vehicle security equipment. Long-term supply agreements between automotive manufacturers and component suppliers continue to shape competitive dynamics within this segment, with suppliers benefiting from established engineering relationships and platform integration capabilities. Strong collaboration between vehicle manufacturers and component suppliers remains a key factor supporting continued growth within the OEM channel, as automakers increasingly prioritize integrated electronic security technologies during vehicle development.
Asia Pacific Automotive Immobilizer Market reached USD 2.1 billion, accounting for 38.1% share in 2025. Continued expansion of domestic vehicle production, regulatory compliance requirements, and a large existing vehicle fleet continue to support both OEM and aftermarket demand for automotive immobilizer systems. Sustained investments in vehicle manufacturing and the growing adoption of advanced automotive security technologies are expected to reinforce the region's market leadership over the forecast period.
Major companies operating in the global automotive immobilizer market include AUMOVIO, Robert Bosch, Denso, Valeo, Hella, Lear, ZF Friedrichshafen, Alps Alpine, Tokai Rika, Aisin, Mitsubishi Electric, and Marquardt. Companies operating in the automotive immobilizer market are strengthening their market position through continuous investment in advanced vehicle security technologies and product innovation. Manufacturers are focusing on developing intelligent immobilizer systems that integrate with connected vehicle platforms and support software-based upgrades to improve long-term functionality. Strategic collaborations with automotive OEMs are helping suppliers secure long-term production contracts while expanding their presence across new vehicle platforms. Businesses are also investing in research and development to enhance cybersecurity, reliability, and compatibility with evolving automotive electronics. Geographic expansion, manufacturing capacity enhancements, and stronger distribution networks are supporting broader market penetration.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Technology
- 2.2.3 Sales Channel
- 2.2.4 Vehicle
- 2.3 TAM analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising vehicle theft rates in emerging markets driving aftermarket retrofit demand
- 3.2.1.2 OEM immobilizer penetration nearing saturation in developed markets
- 3.2.1.3 Insurance mandate expansion as structural aftermarket demand driver
- 3.2.1.4 EV immobilizer architecture differences and new entry points for aftermarket players
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 OEM market maturity compressing new installation volumes in developed markets
- 3.2.2.2 Cybersecurity vulnerabilities in digitally connected immobilizers
- 3.2.3 Market opportunities
- 3.2.3.1 Growing Adoption of Electric Vehicles (EVs)
- 3.2.3.2 Rising Demand for Aftermarket Vehicle Security Solutions
- 3.2.3.3 Increasing Deployment of AI-Enabled Anti-Theft Technologies
- 3.2.1 Growth drivers
- 3.3 Technology and innovation landscape
- 3.3.1 Current technological trends
- 3.3.1.1 RFID-Based Immobilizers
- 3.3.1.2 Transponder Key Systems
- 3.3.1.3 ECU Immobilization
- 3.3.2 Emerging technologies
- 3.3.2.1 Smartphone-Based Digital Keys
- 3.3.2.2 Biometric Vehicle Authentication
- 3.3.2.3 AI-Based Vehicle Security Systems
- 3.3.1 Current technological trends
- 3.4 Growth potential analysis
- 3.5 Pricing Analysis (Driven by Primary Research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Regulatory landscape
- 3.6.1 North America
- 3.6.1.1 US - NHTSA (National Highway Traffic Safety Administration)
- 3.6.1.2 Canada - ISED (Innovation, Science and Economic Development Canada)
- 3.6.2 Europe
- 3.6.2.1 EU - EC (European Commission)
- 3.6.2.2 Germany - KBA (Kraftfahrt-Bundesamt)
- 3.6.3 Asia Pacific
- 3.6.3.1 China - MIIT (Ministry of Industry and Information Technology)
- 3.6.3.2 Japan - MLIT (Ministry of Land, Infrastructure, Transport and Tourism)
- 3.6.3.3 India - BIS (Bureau of Indian Standards / Department of Transport)
- 3.6.4 LATAM
- 3.6.4.1 Brazil - CONTRAN (Conselho Nacional de Transito)
- 3.6.4.2 Brazil - DENATRAN / SENATRAN
- 3.6.5 MEA
- 3.6.5.1 GCC - GSO (GCC Standardization Organization)
- 3.6.5.2 UAE - ESMA (Emirates Authority for Standardization and Metrology)
- 3.6.1 North America
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Trade Data Analysis (Driven by Paid Database)
- 3.9.1 Import/Export Volume & Value Trends
- 3.9.2 Key Trade Corridors & Tariff Impact
- 3.10 Capacity & Production Landscape (Driven by Primary Research)
- 3.10.1 Installed Capacity by Region & Key Producer
- 3.10.2 Capacity Utilization Rates & Expansion Pipelines
- 3.11 Cost breakdown analysis
- 3.12 Patent analysis (Driven by Primary Research)
- 3.13 Theft Trends and Vehicle Security Threat Analysis
- 3.14 Case studies
- 3.15 Impact of AI & generative AI on the market
- 3.15.1 AI-driven disruption of existing business models
- 3.15.2 GenAI use cases & adoption roadmap by segment
- 3.15.3 Risks, limitations & regulatory considerations
- 3.16 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.16.1 Base Case- Key Macro & Industry Variables Driving CAGR
- 3.16.2 Optimistic Scenarios- Favorable macro and industry tailwinds
- 3.16.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates and Forecast, By Technology, 2022 - 2035 ($ Mn, Units)
- 5.1 Key trends
- 5.2 Transponder / RFID-Based Immobilizer
- 5.2.1 Passive Transponder Systems
- 5.2.2 Active Transponder Systems
- 5.3 Rolling Code Immobilizer
- 5.3.1 Fixed Code Systems
- 5.3.2 Dynamic Rolling Code Systems
- 5.4 GPS / Telematics-Integrated Immobilizer
- 5.4.1 Standalone GPS Immobilizer
- 5.4.2 Fleet Telematics-Integrated Immobilizer
- 5.5 OBD-Port Based Immobilizer
- 5.6 Biometric Immobilizer
- 5.6.1 Fingerprint Recognition
- 5.6.2 Facial / Voice Recognition
- 5.7 Others
Chapter 6 Market Estimates and Forecast, By Sales Channel, 2022 - 2035 ($ Mn, Units)
- 6.1 Key trends
- 6.2 OEM
- 6.3 Aftermarket
- 6.3.1 New Vehicle Aftermarket
- 6.3.2 Used Vehicle Aftermarket
Chapter 7 Market Estimates and Forecast, By Vehicle, 2022 - 2035 ($ Mn, Units)
- 7.1 Key trends
- 7.2 Passenger Vehicle
- 7.2.1 Hatchback
- 7.2.2 Sedan
- 7.2.3 SUV
- 7.3 Commercial Vehicle
- 7.3.1 Light Commercial Vehicles (LCV)
- 7.3.2 Medium Commercial Vehicles (MCV)
- 7.3.3 Heavy Commercial Vehicles (HCV)
Chapter 8 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn, Units)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 US
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Italy
- 8.3.5 Spain
- 8.3.6 Netherlands
- 8.3.7 Sweden
- 8.3.8 Poland
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Thailand
- 8.4.7 Vietnam
- 8.4.8 Indonesia
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.5.4 Chile
- 8.6 MEA
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Global players
- 9.1.1 AUMOVIO
- 9.1.2 Robert Bosch
- 9.1.3 Denso
- 9.1.4 Valeo
- 9.1.5 Hella
- 9.1.6 Lear
- 9.1.7 ZF Friedrichshafen
- 9.1.8 Alps Alpine
- 9.1.9 Tokai Rika
- 9.1.10 Aisin
- 9.1.11 Mitsubishi Electric
- 9.1.12 Marquardt
- 9.2 Regional players
- 9.2.1 Asahi Denso
- 9.2.2 Scorpion Automotive
- 9.2.3 Pandora Security
- 9.2.4 Dynamco
- 9.2.5 Ravelco
- 9.3 Emerging players
- 9.3.1 Teltonika Telematics
- 9.3.2 Synaptics
- 9.3.3 Goodix Technology

 車輛安全系統市場-2026-2032年全球市場預測
 汽車安全系統市場分析及預測(至2035年):類型、產品、技術、組件、應用、最終用戶、功能、安裝類型、解決方案、模式
 汽車安全系統市場:依類型、車輛類型、銷售管道、技術、國家及地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測
 汽車安全市場:依車輛類型、銷售管道、產品類型及地區分類汽車安全市場:按類型、應用程式和地區分類
 2026年全球車輛安全系統市場報告乘用車門禁控制市場:依技術、車輛類型及銷售管道分類-2026-2032年全球市場預測摩托車防盜器市場:依技術、引擎排氣量和最終用戶分類-2026-2032年全球預測
 全球汽車安全系統市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 車輛安全系統市場 - 全球產業規模、佔有率、趨勢、機會及預測(按車輛類型、產品類型、技術、地區和競爭格局分類,2021-2031年)