


 |
市場調查報告書
商品編碼
2071254
航空航太氧氣系統市場機會、成長要素、產業趨勢分析及2026-2035年預測。Aircraft Oxygen Systems Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球飛機氧氣系統市場預計到 2025 年將價值 39 億美元,預計到 2035 年將以 6.5% 的複合年成長率成長至 73 億美元。
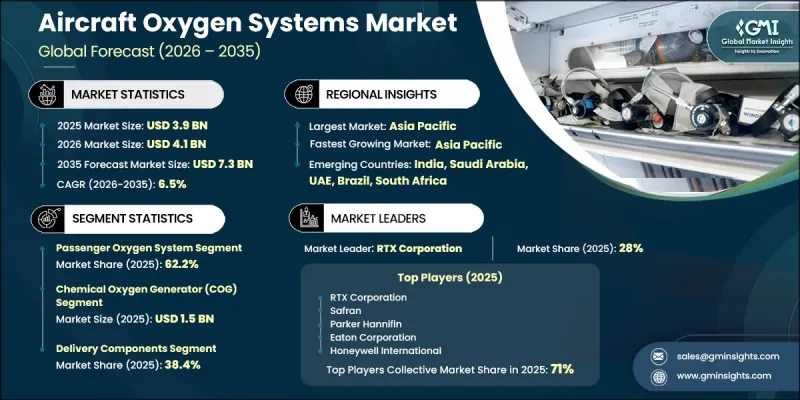
飛機氧氣系統市場的成長主要受全球機隊持續擴張的推動,而這又源自於航空旅行需求的不斷成長以及對更高飛行安全標準的持續追求。隨著民用和軍用航空活動的不斷擴展,航空公司和飛機運營商正加大對先進安全設備的投入,以確保乘客和機組人員在飛行過程中的安全。遵守相關法規仍然是市場成長的主要驅動力,因為航空當局強制要求飛機配備符合嚴格運作和安全要求的可靠氧氣供應系統。此外,長途航班和高空飛行的增加也促進了市場的發展。這些飛行需要可靠的氧氣供應解決方案來維持飛機的安全性能。同時,氧氣系統的定期更換週期以及氧氣產生和供應技術的不斷進步,也為製造商創造了新的商機。這些因素,加上對下一代飛機平台和航空基礎設施投資的不斷增加,預計將推動全球飛機氧氣系統市場整體的持續長期成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 39億美元 |
| 預測金額 | 73億美元 |
| 複合年成長率 | 6.5% |
在全球客運量穩定成長的推動下,飛機氧氣系統市場持續保持強勁勢頭。這促進了全球飛機產量的成長和機隊規模的擴張。隨著航空公司努力滿足日益成長的旅遊需求,先進的機載安全技術的重要性也日益凸顯。氧氣系統仍然是飛機安全基礎設施的關鍵組成部分,確保符合航空法規並保障營運準備就緒。此外,嚴格的業界標準也持續推動各類飛機對尖端氧氣系統的需求。法律規範要求在特定飛行條件下運行的飛機必須保持可靠的輔助氧氣供給能力,這進一步鞏固了市場的長期需求。
預計到2035年,機組氧氣系統市場將以5.4%的複合年成長率成長。該市場的成長主要得益於對機組人員安全的日益重視以及現代航空運營中先進氧氣輸送技術的廣泛應用。這些系統旨在提供卓越的可靠性、更優異的性能以及與先進駕駛座技術的無縫整合。隨著飛機製造商不斷開發更複雜的航空平台,對高性能機組氧氣系統的需求預計將穩定成長,從而推動該市場在未來幾年持續擴張。
預計到2025年,化學氧氣發生器市場規模將達到15億美元。該市場強勁的成長勢頭歸功於其在飛機客艙的廣泛應用,以及無需依賴複雜的儲存基礎設施即可提供可靠的緊急氧氣供給能力。這些系統因其結構緊湊、維護簡便以及與飛機設計的高效整合而廣受認可。其卓越的運作優勢持續推動其在大批量飛機項目中廣泛應用,並顯著提升了整體市場收入。
預計到2025年,北美將佔據飛機氧氣系統市場33.9%的佔有率。這一區域成長主要得益於大量的商用和軍用飛機部署,以及廣泛的維護、修理和大修(MRO)活動。持續的飛機現代化改造和對航空安全技術的持續投資,為市場擴張創造了有利條件。主要飛機製造商和系統供應商的存在,進一步增強了該地區對先進氧氣解決方案的需求,使北美能夠保持主導地位。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 全球民用航空客運量成長
- 嚴格的航空和安全法規及認證標準
- 擴大高空和超遠程飛機作戰
- 加強氧氣系統的維護與生命週期管理
- 化學氧氣系統的輕量化與技術進步
- 產業潛在風險與挑戰
- 身份驗證和合規性的複雜性
- 飛機整合中的重量和空間限制
- 市場機遇
- 引進下一代飛機計畫並實現機隊現代化
- 加大投資,提升飛機客艙安全性和乘客體驗。
- 促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要公司的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- R&D
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 擴張和投資策略
- 數位轉型計劃
- 新興企業競爭公司和新創企業的發展趨勢
第5章 市場估計與預測:依系統類型分類,2022-2035年
- 乘客氧氣系統
- 船員氧氣系統
第6章 市場估計與預測:依技術分類,2022-2035年
- 化學制氧機(COG)
- 氣態氧系統(GOX)
- 液態氧系統(LOX)
- 機載制氧系統(OBOGS)
第7章 市場估計與預測:依組件分類,2022-2035年
- 儲存組件
- 供應組件
- 控制和監控組件
- 安裝組件
第8章 市場估算與預測:依飛機類型分類,2022-2035年
- 民航機
- 軍用機
- 公務機和通用飛機
- 旋翼飛機
第9章 市場估價與預測:依最終用戶分類,2022-2035年
- 商業
- 軍事商業
- 商務航空公司營運商
- 私人休閒娛樂企業
- 政府/特種任務人員
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 俄羅斯
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第11章:公司簡介
- 全球主要公司
- RTX Corporation
- Safran
- Parker Hannifin
- Eaton Corporation
- Honeywell International
- 該地區的主要公司
- 北美洲
- Worthington Enterprises
- Gentex Corporation
- Telephonics Corporation
- Precise Flight
- Ventura Aerospace
- 亞太地區
- CIRCOR International
- 歐洲
- Air Liquide
- Drager
- Autoflug GmbH
- Survitec Group
- Thales
- Diehl Aviation
- Bucher Group
- 北美洲
- 小眾玩家/顛覆者
- Aerox Aviation Oxygen Systems
The Global Aircraft Oxygen Systems Market was valued at USD 3.9 billion in 2025 and is estimated to grow at a CAGR of 6.5% to reach USD 7.3 billion by 2035.
Growth in the aircraft oxygen systems market is driven by the continuous expansion of global aircraft fleets resulting from increasing air travel demand and the ongoing need to enhance onboard safety standards. As commercial and military aviation activities continue to grow, airlines and aircraft operators are investing in advanced safety equipment designed to ensure passenger and crew protection during flight operations. Regulatory compliance remains a major factor supporting market growth, as aviation authorities require aircraft to be equipped with dependable oxygen supply systems that meet stringent operational and safety requirements. The market is also benefiting from the increasing prevalence of long-duration and high-altitude flight operations, which require reliable oxygen delivery solutions to support safe aircraft performance. Furthermore, recurring replacement cycles for oxygen systems, along with continuous technological advancements in oxygen generation and delivery technologies, are creating new opportunities for manufacturers. These factors, combined with growing investments in next-generation aircraft platforms and aviation infrastructure, are expected to sustain long-term growth across the global aircraft oxygen systems market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.9 Billion |
| Forecast Value | $7.3 Billion |
| CAGR | 6.5% |
The aircraft oxygen systems market continues to gain momentum due to the steady rise in global passenger traffic, which is contributing to increased aircraft production and fleet expansion worldwide. As aviation operators seek to accommodate growing travel demand, the importance of advanced onboard safety technologies has become increasingly significant. Oxygen systems remain a critical component of aircraft safety infrastructure, ensuring compliance with aviation regulations and supporting operational readiness. In addition, strict industry standards governing aircraft safety continue to reinforce demand for modern oxygen systems across various aircraft categories. Regulatory frameworks require aircraft operating under specific flight conditions to maintain reliable supplementary oxygen capabilities, further strengthening long-term market demand.
The crew oxygen system segment is expected to register a CAGR of 5.4% throughout 2035. Segment growth is driven by increasing emphasis on flight crew safety and the growing utilization of advanced oxygen delivery technologies in modern aviation operations. These systems are designed to provide superior reliability, enhanced performance, and seamless integration with advanced cockpit technologies. As aircraft manufacturers continue developing more sophisticated aviation platforms, demand for high-performance crew oxygen systems is expected to increase steadily, supporting continued segment expansion over the coming years.
The chemical oxygen generator segment generated USD 1.5 billion in 2025. Strong segment performance is attributed to its broad adoption across aircraft cabins and its ability to deliver dependable emergency oxygen capabilities without relying on complex storage infrastructure. These systems are widely recognized for their compact configuration, simplified maintenance requirements, and efficient integration into aircraft designs. Their operational advantages continue to support widespread deployment across high-volume aircraft production programs, contributing significantly to overall market revenue.
North America Aircraft Oxygen Systems Market accounted for 33.9% share in 2025. The region's market growth is supported by a substantial installed base of commercial and military aircraft, along with extensive maintenance, repair, and overhaul activities. Continuous fleet modernization efforts and ongoing investments in aviation safety technologies are creating favorable conditions for market expansion. The presence of leading aircraft manufacturers and system suppliers further strengthens regional demand for advanced oxygen solutions, enabling North America to maintain a prominent position within the global aircraft oxygen systems industry.
Major companies operating in the Global Aircraft Oxygen Systems Market include RTX Corporation, Safran, Eaton Corporation, Honeywell International, Parker Hannifin, Worthington Enterprises, Gentex Corporation, Air Liquide, Telephonics Corporation, Precise Flight, Ventura Aerospace, Aerox Aviation Oxygen Systems, Mountain High Equipment & Supply, Luxfer Holdings, Drager, Autoflug GmbH, Survitec Group, Thales, CIRCOR International, Diehl Aviation, Bucher Group, and Northrop Grumman. Companies participating in the aircraft oxygen systems market are adopting a variety of strategic initiatives to strengthen their market position and expand their competitive advantage. Product innovation remains a key priority, with manufacturers investing in advanced oxygen generation technologies, lightweight system designs, and enhanced safety features that improve overall aircraft performance. Strategic partnerships with aircraft manufacturers, defense organizations, and aviation service providers are helping companies secure long-term contracts and strengthen customer relationships. Businesses are also increasing research and development investments to improve system reliability, operational efficiency, and regulatory compliance.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 System type trends
- 2.2.2 Technology trends
- 2.2.3 Component trends
- 2.2.4 Aircraft type trends
- 2.2.5 End-User trends
- 2.2.6 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Growth in global commercial air passenger traffic
- 3.2.1.2 Stringent aviation and safety regulations and certification standards
- 3.2.1.3 Expansion of high-altitude and ultra-long-range aircraft operations
- 3.2.1.4 Increasing replacement and lifecycle management of oxygen systems
- 3.2.1.5 Technological advancements in lightweight and chemical oxygen systems
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High certification and compliance complexities
- 3.2.2.2 Weight and space constraints in aircraft integration
- 3.2.3 Market opportunities
- 3.2.3.1 Adoption of next-generation aircraft programs and fleet modernization
- 3.2.3.2 Increasing investments in aircraft cabin safety and passenger experience enhancement
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By System Type, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Passenger oxygen system
- 5.3 Crew oxygen system
Chapter 6 Market Estimates and Forecast, By Technology, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Chemical oxygen generator (COG)
- 6.3 Gaseous oxygen system (GOX)
- 6.4 Liquid oxygen system (LOX)
- 6.5 Onboard oxygen generation systems (OBOGS)
Chapter 7 Market Estimates and Forecast, By Component, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Storage components
- 7.3 Delivery components
- 7.4 Control & monitoring components
- 7.5 Deployment assemblies
Chapter 8 Market Estimates and Forecast, By Aircraft Type, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 Commercial aircraft
- 8.3 Military aircraft
- 8.4 Business & general aviation aircraft
- 8.5 Rotary-wing aircraft
Chapter 9 Market Estimates and Forecast, By End-User, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 Commercial operators
- 9.3 Military operators
- 9.4 Business aviation operators
- 9.5 Private/Recreational operators
- 9.6 Government & special mission operators
Chapter 10 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Spain
- 10.3.5 Italy
- 10.3.6 Russia
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 Middle East and Africa
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Key Players
- 11.1.1 RTX Corporation
- 11.1.2 Safran
- 11.1.3 Parker Hannifin
- 11.1.4 Eaton Corporation
- 11.1.5 Honeywell International
- 11.2 Regional key players
- 11.2.1 North America
- 11.2.1.1 Worthington Enterprises
- 11.2.1.2 Gentex Corporation
- 11.2.1.3 Telephonics Corporation
- 11.2.1.4 Precise Flight
- 11.2.1.5 Ventura Aerospace
- 11.2.2 Asia Pacific
- 11.2.2.1 CIRCOR International
- 11.2.3 Europe
- 11.2.3.1 Air Liquide
- 11.2.3.2 Drager
- 11.2.3.3 Autoflug GmbH
- 11.2.3.4 Survitec Group
- 11.2.3.5 Thales
- 11.2.3.6 Diehl Aviation
- 11.2.3.7 Bucher Group
- 11.2.1 North America
- 11.3 Niche Players/Disruptors
- 11.3.1 Aerox Aviation Oxygen Systems


