


 |
市場調查報告書
商品編碼
2061488
獸醫院市場機會、成長要素、產業趨勢分析及2026-2035年預測。Veterinary Hospital Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025年全球獸醫院市場價值為678億美元,預計2035年將以7.1%的複合年成長率成長至1,328億美元。
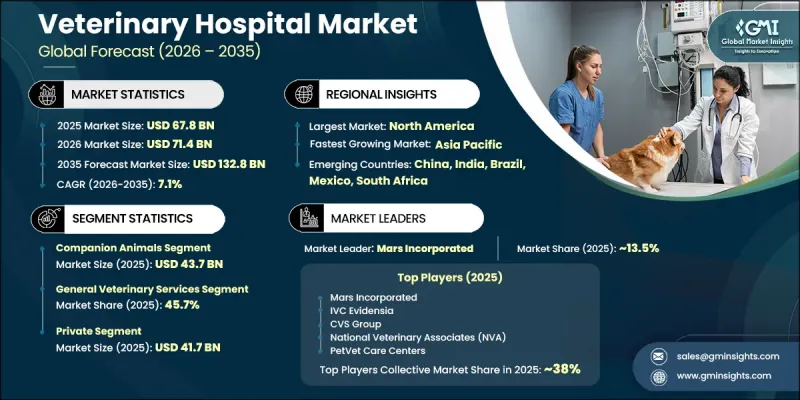
由於全球動物數量不斷成長、伴侶動物數量持續增加以及動物醫療保健服務支出不斷成長,市場正穩步擴張。獸醫院在為寵物、牲畜和其他動物提供全面的醫療保健方面發揮著至關重要的作用,其服務涵蓋廣泛的診斷、預防和治療。這些機構配備齊全,能夠提供先進的醫療支持,包括外科手術、常規檢查、疫苗接種計劃和專業的獸醫護理。寵物飼主與其寵物之間日益增強的情感紐帶顯著影響著對高品質醫療保健服務和先進治療方案的需求。此外,獸醫學的不斷進步、創新醫療設備的普及以及寵物醫療保健服務可近性的提高也促進了市場的整體成長。人們對動物福利和預防醫學的日益重視進一步增強了全球對獸醫院的需求。診斷和治療程序以及動物醫療保健管理系統的技術進步也使該行業受益匪淺,這些進步有助於提高獸醫機構的治療效果和運作效率。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 678億美元 |
| 預測金額 | 1328億美元 |
| 複合年成長率 | 7.1% |
預計到2025年,伴侶動物市場規模將達437億美元。這個市場成長的主要驅動力是越來越多的家庭飼養伴侶動物,並將寵物視為家庭成員。人們對動物健康和福祉的日益關注,以及對預防性護理和專業醫療保健服務需求的成長,持續推動市場擴張。隨著寵物飼主醫療保健支出的增加,以及全球對高品質寵物治療和長期保健需求的不斷成長,伴侶動物仍然是獸醫醫院關注的重點領域。
預計到2025年,一般獸醫服務市佔率將達到45.7%。寵物飼養率的上升、人們對動物保健日益重視以及獸醫實踐的不斷改進,都推動了對普通獸醫服務的強勁需求。動物健康問題的日益增加也促使人們對常規獸醫檢查和預防性保健方案的需求不斷成長。獸醫醫院正在拓展其普通服務範圍,包括常規健康檢查、疫苗接種、預防性治療和持續性健康護理,這進一步促進了市場成長。
預計到2025年,北美獸醫院市佔率將達到39.7%。該地區憑藉其高寵物擁有率、在伴侶動物醫療保健方面的大量支出以及完善的獸醫基礎設施,繼續引領著產業發展。先進的診斷技術、專業的治療服務以及強大的寵物保險網路,全部區域獸醫服務的擴張提供了支持。此外,多地點獸醫醫院網路的成長以及對動物醫療保健服務投資的增加,也進一步推動了北美市場的發展。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 影響產業的因素
- 促進因素
- 動物數量增加和寵物飼養率上升
- 獸醫學進展
- 動物醫院合併
- 動物慢性疾病和感染疾病增加
- 產業潛在風險與挑戰
- 高級獸醫治療高成本
- 熟練獸醫專業人員短缺
- 市場機遇
- 寵物保險的普及
- 對專業和轉診獸醫服務的需求日益成長
- 進入新興市場
- 促進因素
- 成長潛力分析
- 監理情勢
- 各國寵物數量
- 人口趨勢對寵物飼養的影響
- 未來市場趨勢
- 獸醫保健服務醫療成本分析
- 人工智慧和生成式人工智慧對市場的影響
- 波特的分析
- PESTLE分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 北美洲
- 歐洲
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估計與預測:依動物類型分類,2022-2035年
- 伴侶動物
- 狗
- 貓
- 馬
- 其他伴侶動物
- 家畜
- 牛
- 豬
- 家禽
- 其他牲畜
- 珍稀動物和野生動物
第6章 市場估計與預測:依服務業分類,2022-2035年
- 一般獸醫服務
- 診斷服務
- 外科服務
- 其他服務
第7章 市場估計與預測:依所有權類型分類,2022-2035年
- 民眾
- 私人的
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第9章:公司簡介
- All Pets Veterinary Hospital
- AniCura
- Beijing Xintiandi International Animal Hospital
- Belltowne Veterinary Center
- CVS Group
- Fishers Veterinary Hospital
- Greencross Vets
- Innovative Petcare
- IVC Evidensia
- MaxPetZ
- Mars Incorporated
- Medivet
- National Veterinary Associates(NVA)
- PetVet Care Centers
- SASH Vets
- The Animal Medical Center
- VetPartners
The Global Veterinary Hospital Market was valued at USD 67.8 billion in 2025 and is estimated to grow at a CAGR of 7.1% to reach USD 132.8 billion by 2035.
The market is expanding steadily due to the rising global animal population, increasing adoption of companion animals, and growing spending on animal healthcare services. Veterinary hospitals play a critical role in delivering comprehensive medical care for pets, livestock, and other animals through a broad range of diagnostic, preventive, and treatment services. These facilities are equipped to provide advanced medical support, including surgical procedures, routine examinations, immunization programs, and specialized veterinary care. The increasing emotional attachment between pet owners and animals is significantly influencing demand for high-quality healthcare services and advanced treatment solutions. In addition, continuous progress in veterinary medicine, availability of innovative medical devices, and wider access to pet healthcare services are contributing to overall market growth. Expanding awareness regarding animal welfare and preventive healthcare is further strengthening demand for veterinary hospitals worldwide. The industry is also benefiting from technological advancements in diagnostics, treatment procedures, and veterinary healthcare management systems, supporting improved treatment outcomes and operational efficiency across veterinary care facilities.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $67.8 Billion |
| Forecast Value | $132.8 Billion |
| CAGR | 7.1% |
The companion animals segment generated USD 43.7 billion in 2025. Growth within this segment is primarily driven by the increasing number of households adopting companion animals and treating pets as integral family members. Rising awareness regarding animal health and wellness, coupled with growing demand for preventive and specialized healthcare services, continues to support market expansion. Companion animals remain a major focus area for veterinary hospitals due to increasing healthcare spending by pet owners and rising demand for quality treatment and long-term medical care for pets across global markets.
The general veterinary services segment held a 45.7% share in 2025. Strong demand for general veterinary services is being driven by rising pet ownership rates, increasing focus on animal health management, and continuous improvements in veterinary medical practices. The growing occurrence of animal health conditions is also contributing to greater demand for routine veterinary consultations and preventive healthcare solutions. Veterinary hospitals are increasingly expanding their general service offerings to include regular health examinations, vaccinations, preventive treatments, and ongoing wellness care, supporting broader market growth.
North America Veterinary Hospital Market captured 39.7% share in 2025. The region continues to lead the industry due to high pet ownership levels, substantial expenditure on companion animal healthcare, and the presence of well-developed veterinary infrastructure. Strong availability of advanced diagnostic technologies, specialty treatment services, and pet healthcare coverage is supporting increased adoption of veterinary services throughout the region. In addition, the growing expansion of multi-location veterinary hospital networks and rising investments in animal healthcare services are further strengthening market development across North America.
Major companies operating in the Global Veterinary Hospital Market include All Pets Veterinary Hospital, AniCura, Beijing Xintiandi International Animal Hospital, Belltowne Veterinary Center, CVS Group, Fishers Veterinary Hospital, Greencross Vets, Innovative Petcare, IVC Evidensia, MaxPetZ, Mars Incorporated, Medivet, National Veterinary Associates (NVA), PetVet Care Centers, SASH Vets, The Animal Medical Center, and VetPartners. Companies operating in the veterinary hospital industry are adopting multiple strategic initiatives to strengthen their market presence and expand service capabilities. Leading organizations are investing in advanced diagnostic technologies, digital healthcare systems, and specialized treatment facilities to improve the quality of veterinary care and operational efficiency. Many market participants are also focusing on expanding multi-location hospital networks through mergers, acquisitions, and strategic partnerships to increase geographic reach and customer access. In addition, veterinary healthcare providers are emphasizing preventive care programs, wellness services, and personalized treatment solutions to enhance long-term client relationships. Investments in skilled veterinary professionals, telemedicine platforms, and modern healthcare infrastructure are further supporting business growth.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research approach
- 1.3 Quality commitments
- 1.3.1 GMI AI policy and data integrity commitment
- 1.3.1.1 Source consistency protocol
- 1.3.1 GMI AI policy and data integrity commitment
- 1.4 Research trail and confidence scoring
- 1.4.1 Research trail components
- 1.4.2 Scoring components
- 1.5 Data collection
- 1.5.1 Partial list of primary sources
- 1.6 Data mining sources
- 1.6.1 Paid sources
- 1.6.1.1 Sources, by region
- 1.6.1 Paid sources
- 1.7 Base estimates and calculations
- 1.7.1 Revenue share analysis
- 1.7.2 Base year calculation
- 1.8 Forecast model
- 1.9 Research transparency addendum
- 1.9.1 Source attribution framework
- 1.9.2 Quality assurance metrics
- 1.9.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional trends
- 2.2.2 Animal type trends
- 2.2.3 Services trends
- 2.2.4 Ownership trends
- 2.3 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Growing animal population and rising pet ownership
- 3.2.1.2 Advancements in veterinary medicine
- 3.2.1.3 Consolidation of animal hospitals
- 3.2.1.4 Growing prevalence of chronic and infectious diseases in animals
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High cost of advanced veterinary treatments
- 3.2.2.2 Shortage of skilled veterinary professionals
- 3.2.3 Market opportunities
- 3.2.3.1 Growth in pet insurance adoption
- 3.2.3.2 Increasing demand for specialized and referral veterinary services
- 3.2.3.3 Expansion in emerging markets
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Pet population, by country
- 3.6 Impact of demographics on pet ownership
- 3.7 Future market trends
- 3.8 Veterinary service healthcare cost analysis
- 3.9 Impact of AI and Gen AI on the market
- 3.10 Porter's analysis
- 3.11 PESTEL analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Merger and acquisition
- 4.6.2 Partnership and collaboration
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Animal Type, 2022 - 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Companion animals
- 5.2.1 Dogs
- 5.2.2 Cats
- 5.2.3 Horses
- 5.2.4 Other companion animals
- 5.3 Farm animals
- 5.3.1 Cattle
- 5.3.2 Swine
- 5.3.3 Poultry
- 5.3.4 Other farm animals
- 5.4 Exotic animals and wildlife
Chapter 6 Market Estimates and Forecast, By Services, 2022 - 2035 ($ Mn)
- 6.1 Key trends
- 6.2 General veterinary services
- 6.3 Diagnostic services
- 6.4 Surgical services
- 6.5 Other services
Chapter 7 Market Estimates and Forecast, By Ownership, 2022 - 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Public
- 7.3 Private
Chapter 8 Market Estimates and Forecast, By Region, 2022 - 2035 ($ Mn)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Italy
- 8.3.5 Spain
- 8.3.6 Netherlands
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 Japan
- 8.4.3 India
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 Middle East and Africa
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 All Pets Veterinary Hospital
- 9.2 AniCura
- 9.3 Beijing Xintiandi International Animal Hospital
- 9.4 Belltowne Veterinary Center
- 9.5 CVS Group
- 9.6 Fishers Veterinary Hospital
- 9.7 Greencross Vets
- 9.8 Innovative Petcare
- 9.9 IVC Evidensia
- 9.10 MaxPetZ
- 9.11 Mars Incorporated
- 9.12 Medivet
- 9.13 National Veterinary Associates (NVA)
- 9.14 PetVet Care Centers
- 9.15 SASH Vets
- 9.16 The Animal Medical Center
- 9.17 VetPartners


