


 |
市場調查報告書
商品編碼
2061400
2026 年至 2035 年止血帶系統的市場機會、成長要素、產業趨勢分析與預測。Tourniquet Systems Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球止血帶系統市場預計到 2025 年將達到 5.497 億美元,年複合成長率為 8.2%,到 2035 年將達到 12 億美元。
外科手術和急救過程中對有效血流管理的需求不斷成長,持續推動全球市場的擴張。創傷、急診和整形外科手術數量的增加,顯著促進了醫療機構對先進止血帶系統的廣泛應用。止血帶系統旨在手術和急救過程中對肢體施加可控壓力,暫時阻斷血液循環。人們對快速止血的認知不斷提高,以及創傷護理基礎設施的進步,進一步加速了醫院、門診診所、軍事醫療單位和急救服務機構對止血帶系統的需求。肌肉骨骼疾病和與老齡化相關的整形外科疾病發病率的上升,也推動了全球重組和關節關節重建手術數量的成長,進一步增加了對可靠止血帶解決方案的需求。此外,手術器械的持續創新、醫療保健投資的增加以及對病人安全的日益重視,都促使醫療專業人員採用技術先進的止血帶系統,以提高手術精度、最大限度地減少出血,並提升手術效率。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 5.497億美元 |
| 預測金額 | 12億美元 |
| 複合年成長率 | 8.2% |
由於止血帶袖套在醫療手術中提供穩定可控的壓力方面發揮著至關重要的作用,預計到2025年,止血袖套市場佔有率將達到68%。這些袖套因其多種配置、尺寸和材質可供選擇,以滿足不同的臨床需求和患者解剖結構,因此在外科手術中廣泛應用。袖套技術的進步,例如壓力均勻性的提高、患者舒適度的提升以及組織相關併發症的減少,進一步推動了其在醫療機構中的普及。此外,對手術精準度和病人安全的日益重視也促進了對技術更先進的袖套系統的需求成長。
預計到2025年,醫院止血帶市場規模將達到2.641億美元。由於在先進的手術設施中進行的整形外科、創傷、血管和重組手術數量不斷增加,醫院仍然是止血帶系統的最大用戶。熟練的醫務人員、現代化的手術基礎設施以及先進手術技術的應用,都促進了止血帶產品在醫院環境中的使用。此外,為簡化手術流程和減少術中併發症所採取的措施,也推動了該細分市場的長期成長。
預計到2025年,北美止血帶系統市佔率將達到39.3%,並在整個預測期內保持顯著成長。該地區市場成長的主要促進因素包括創傷病例數量龐大、外科手術量增加以及對先進血液管理技術的強勁需求。高度發展的醫療基礎設施、創新手術器械的快速普及以及眾多成熟醫療技術公司的強大影響力,持續推動著全部區域市場的擴張。醫療機構日益重視改善治療效果、提高手術效率和降低術中風險,這進一步推動了止血帶系統在整體臨床應用中的廣泛應用。
目錄
第1章:調查方法
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 影響產業的因素
- 促進因素
- 創傷和事故案件數量增加
- 關節重建手術數量增加
- 成人族群中退化性骨病和肌肉骨骼疾病的盛行率增加。
- 提高對出血管理的認知
- 止血帶系統的技術進步
- 產業潛在風險與挑戰
- 熟練專業人員短缺
- 可重複使用袖口的增加會導致感染疾病的傳播。
- 機會
- 開發具有即時壓力監測功能的智慧止血帶
- 將人工智慧和物聯網整合到自動化壓力控制系統中
- 促進因素
- 成長潛力分析
- 監理情勢
- 價格趨勢分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 未來市場趨勢
- 專利分析
- 人工智慧和生成式人工智慧對市場的影響
- 波特的分析
- PESTLE分析
第4章 競爭情勢
- 介紹
- 企業矩陣分析
- 企業市佔率分析
- 世界
- 北美洲
- 歐洲
- 亞太地區
- LAMEA
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估計與預測:依組件分類,2022-2035年
- 止血帶裝置
- 止血袖口
- 氣動
- 拋棄式的
- 可重複使用的
- 非氣動
- 氣動
第6章 市場估計與預測:依應用領域分類,2022-2035年
- 上肢
- 下肢
第7章 市場估計與預測:依最終用途分類,2022-2035年
- 醫院
- 門診手術中心
- 其他最終用戶
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 荷蘭
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第9章:公司簡介
- Anetic Aid
- ATMOS Medizintechnik
- CAT Resources, LLC
- Delfi
- DESSILLIONS & DUTRILLAUX
- Hammarplast Medical AB
- OHK Medical Devices
- REVMED X
- Rudolf Riester GmbH
- SAM MEDICAL
- stryker
- TACMED Solutions
- Teleflex Incorporated
- ulrich medical
- VBM Medizintechnik GmbH
- ZIMMER BIOMET
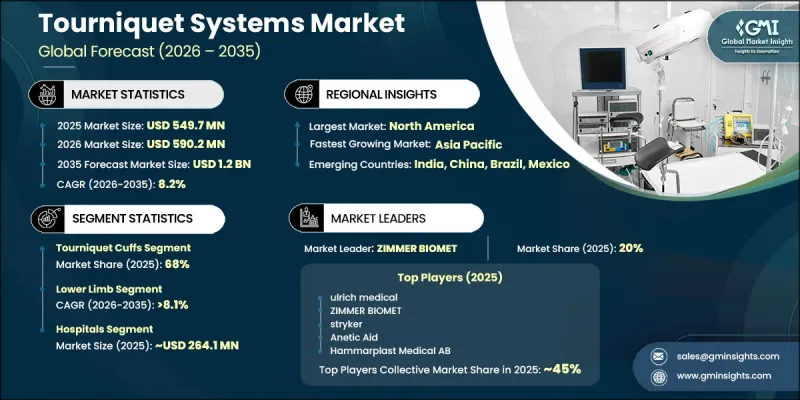
The Global Tourniquet Systems Market was valued at USD 549.7 million in 2025 and is estimated to grow at a CAGR of 8.2% to reach USD 1.2 billion by 2035.
Rising demand for effective blood flow management during surgical and emergency procedures continues to support market expansion worldwide. Increasing cases of traumatic injuries, emergency surgeries, and orthopedic procedures are significantly contributing to the growing adoption of advanced tourniquet systems across healthcare facilities. A tourniquet system is designed to apply controlled pressure to an extremity to temporarily restrict blood circulation during surgeries or emergency treatment procedures. Growing awareness regarding rapid hemorrhage control and advancements in trauma care infrastructure are further accelerating product demand across hospitals, ambulatory care centers, military medical units, and emergency response services. The increasing incidence of musculoskeletal conditions and age-related orthopedic disorders has also elevated the number of reconstructive and joint replacement surgeries globally, strengthening the need for reliable tourniquet solutions. In addition, continuous innovation in surgical equipment, rising healthcare investments, and increasing focus on patient safety are encouraging healthcare providers to adopt technologically advanced tourniquet systems that improve surgical precision, minimize blood loss, and enhance operational efficiency during procedures.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $549.7 Million |
| Forecast Value | $1.2 Billion |
| CAGR | 8.2% |
The tourniquet cuffs segment held a share of 68% in 2025 due to its essential role in delivering consistent and controlled pressure during medical procedures. These cuffs remain widely used across surgical settings because they are available in multiple configurations, sizes, and material compositions to suit varying clinical requirements and patient anatomies. Advancements in cuff engineering, including improved pressure uniformity, enhanced patient comfort, and reduced tissue-related complications, have further supported strong adoption across healthcare environments. The growing emphasis on surgical accuracy and patient safety is also contributing to increased demand for technologically improved cuff systems.
The hospitals segment generated USD 264.1 million in 2025. Hospitals continue to account for the highest usage of tourniquet systems due to rising volumes of orthopedic, trauma, vascular, and reconstructive surgeries performed within advanced surgical facilities. The presence of skilled healthcare professionals, modern operating infrastructure, and growing integration of advanced surgical technologies has strengthened product utilization in hospital settings. Increasing efforts to improve surgical workflow efficiency and reduce intraoperative complications are also supporting long-term market growth in this segment.
North America Tourniquet Systems Market accounted for 39.3% share in 2025 and is expected to witness notable growth throughout the forecast period. The regional market is supported by a high volume of trauma-related cases, increasing surgical procedures, and strong demand for advanced blood management technologies. A highly developed healthcare infrastructure, rapid adoption of innovative surgical devices, and strong presence of established medical technology companies continue to reinforce market expansion across the region. Healthcare providers are increasingly focusing on improving procedural outcomes, enhancing surgical efficiency, and reducing operative risks, which is further encouraging widespread deployment of tourniquet systems across clinical applications.
Key companies operating in the Tourniquet Systems Market include Anetic Aid, ATMOS Medizintechnik, CAT Resources, LLC, Delfi, DESSILLIONS & DUTRILLAUX, Hammarplast Medical AB, OHK Medical Devices, REVMED X, Rudolf Riester GmbH, SAM MEDICAL, Stryker, TACMED Solutions, Teleflex Incorporated, ulrich medical, VBM Medizintechnik GmbH, and ZIMMER BIOMET. Companies participating in the global tourniquet systems market are focusing on multiple strategic initiatives to strengthen their competitive position and expand market reach. Manufacturers are heavily investing in product innovation to develop advanced tourniquet systems with improved pressure control, enhanced safety features, and greater patient comfort. Many companies are also emphasizing lightweight and portable designs to support emergency care, military applications, and ambulatory surgical settings. Strategic collaborations with hospitals, surgical centers, and healthcare distributors are helping businesses improve product accessibility and strengthen customer relationships. In addition, organizations are increasing investments in research and development to integrate digital monitoring technologies and automated pressure management systems into their product portfolios.
Table of Contents
Chapter 1 Research Methodology
- 1.1 Research approach
- 1.2 Quality commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research trail & confidence scoring
- 1.3.1 Research trail components
- 1.3.2 Scoring components
- 1.4 Data collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional trends
- 2.2.2 Component trends
- 2.2.3 Application trends
- 2.2.4 End use trends
- 2.3 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing number of trauma and accident cases.
- 3.2.1.2 Rising number of joint replacement surgeries.
- 3.2.1.3 Increasing prevalence of degenerative bone disorders and musculoskeletal diseases among adult population.
- 3.2.1.4 Rising awareness of blood loss management.
- 3.2.1.5 Technological advancements in tourniquet systems.
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Dearth of skilled professionals.
- 3.2.2.2 Transmission of infectious diseases associated with increasing use of reusable cuffs.
- 3.2.3 Opportunities
- 3.2.3.1 Development of smart tourniquets with real-time pressure monitoring
- 3.2.3.2 Integration of AI and IoT for automated pressure control systems
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.5 Pricing trend analysis
- 3.6 Technology and innovation landscape (Driven by Primary Research)
- 3.6.1 Current technological trends
- 3.6.2 Emerging technologies
- 3.7 Future market trends (Driven by Primary Research)
- 3.8 Patent analysis
- 3.9 Impact of AI & Generative AI on the Market (Driven by Primary Research)
- 3.10 Porter's analysis
- 3.11 PESTEL analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company matrix analysis
- 4.3 Company market share analysis (Driven by Primary Research)
- 4.3.1 Global
- 4.3.2 North America
- 4.3.3 Europe
- 4.3.4 Asia Pacific
- 4.3.5 LAMEA
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates and Forecast, By Component, 2022 - 2035 ($ Mn)
- 5.1 Key trends
- 5.2 Tourniquet instruments
- 5.3 Tourniquet cuffs
- 5.3.1 Pneumatic
- 5.3.1.1 Disposable
- 5.3.1.2 Reusable
- 5.3.2 Non-pneumatic
- 5.3.1 Pneumatic
Chapter 6 Market Estimates and Forecast, By Application, 2022 - 2035 ($ Mn)
- 6.1 Key trends
- 6.2 Upper limb
- 6.3 Lower limb
Chapter 7 Market Estimates and Forecast, By End Use, 2022 - 2035 ($ Mn)
- 7.1 Key trends
- 7.2 Hospitals
- 7.3 Ambulatory surgical centers
- 7.4 Other end users
Chapter 8 Market Estimates and Forecast, By Region, 2022 - 2035 ($ Mn)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Netherlands
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 Japan
- 8.4.3 India
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 MEA
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Anetic Aid
- 9.2 ATMOS Medizintechnik
- 9.3 CAT Resources, LLC
- 9.4 Delfi
- 9.5 DESSILLIONS & DUTRILLAUX
- 9.6 Hammarplast Medical AB
- 9.7 OHK Medical Devices
- 9.8 REVMED X
- 9.9 Rudolf Riester GmbH
- 9.10 SAM MEDICAL
- 9.11 stryker
- 9.12 TACMED Solutions
- 9.13 Teleflex Incorporated
- 9.14 ulrich medical
- 9.15 VBM Medizintechnik GmbH
- 9.16 ZIMMER BIOMET

 2026年下一代止血帶全球市場報告
 外科止血帶市場:依產品類型、應用、最終用戶及通路分類-2026-2032年全球市場預測
 全球止血帶系統市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 全球止血帶系統市場
 氣動止血帶市場規模、佔有率和成長分析:按產品類型、肢體類型、最終用戶和地區分類-2026-2033年產業預測
 止血帶系統市場規模、佔有率和成長分析:按產品類型、袖帶類型、患者類型、應用、最終用戶、分銷管道和地區分類-2026-2033年產業預測
 外科止血帶市場:市場洞察、競爭格局及市場預測(2034 年)
 外科止血帶市場:按產品類型、應用、最終用戶和地區分類
 止血帶市場報告:趨勢、預測與競爭分析(至2035年)2026年全球止血帶袖套市場報告