


 |
市場調查報告書
商品編碼
2045845
2026 年至 2035 年鈑金加工服務的市場機會、成長要素、產業趨勢與預測。Sheet Metal Fabrication Services Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025年全球鈑金加工服務市場價值為873億美元,預計到2035年將以4.6%的複合年成長率成長至1365億美元。
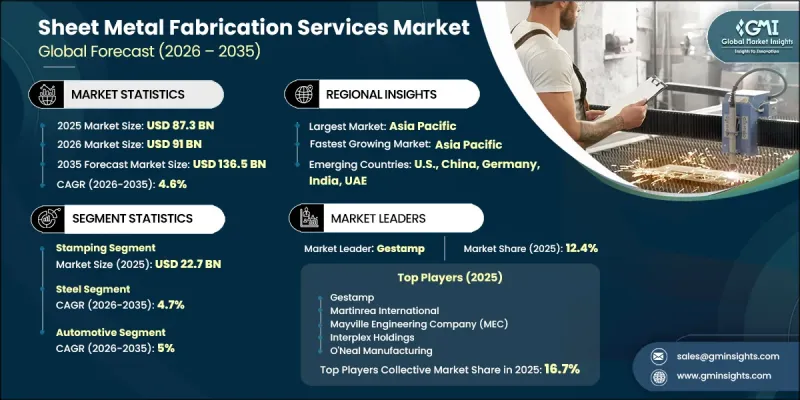
鈑金加工服務業正經歷穩定成長,這主要得益於汽車、航太和建築等關鍵產業對輕質耐用材料日益成長的需求。這些產業越來越依賴精密設計的零件,而鈑金加工服務能夠有效率且可靠地提供這些零件。隨著製造商尋求能夠提高能源效率並降低整車重量的材料,電動車解決方案的日益普及進一步加速了市場需求。同時,自動化切割、精密焊接和積層製造等加工技術的進步顯著提高了生產效率,最大限度地減少了材料浪費,並實現了複雜形狀的加工。此外,新興國家基礎設施項目的擴張也促進了市場成長,因為住宅、商業和工業建設的大規模投資增加了對金屬加工零件的需求。此外,旨在改善加工技術和材料性能的持續研發工作也將繼續支撐市場的長期擴張。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 873億美元 |
| 預計金額 | 1365億美元 |
| 複合年成長率 | 4.6% |
預計到2025年,沖壓加工市場規模將達到227億美元,並在2035年之前維持4.6%的複合年成長率。該市場持續成長的動力源於其在眾多行業的廣泛應用,這些行業都需要大規模生產性能穩定、經久耐用的零件。對輕量化、高強度零件日益成長的需求推動了沖壓加工製程的普及,而製造技術的不斷進步則提高了生產效率和產品品質。
預計到2025年,鋼鐵業將佔據54%的市場佔有率,並在2026年至2035年間以4.7%的複合年成長率成長。鋼鐵的廣泛應用得益於其強度高、成本效益好以及在各行業的適應性強。鋼鐵加工技術的進步以及對兼具耐用性和輕量化特性的材料日益成長的需求,正進一步推動該行業的成長。
預計到2025年,美國鈑金加工服務市場將佔據80%的市場佔有率,市場規模將達到190億美元。美國市場成長的主要驅動力是強勁的工業發展和成熟的製造業基礎。包括建築、能源和重工業在內的多個行業的擴張,持續推動對加工服務的穩定需求。傳統產業和新興產業的投資增加,進一步增強了市場前景。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 影響價值鏈的因素
- 利潤率分析
- 中斷
- 前景
- 服務供應商
- 價值鏈分析
- 原物料供應商
- 製造服務供應商
- 配送/物流
- 終端用戶
- 價值鏈各階段的利潤率分析
- 2025年價格分析
- 對過去價格趨勢的分析
- 定價策略:按業務類型分類
- 產品類型和技術世代導致的價格波動
- 消費者價格敏感度分析
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 市場機遇
- 成長潛力分析
- 監理情勢
- 全球製造業和工業安全法律規範
- 北美 - OSHA 標準和行業法規
- 環境合規性和永續性要求
- 合規要求
- 波特的分析
- PESTLE分析
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 未來市場趨勢
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估價與預測:依服務類型分類,2022-2035年
- 切割
- 沖孔
- 可按壓
- 模具
- 彎曲過程
- 焊接
- 精加工
- 其他
第6章 市場估計與預測:依材料分類,2022-2035年
- 鋼
- 鋁
- 銀
- 其他(銅、黃銅、不銹鋼等)
第7章 市場估計與預測:依最終用途產業分類,2022-2035年
- 車
- Kei car(迷你車)
- 商用車輛
- 電動車
- 航太
- 民用航太
- 國防航太
- 工業機械
- 製造設備
- 物料輸送系統
- 加工機械
- 建造
- 電子設備
- 資料中心
- 其他(例如,通訊)
第8章 市場估算與預測:依通路分類,2022-2035年
- 直銷
- 間接銷售
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 荷蘭
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- UAE
第10章:公司簡介
- 全球主要公司
- BTD Manufacturing
- Gestamp
- Interplex Holdings
- Kapco Global
- Martinrea International
- Mayville Engineering Company(MEC)
- MW Industries
- 該地區的主要公司
- All Metals Fabrication
- Ironform Corporation
- Manor Tool & Manufacturing
- Noble Industries
- O'Neal Manufacturing Services
- Ryerson Advanced Processing
- Standard Iron & Wire Works
- Emerging Niche Specialist
- Approved Sheet Metal(ASM)
- Buckeye Shapeform
- Capps Manufacturing
- Kencoa Aerospace LLC
- Laserage Technology Corporation
- V&F Sheet Metal
- Xometry
The Global Sheet Metal Fabrication Services Market was valued at USD 87.3 billion in 2025 and is estimated to grow at a CAGR of 4.6% to reach USD 136.5 billion by 2035.
The sheet metal fabrication services industry is witnessing steady expansion driven by the growing requirement for lightweight yet durable materials across key sectors such as automotive, aerospace, and construction. These industries increasingly depend on precision-engineered components, which fabrication services deliver with efficiency and consistency. The rising adoption of electric mobility solutions is further accelerating demand, as manufacturers seek materials that enhance energy efficiency and reduce overall vehicle weight. In parallel, advancements in fabrication technologies, including automated cutting, precision welding, and additive manufacturing, are significantly improving production efficiency, minimizing material waste, and enabling the development of complex geometries. Expanding infrastructure projects across developing economies are also contributing to market growth, as large-scale investments in residential, commercial, and industrial construction increase the need for fabricated metal components. Additionally, ongoing research and development efforts aimed at enhancing fabrication techniques and improving material performance continue to support long-term market expansion.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $87.3 Billion |
| Forecast Value | $136.5 Billion |
| CAGR | 4.6% |
The stamping segment accounted for USD 22.7 billion in 2025 and is expected to grow at a CAGR of 4.6% through 2035. This segment continues to gain traction due to its extensive application across multiple industries that require high-volume production of consistent and durable components. Increasing demand for lightweight and strong parts is supporting the adoption of stamping processes, while continuous improvements in manufacturing technologies are enhancing efficiency and output quality.
The steel segment held a 54% share in 2025 and is anticipated to grow at a CAGR of 4.7% from 2026 to 2035. Its widespread use is driven by its strength, cost-effectiveness, and adaptability across various industries. Advancements in steel processing and the growing need for materials that balance durability with reduced weight are further supporting segment growth.
United States Sheet Metal Fabrication Services Market held 80% share, generating USD 19 billion in 2025. Market growth in the country is fueled by strong industrial development and a well-established manufacturing base. Expansion across multiple sectors, including construction, energy, and heavy industries, continues to create sustained demand for fabrication services. Increasing investments in both traditional and emerging industries are further strengthening the market outlook.
Key companies operating in the Global Sheet Metal Fabrication Services Market include BTD Manufacturing, Gestamp, Interplex Holdings, Kapco Global, Martinrea International, Mayville Engineering Company (MEC), MW Industries, All Metals Fabrication, Ironform Corporation, Manor Tool & Manufacturing, Noble Industries, O'Neal Manufacturing Services, Ryerson Advanced Processing, Standard Iron & Wire Works, Approved Sheet Metal (ASM), Buckeye Shapeform, Capps Manufacturing, Kencoa Aerospace LLC, Laserage Technology Corporation, V&F Sheet Metal, and Xometry. Companies in the sheet metal fabrication services market are focusing on strategic investments in advanced manufacturing technologies to enhance efficiency and precision. Many players are adopting automation, digital manufacturing systems, and smart production processes to reduce operational costs and improve turnaround times. Expanding production capabilities and geographic presence through partnerships, acquisitions, and facility upgrades is also a key approach to strengthen market positioning. Firms are prioritizing research and development to introduce innovative fabrication techniques and improve material performance.
Table of Contents
Chapter 1 Methodology and scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Service Type
- 2.2.3 Material
- 2.2.4 End Use Industry
Chapter 3 Industry insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Factor affecting the value chain
- 3.1.2 Profit margin analysis
- 3.1.3 Disruptions
- 3.1.4 Future outlook
- 3.1.5 Service provider
- 3.2 Value Chain Analysis
- 3.2.1 Raw material suppliers
- 3.2.2 Fabrication service providers
- 3.2.3 Distribution and logistics
- 3.2.4 End-use customers
- 3.2.5 Profit margin analysis by value chain stage
- 3.3 Pricing analysis, 2025 (driven by primary research)
- 3.3.1 Historical price trend analysis
- 3.3.2 Pricing strategy by player type
- 3.3.3 Price variation by product type & technology generation
- 3.3.4 Consumer price sensitivity analysis
- 3.4 Industry impact forces
- 3.4.1 Growth drivers
- 3.4.2 Industry pitfalls & challenges
- 3.4.3 Market opportunities
- 3.5 Growth potential analysis
- 3.6 Regulatory landscape
- 3.6.1 Global regulatory framework for manufacturing and industrial safety
- 3.6.2 North America - OSHA standards and industry regulations
- 3.6.3 Environmental compliance and sustainability mandates
- 3.6.4 Compliance requirements
- 3.7 Porter's analysis
- 3.8 PESTEL analysis
- 3.9 Technological and innovation landscape
- 3.9.1 Current technological trends
- 3.9.2 Emerging technologies
- 3.10 Future market trends
- 3.11 Impact of AI & generative ai on the market
- 3.11.1 AI-driven disruption of existing business models
- 3.11.2 GenAI use cases & adoption roadmap by segment
- 3.11.3 Risks, limitations & regulatory considerations
Chapter 4 Competitive landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Latin America
- 4.2.5 MEA
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates & Forecast, By Service Type, 2022 - 2035 ($Billion)
- 5.1 Key trends
- 5.2 Cutting
- 5.3 Punching
- 5.4 Stamping
- 5.5 Forming
- 5.6 Bending
- 5.7 Welding
- 5.8 Finishing
- 5.9 Others
Chapter 6 Market Estimates & Forecast, By Material, 2022 - 2035 ($Billion)
- 6.1 Key trends
- 6.2 Steel
- 6.3 Aluminum
- 6.4 Silver
- 6.5 Others (copper, brass, stainless steel etc.)
Chapter 7 Market Estimates & Forecast, By End Use Industry, 2022 - 2035 ($Billion)
- 7.1 Key trends
- 7.2 Automotive
- 7.2.1 Light vehicles
- 7.2.2 Commercial vehicles
- 7.2.3 Electric vehicles
- 7.3 Aerospace & Space
- 7.3.1 Commercial aerospace
- 7.3.2 Defense aerospace
- 7.4 Industrial Machinery
- 7.4.1 Manufacturing equipment
- 7.4.2 Material handling systems
- 7.4.3 Processing machinery
- 7.5 Construction
- 7.6 Electronics
- 7.7 Data Centers
- 7.8 Others (telecommunication etc.)
Chapter 8 Market Estimates & Forecast, By Distribution Channel, 2022 - 2035 ($Billion)
- 8.1 Key trends
- 8.2 Direct sales
- 8.3 Indirect sales
Chapter 9 Market Estimates & Forecast, By Region, 2022 - 2035 ($Billion)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.3.6 Netherlands
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 Japan
- 9.4.3 India
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 MEA
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 BTD Manufacturing
- 10.1.2 Gestamp
- 10.1.3 Interplex Holdings
- 10.1.4 Kapco Global
- 10.1.5 Martinrea International
- 10.1.6 Mayville Engineering Company (MEC)
- 10.1.7 MW Industries
- 10.2 Regional Key Players
- 10.2.1 All Metals Fabrication
- 10.2.2 Ironform Corporation
- 10.2.3 Manor Tool & Manufacturing
- 10.2.4 Noble Industries
- 10.2.5 O'Neal Manufacturing Services
- 10.2.6 Ryerson Advanced Processing
- 10.2.7 Standard Iron & Wire Works
- 10.3 Emerging Niche Specialist
- 10.3.1 Approved Sheet Metal (ASM)
- 10.3.2 Buckeye Shapeform
- 10.3.3 Capps Manufacturing
- 10.3.4 Kencoa Aerospace LLC
- 10.3.5 Laserage Technology Corporation
- 10.3.6 V&F Sheet Metal
- 10.3.7 Xometry


