

 |
市場調查報告書
商品編碼
2038387
企業資產管理市場機會、成長要素、產業趨勢分析及2026-2035年預測Enterprise Asset Management Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球企業資產管理市場預計到 2025 年將達到 61 億美元,並預計以 11.3% 的複合年成長率成長,到 2035 年將達到 172 億美元。
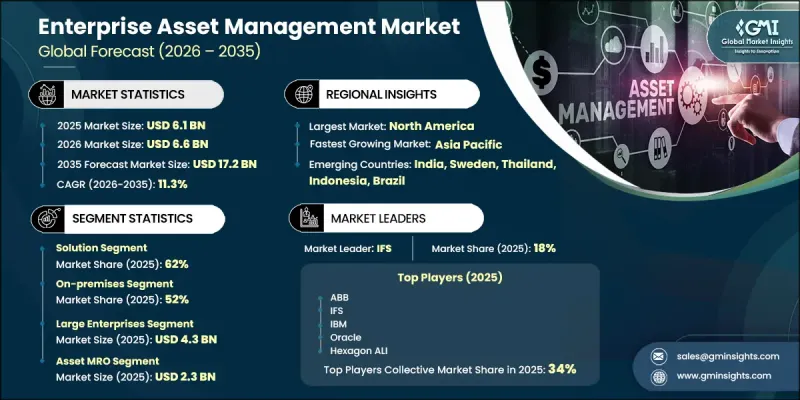
市場成長主要得益於旨在提升資產性能、最佳化維護計劃並實現跨行業預測性維護策略的數位化技術的日益普及。併購和策略聯盟不斷增強解決方案能力和市場覆蓋率,日益塑造競爭格局。資產密集型行業的企業正在利用企業資產管理系統 (EAM) 來提高營運效率、減少意外停機時間並提升決策準確性。人工智慧、物聯網連接和巨量資料分析等先進技術的整合,實現了即時資產監控,並提供預測性洞察,從而提升效能並降低營運成本。資產管理流程持續向數位轉型,使 EAM 解決方案成為實現擴充性、高效和永續營運的關鍵工具。儘管 COVID-19 疫情初期由於預算限制、勞動力中斷和資本投資延遲而減緩了 EAM 解決方案的普及速度,但也凸顯了資產可視性和維護計劃方面存在的重大挑戰。這正在加速眾多企業的數位轉型進程,並增強全球各產業對 EAM 解決方案的長期需求。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 61億美元 |
| 預測金額 | 172億美元 |
| 複合年成長率 | 11.3% |
預計到2025年,解決方案業務部門將佔據62%的市場佔有率,並在2026年至2035年間以10.5%的複合年成長率成長。該板塊的成長主要得益於市場對整合軟體平台日益成長的需求,這些平台能夠實現即時資產追蹤、預測性維護和生命週期管理。這些解決方案支援從採購到處置的端到端資產管理,同時整合了人工智慧和物聯網等技術,以增強預測分析能力、最大限度地減少停機時間並提高整體營運效率。
預計到2025年,資產維護、維修和營運(MRO)市場規模將達到23億美元。由於數位化進步、成本最佳化壓力以及基礎設施投資的增加,該領域正在經歷轉型。各組織正逐步從被動維護方式轉向預測性和基於狀態的維護策略。物聯網感測器和基於人工智慧的故障預測系統的日益普及推動了這一轉變,這些技術提高了資產可靠性,並減少了工業環境中與維護相關的中斷。
預計2025年,美國企業資產管理市場規模將達21億美元。推動美國市場擴張的主要因素是聯邦、州和私人投資的基礎設施項目廣泛採用企業資產管理框架。管理大規模基礎設施組合的政府機構正擴大採用結構化的資產管理系統,以提高營運效率、延長資產使用壽命並確保合規性。這種強而有力的組織採納將持續鞏固美國在區域市場的領先地位。
Oracle、SAP、IBM、IFS、AVEVA、ABB、Hexagon ALI、Aptean、CGI 和 Salesforce 是企業資產管理 (EAM) 市場的主要參與者。這些公司致力於透過持續的產品創新和平台整合來增強自身競爭力。它們也大力投資人工智慧、物聯網連接和進階分析,以提升預測性維護能力並增強資產全生命週期的可視性。策略聯盟、併購等措施正被用來拓展技術能力和全球市場覆蓋範圍。供應商也優先考慮基於雲端的部署,以提高最終用戶的擴充性、柔軟性和成本效益。此外,各公司正在增強 EAM 平台的行動存取性和使用者體驗,以支援即時決策。進軍新興市場和開發產業專用的解決方案,進一步幫助各公司擴大基本客群,並鞏固其在各產業領域的長期市場地位。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章業界考察
- 生態系分析
- 供應商情況
- 解決方案供應商和平台供應商
- 實施夥伴和系統整合商
- 技術基礎設施和基礎設施供應商
- 託管服務供應商
- 終端用戶公司
- 成本結構
- 利潤率
- 每個階段增加的價值
- 垂直整合趨勢
- 顛覆者
- 供應商情況
- 影響因素
- 促進因素
- 資產生命週期最佳化的需求日益成長
- 在資產密集型產業中擴大採用範圍
- 與物聯網和預測性維護技術的整合
- 監管合規和資產績效標準
- 產業潛在風險與挑戰
- 高昂的實施和整合成本
- 資料管理和遷移面臨的挑戰
- 市場機遇
- 遷移到基於雲端和基於SaaS的企業資產管理平台
- 與人工智慧和高級分析的整合
- 擴大行動企業資產管理解決方案的應用
- 與企業系統整合
- 促進因素
- 技術趨勢與創新生態系統
- 目前技術
- 新興技術
- 成長潛力分析
- 監理情勢
- 北美洲
- 通貨膨脹控制法案(IRA)
- 網路安全與基礎設施安全框架(CISA)
- 歐洲
- 歐洲綠色新政
- NIS2 指令和 GDPR 合規框架
- 亞太地區
- 中國碳排放「達峰與碳中和」政策框架
- 「數位印度」計劃與智慧基礎設施使命
- 拉丁美洲
- 巴西國家基礎設施現代化計劃
- 墨西哥能源和工業合規標準(NOM框架)
- 中東和非洲
- 阿拉伯聯合大公國2050年淨零排放策略
- 沙烏地阿拉伯2030願景工業數位化計劃
- 北美洲
- 波特五力分析
- PESTEL 分析
- 專利分析(基於初步研究)
- 價格分析(基於初步調查)
- 對過去價格趨勢的分析
- 按玩家類型分類的定價策略
- 基本案例狀況
- 用例
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 關於碳足跡的考量
- 人工智慧和生成式人工智慧對市場的影響
- 利用人工智慧改造現有經營模式
- 按細分市場分類的生成式人工智慧用例和部署藍圖
- 風險、限制和監管考量
- 預測假設和情境分析(基於初步研究)
- 基本案例-驅動複合年成長率的關鍵宏觀經濟與產業變量
- 樂觀情境-宏觀經濟與產業的順風
- 悲觀情景-宏觀經濟放緩或產業逆風
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 企業級分層基準測試
- 層級分類標準與選擇標準
- 按銷售額、地區和創新能力分類的層級定位矩陣。
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃及資金籌措
第5章 市場估計與預測:依組件分類,2022-2035年
- 解決方案
- 資產生命週期管理
- 預測性保護
- 工單管理
- 勞動管理
- 設施管理
- 庫存管理
- 服務
- 專業服務
- 託管服務
第6章 市場估算與預測:依部署模式分類,2022-2035年
- 現場
- 雲
第7章 市場估計與預測:依組織規模分類,2022-2035年
- 大公司
- 小型企業
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 資產維護、維修和運營
- 線性資產
- 非線性資產
- 現場服務管理
第9章 市場估計與預測:依最終用途分類,2022-2035年
- 能源與公共產業
- 製造業
- 資訊科技/通訊
- 衛生保健
- 石油和天然氣
- 運輸/物流
- 政府/公共部門
- 其他
第10章 市場估價與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 比利時
- 荷蘭
- 瑞典
- 俄羅斯
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 新加坡
- 韓國
- 越南
- 印尼
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲(MEA)
- 南非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
第11章:公司簡介
- 世界公司
- ABB
- Aptean
- AVEVA
- CGI
- IBM
- IFS A
- Infor
- Oracle
- Salesforce
- SAP
- 當地公司
- Asset Panda
- AssetWorks
- eMaint
- EZOfficeInventory
- Fleetio
- Ramco Systems
- Ultimo Software
- 新興企業
- KloudGin
- Maintenance Connection
- UpKeep
The Global Enterprise Asset Management Market was valued at USD 6.1 billion in 2025 and is estimated to grow at a CAGR of 11.3% to reach USD 17.2 billion by 2035.
Market growth is strongly supported by the rising adoption of digital technologies aimed at improving asset performance, optimizing maintenance schedules, and enabling predictive maintenance strategies across industries. The competitive environment is increasingly shaped by mergers, acquisitions, and strategic partnerships that enhance solution capabilities and market reach. Organizations operating in asset-intensive sectors are leveraging enterprise asset management systems to improve operational efficiency, reduce unplanned downtime, and strengthen decision-making accuracy. Integration of advanced technologies such as artificial intelligence, Internet of Things connectivity, and big data analytics is enabling real-time asset monitoring and delivering predictive insights that improve performance and reduce operational costs. The ongoing shift toward digital transformation in asset management processes is positioning EAM solutions as critical tools for achieving scalable, efficient, and sustainable operations. Although the COVID-19 period initially slowed implementation due to budget limitations, workforce disruptions, and postponed capital investments, it also exposed significant gaps in asset visibility and maintenance planning. This led many organizations to accelerate digital transformation initiatives, strengthening long-term demand for EAM solutions across global industries.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $6.1 Billion |
| Forecast Value | $17.2 Billion |
| CAGR | 11.3% |
The solutions segment accounted for 62% share in 2025 and is expected to grow at a CAGR of 10.5% from 2026 to 2035. Growth in this segment is driven by increasing demand for integrated software platforms that enable real-time asset tracking, predictive maintenance, and complete lifecycle management. These solutions support end-to-end asset oversight from procurement to retirement, while incorporating technologies such as artificial intelligence and IoT to enhance predictive analytics capabilities, minimize downtime, and improve overall operational efficiency.
The asset maintenance, repair, and operations segment captured USD 2.3 billion in 2025. This segment is undergoing transformation due to rising digital adoption, cost optimization pressures, and increased infrastructure investments. Organizations are progressively moving away from reactive maintenance approaches toward predictive and condition-based strategies. This shift is supported by the growing deployment of IoT sensors and AI-based failure prediction systems, which are improving asset reliability and reducing maintenance-related disruptions across industrial environments.
United States Enterprise Asset Management Market generated USD 2.1 billion in 2025. Market expansion in the country is driven by the widespread implementation of enterprise asset management frameworks across federal, state, and privately funded infrastructure programs. Government agencies managing large-scale infrastructure portfolios are increasingly adopting structured asset management systems to improve operational efficiency, extend asset lifecycles, and ensure regulatory compliance. This strong institutional adoption continues to reinforce the United States' leadership position in the regional market.
Oracle, SAP, IBM, IFS, AVEVA, ABB, Hexagon ALI, Aptean, CGI, and Salesforce are among the key companies operating in the Enterprise Asset Management Market. Companies in the Enterprise Asset Management Market are focusing on strengthening their competitive position through continuous product innovation and platform integration. They are investing heavily in artificial intelligence, IoT connectivity, and advanced analytics to enhance predictive maintenance capabilities and improve asset lifecycle visibility. Strategic partnerships, mergers, and acquisitions are being used to expand technological capabilities and global market reach. Vendors are also prioritizing cloud-based deployments to improve scalability, flexibility, and cost efficiency for end users. In addition, companies are enhancing mobile accessibility and user experience within EAM platforms to support real-time decision-making. Expansion into emerging markets and industry-specific solution development is further helping firms broaden their customer base and reinforce long-term market presence across diverse industrial sectors.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Component
- 2.2.2 Deployment Model
- 2.2.3 Organization Size
- 2.2.4 Application
- 2.2.5 End Use
- 2.2.6 Regional
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.1.1 Solution providers & platform vendors
- 3.1.1.2 Implementation partners & system integrators
- 3.1.1.3 Technology enablers & infrastructure providers
- 3.1.1.4 Managed service providers
- 3.1.1.5 End-user organizations
- 3.1.2 Cost structure
- 3.1.3 Profit margin
- 3.1.4 Value addition at each stage
- 3.1.5 Vertical integration trends
- 3.1.6 Disruptors
- 3.1.1 Supplier landscape
- 3.2 Impact on forces
- 3.2.1 Growth drivers
- 3.2.1.1 Increasing need for asset lifecycle optimization
- 3.2.1.2 Rising adoption across asset-intensive industries
- 3.2.1.3 Integration with IoT and predictive maintenance technologies
- 3.2.1.4 Regulatory compliance and asset performance standards
- 3.2.2 Industry pitfalls & challenges
- 3.2.2.1 High implementation and integration costs
- 3.2.2.2 Data management and migration challenges
- 3.2.3 Market opportunities
- 3.2.3.1 Shift toward cloud-based and SaaS EAM platforms
- 3.2.3.2 Integration with AI and advanced analytics
- 3.2.3.3 Increasing adoption of mobile EAM solutions
- 3.2.3.4 Convergence with enterprise systems
- 3.2.1 Growth drivers
- 3.3 Technology trends & innovation ecosystem
- 3.3.1 Current technologies
- 3.3.2 Emerging technologies
- 3.4 Growth potential analysis
- 3.5 Regulatory landscape
- 3.5.1 North America
- 3.5.1.1 Inflation Reduction Act (IRA)
- 3.5.1.2 Cybersecurity & Infrastructure Security Framework (CISA)
- 3.5.2 Europe
- 3.5.2.1 European Green Deal
- 3.5.2.2 NIS2 Directive & GDPR Compliance Framework
- 3.5.3 Asia-Pacific
- 3.5.3.1 China Dual Carbon Policy Framework
- 3.5.3.2 Digital India Initiative & Smart Infrastructure Mission
- 3.5.4 Latin America
- 3.5.4.1 Brazil National Infrastructure Modernization Program
- 3.5.4.2 Mexico Energy & Industrial Compliance Standards (NOM Framework)
- 3.5.5 Middle East & Africa
- 3.5.5.1 UAE Net Zero 2050 Strategy
- 3.5.5.2 Saudi Vision 2030 Industrial Digitalization Program
- 3.5.1 North America
- 3.6 Porter's analysis
- 3.7 PESTEL analysis
- 3.8 Patent analysis (Driven by Primary Research)
- 3.9 Pricing Analysis (Driven by Primary Research)
- 3.9.1 Historical Price Trend Analysis
- 3.9.2 Pricing Strategy by Player Type
- 3.10 Base case scenarios
- 3.11 Use cases
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.12.5 Carbon footprint considerations
- 3.13 Impact of AI & generative AI on the market
- 3.13.1 AI-driven disruption of existing business models
- 3.13.2 GenAI use cases & adoption roadmap by segment
- 3.13.3 Risks, limitations & regulatory considerations
- 3.14 Forecast assumptions & scenario analysis (Driven by Primary Research)
- 3.14.1 Base Case - key macro & industry variables driving CAGR
- 3.14.2 Optimistic Scenarios - Favorable Macro and Industry Tailwinds
- 3.14.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Latin America
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Company Tier Benchmarking
- 4.5.1 Tier Classification Criteria & Qualifying Thresholds
- 4.5.2 Tier Positioning Matrix by Revenue, Geography & Innovation
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans and funding
Chapter 5 Market Estimates & Forecast, By Component, 2022 - 2035 ($Bn)
- 5.1 Key trends
- 5.2 Solution
- 5.2.1 Asset lifecycle management
- 5.2.2 Predictive maintenance
- 5.2.3 Work order management
- 5.2.4 Labor management
- 5.2.5 Facility management
- 5.2.6 Inventory management
- 5.3 Service
- 5.3.1 Professional services
- 5.3.2 Managed services
Chapter 6 Market Estimates & Forecast, By Deployment Model, 2022 - 2035 ($Bn)
- 6.1 Key trends
- 6.2 On premises
- 6.3 Cloud
Chapter 7 Market Estimates & Forecast, By Organization Size, 2022 - 2035 ($Bn)
- 7.1 Key trends
- 7.2 Large enterprise
- 7.3 SME
Chapter 8 Market Estimates & Forecast, By Application, 2022 - 2035 ($Bn)
- 8.1 Key trends
- 8.2 Asset MRO
- 8.3 Linear assets
- 8.4 Non-linear assets
- 8.5 Field service management
Chapter 9 Market Estimates & Forecast By End use, 2022 - 2035 ($Bn)
- 9.1 Key trends
- 9.2 Energy & utilities
- 9.3 Manufacturing
- 9.4 IT & telecom
- 9.5 Healthcare
- 9.6 Oil & gas
- 9.7 Transportation & logistics
- 9.8 Government & public sector
- 9.9 Others
Chapter 10 Market Estimates & Forecast, By Region, 2022 - 2035 ($ Bn)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 US
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 UK
- 10.3.2 Germany
- 10.3.3 France
- 10.3.4 Italy
- 10.3.5 Spain
- 10.3.6 Belgium
- 10.3.7 Netherlands
- 10.3.8 Sweden
- 10.3.9 Russia
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 Singapore
- 10.4.6 South Korea
- 10.4.7 Vietnam
- 10.4.8 Indonesia
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 MEA
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global players
- 11.1.1 ABB
- 11.1.2 Aptean
- 11.1.3 AVEVA
- 11.1.4 CGI
- 11.1.5 IBM
- 11.1.6 IFS A
- 11.1.7 Infor
- 11.1.8 Oracle
- 11.1.9 Salesforce
- 11.1.10 SAP
- 11.2 Regional players
- 11.2.1 Asset Panda
- 11.2.2 AssetWorks
- 11.2.3 eMaint
- 11.2.4 EZOfficeInventory
- 11.2.5 Fleetio
- 11.2.6 Ramco Systems
- 11.2.7 Ultimo Software
- 11.3 Emerging players
- 11.3.1 KloudGin
- 11.3.2 Maintenance Connection
- 11.3.3 UpKeep

 企業資產管理市場-2026-2032年全球市場預測
 企業資產管理市場:按產業、解決方案、服務和地區分類
 全球企業資產管理市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026年全球企業資產管理(EAM)市場報告2026年全球企業資產管理市場報告
 企業資產管理市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、部署類型、最終用戶、模組及功能分類
 企業資產管理市場 - 全球產業規模、佔有率、趨勢、機會及預測(按組件、組織規模、部署模式、應用、產業垂直領域、地區和競爭格局分類,2021-2031 年)全球企業資產管理市場:市場規模、佔有率、成長率、產業分析、依類型、應用和地區劃分的分析及預測(2026-2034年)企業資產管理工具市場:2026-2032年全球預測(依組件、部署類型、組織規模及產業垂直領域分類)
 企業資產管理系統市場規模、佔有率和成長分析(按產品、應用、部署模式、組織規模、垂直產業和地區分類)-2026-2033年產業預測