

 |
市場調查報告書
商品編碼
2038329
類腦運算處理器市場機會、成長要素、產業趨勢分析及2026-2035年預測Brain-Inspired Computing Processor Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025 年全球類腦運算處理器市場價值為 300 萬美元,預計到 2035 年將達到 5,380 萬美元,年複合成長率為 33.7%。
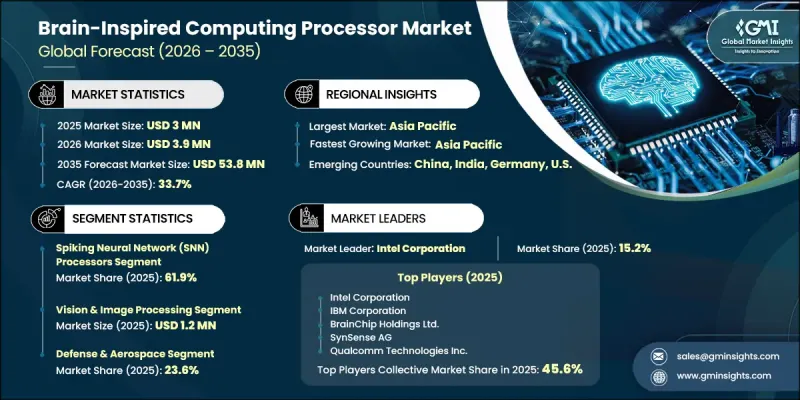
由於人工智慧 (AI) 工作負載對降低功耗的日益重視以及智慧部署越來越靠近資料來源,類腦運算處理器產業正蓬勃發展。對自適應和自主運算系統的需求不斷成長,加上神經形態晶片設計和學習框架的持續進步,進一步加速了市場擴張。此外,需要即時、低延遲處理能力的事件驅動型感測技術的日益普及,也提升了這些處理器的重要性。隨著運算範式向效率和響應速度的轉變,類腦架構正成為下一代 AI 系統的關鍵基礎,它支援在各種應用中的可擴展部署,同時滿足效能和功耗方面的限制。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 300萬美元 |
| 預計金額 | 5380萬美元 |
| 複合年成長率 | 33.7% |
受大規模運算環境中人工智慧 (AI) 運作所帶來的能源需求激增的驅動,類腦運算處理器市場正在蓬勃發展。各組織機構正加速向邊緣運算和設備端智慧轉型,以最大限度地降低延遲、減少資料傳輸量並提高營運效率。在這一演進過程中,企業優先考慮超低功耗和即時回應能力,這提升了神經形態技術的商業性可行性。架構設計的進步以及與事件驅動型感知系統的緊密成顯著提高了系統整體效率,從而加速了其在高級 AI 應用場景中的普及。
預計到2025年,脈衝神經網路處理器市佔率將達到61.9%,這主要得益於早期神經形態實作中對節能型、事件驅動型運算框架日益成長的需求。這些處理器因其低功耗和模擬生物神經元行為的能力而被廣泛應用於即時處理任務和邊緣智慧應用。試驗計畫和商業邊緣人工智慧解決方案中日益成長的應用進一步鞏固了該領域的領先地位。
預計到2025年,視覺和影像處理領域的市場規模將達到120萬美元,這主要得益於需要連續感知和快速資料解讀的應用領域對相關技術的日益普及。這些處理器因其能夠快速響應並高效處理視覺資料流而備受關注。它們在處理複雜視覺工作負載方面的卓越性能,正在推動先進感測和成像系統對這類處理器的需求不斷成長。
預計到2025年,北美類腦運算處理器市佔率將達到31.4%,主要得益於先進人工智慧研發的大力投入以及邊緣運算技術的早期應用。該地區擁有強大的技術開發商、研究機構和系統整合商生態系統,致力於部署節能型即時人工智慧解決方案。此外,公共和私營部門對半導體創新和先進運算基礎設施的持續支持也進一步推動了該地區的市場成長。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章業界考察
- 生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 對節能型人工智慧處理的需求日益成長
- 邊緣運算和設備端智慧的快速發展
- 自主自適應系統的應用日益普及
- 神經形態演算法和硬體架構的進展
- 與事件驅動型和仿生感測器整合方面的進展
- 產業潛在風險與挑戰
- 開發神經形態硬體的複雜性和成本都很高。
- 標準化進展有限,導致與現有人工智慧生態系統的兼容性較低。
- 市場機遇
- 在連續運作的工業和基礎設施系統中採用類腦處理器
- 將類腦運算擴展到國防、航太和關鍵任務應用領域。
- 促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 波特五力分析
- PESTEL 分析
- 科技與創新趨勢
- 當前技術趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要公司的競爭標竿分析
- 財務績效比較
- 銷售量
- 利潤率
- 研究與開發
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 業務拓展與投資策略
- 數位轉型計劃
- 新興/新創競爭對手的發展趨勢
第5章 市場估價與預測:依建築類型分類,2022-2035年
- 間諜神經網路(SNN)處理器
- 混合神經形態加速器
第6章 市場估計與預測:依應用領域分類,2022-2035年
- 視覺和影像處理
- 語音和語音處理
- 感測器融合與邊緣分析
- 機器人與自主系統
第7章 市場估計與預測:依最終用戶產業分類,2022-2035年
- 家用電子產品
- 汽車和交通運輸
- 工業自動化和製造
- 醫療保健和醫療設備
- 國防/航太
- 溝通
- 其他
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 俄羅斯
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
第9章:公司簡介
- 全球主要公司
- Intel Corporation
- IBM Corporation
- BrainChip Holdings Ltd.
- SynSense AG
- Qualcomm Technologies Inc.
- 按地區分類的主要公司
- 北美洲
- Hewlett Packard Enterprise
- Applied Brain Research
- General Vision Inc.
- HRL Laboratories
- Vicarious FPC
- 亞太地區
- Samsung Electronics
- SK Hynix
- 歐洲
- GrAI Matter Labs
- CEA-Leti
- Innatera Nanosystems
- 北美洲
The Global Brain-Inspired Computing Processor Market was valued at USD 3 million in 2025 and is estimated to grow at a CAGR of 33.7% to reach USD 53.8 million by 2035.
The brain-inspired computing processor industry is gaining momentum due to rising emphasis on lowering energy consumption in artificial intelligence workloads and increasing deployment of intelligence closer to data sources. The growing need for adaptive and autonomous computing systems, along with continuous advancements in neuromorphic chip design and learning frameworks, is further accelerating market expansion. In addition, the increasing adoption of event-driven sensing technologies that demand real-time and low-latency processing capabilities is strengthening the relevance of these processors. As computing paradigms shift toward efficiency and responsiveness, brain-inspired architectures are emerging as a key enabler for next-generation AI systems, supporting scalable deployment across diverse applications while addressing performance and power constraints.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3 Million |
| Forecast Value | $53.8 Million |
| CAGR | 33.7% |
The brain-inspired computing processor market is driven by the surge in energy demands associated with artificial intelligence operations in large-scale computing environments. Organizations are increasingly transitioning toward edge-based and on-device intelligence to minimize latency, reduce data transfer, and improve operational efficiency. During this evolution, companies have prioritized ultra-low power consumption and real-time responsiveness, which has enhanced the commercial viability of neuromorphic technologies. Advancements in architecture design and tighter integration with event-based sensing systems have significantly improved overall system efficiency, thereby accelerating adoption across advanced AI use cases.
The spiking neural network processors segment accounted for 61.9% share in 2025, supported by the growing preference for energy-efficient and event-driven computing frameworks in early neuromorphic implementations. These processors are widely utilized for real-time processing tasks and edge intelligence applications due to their low power requirements and ability to mimic biological neural behavior. Increasing deployment in pilot programs and commercial edge AI solutions continues to reinforce the segment's dominant position.
The vision and image processing segment reached USD 1.2 million in 2025, driven by rising adoption in applications requiring continuous perception and rapid data interpretation. These processors are gaining traction due to their ability to deliver fast response times and energy-efficient processing of visual data streams. Their effectiveness in handling complex visual workloads supports growing demand across advanced sensing and imaging systems.
North America Brain-Inspired Computing Processor Market accounted for 31.4% share in 2025, driven by strong investment in advanced artificial intelligence research and early adoption of edge computing technologies. The region benefits from a robust ecosystem of technology developers, research institutions, and system integrators focused on deploying energy-efficient and real-time AI solutions. Increasing support from both public and private sectors for semiconductor innovation and advanced computing infrastructure is further strengthening regional market growth.
Prominent players operating in the Global Brain-Inspired Computing Processor Industry include Intel Corporation, IBM Corporation, BrainChip Holdings Ltd., SynSense AG, Innatera Nanosystems, Qualcomm Technologies Inc., Samsung Electronics, Hewlett Packard Enterprise, Applied Brain Research, General Vision Inc., GrAI Matter Labs, HRL Laboratories, CEA-Leti, SK Hynix, and Vicarious FPC. Companies operating in the Global Brain-Inspired Computing Processor Market are focusing on strategic collaborations, research partnerships, and technology innovation to strengthen their competitive positioning. They are investing heavily in neuromorphic chip development, enhancing energy efficiency, and improving real-time processing capabilities to meet evolving AI demands. Firms are also prioritizing integration with edge computing platforms and event-driven sensing systems to expand application areas. In addition, partnerships with research institutions and semiconductor manufacturers enable faster commercialization and scaling of advanced architectures.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Architecture type trends
- 2.2.2 Application trends
- 2.2.3 End-user industry trends
- 2.2.4 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rising demand for energy-efficient AI processing
- 3.2.1.2 Rapid expansion of edge and on-device intelligence
- 3.2.1.3 Increasing adoption of autonomous and adaptive systems
- 3.2.1.4 Advancements in neuromorphic algorithms and hardware architectures
- 3.2.1.5 Growing integration with event-based and bio-inspired sensors
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High development complexity and cost of neuromorphic hardware
- 3.2.2.2 Limited standardization and compatibility with existing AI ecosystems
- 3.2.3 Market opportunities
- 3.2.3.1 Adoption of brain-inspired processors in continuously operating industrial and infrastructure systems
- 3.2.3.2 Expansion of brain-inspired computing into defense, aerospace, and mission-critical applications
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Architecture Type, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Spiking neural network (SNN) processors
- 5.3 Hybrid neuromorphic accelerators
Chapter 6 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Vision & image processing
- 6.3 Audio & speech processing
- 6.4 Sensor fusion & edge analytics
- 6.5 Robotics & autonomous systems
Chapter 7 Market Estimates and Forecast, By End-User Industry, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Consumer electronics
- 7.3 Automotive & transportation
- 7.4 Industrial automation & manufacturing
- 7.5 Healthcare & medical devices
- 7.6 Defense & aerospace
- 7.7 Telecommunications
- 7.8 Others
Chapter 8 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Russia
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.6 Middle East and Africa
- 8.6.1 South Africa
- 8.6.2 Saudi Arabia
- 8.6.3 UAE
Chapter 9 Company Profiles
- 9.1 Global Key Players
- 9.1.1 Intel Corporation
- 9.1.2 IBM Corporation
- 9.1.3 BrainChip Holdings Ltd.
- 9.1.4 SynSense AG
- 9.1.5 Qualcomm Technologies Inc.
- 9.2 Regional key players
- 9.2.1 North America
- 9.2.1.1 Hewlett Packard Enterprise
- 9.2.1.2 Applied Brain Research
- 9.2.1.3 General Vision Inc.
- 9.2.1.4 HRL Laboratories
- 9.2.1.5 Vicarious FPC
- 9.2.2 Asia Pacific
- 9.2.2.1 Samsung Electronics
- 9.2.2.2 SK Hynix
- 9.2.3 Europe
- 9.2.3.1 GrAI Matter Labs
- 9.2.3.2 CEA-Leti
- 9.2.3.3 Innatera Nanosystems
- 9.2.1 North America

 片上共用記憶體市場:全球市場預測,2026-2032年80MHz工業微控制器市場:全球市場預測,2026-2032年人工智慧工業微控制器市場:全球市場預測,2026-2032年
 ARM(進階精簡指令集電腦)微控制器全球市場報告(2026年)2026年全球金屬氧化物半導體(MOS)微控制器(MPU、MCU、DSP)市場報告
 嵌入式處理器市場規模、佔有率和成長分析:按處理器類型、位元架構、核心類型、連接方式、功耗、應用、最終用戶產業和地區分類-2026-2033年產業預測
 嵌入式處理器市場規模、佔有率、趨勢和預測:按類型、位元深度、應用和地區分類,2026-2034 年嵌入式處理器市場:依處理器類型、架構、核心數、效能等級、產業分類,全球預測(2026-2032年)馬達專用MCU市場(依馬達類型、拓樸結構、封裝、安裝方式、應用及通路分類),全球預測(2026-2032年)2026年全球嵌入式處理器市場報告