


 |
市場調查報告書
商品編碼
2027595
氖氣市場機會、成長要素、產業趨勢分析及2026-2035年預測Neon Gas Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025年全球氖氣市場規模預估為286億美元,預計2035年將以6%的複合年成長率成長至522億美元。
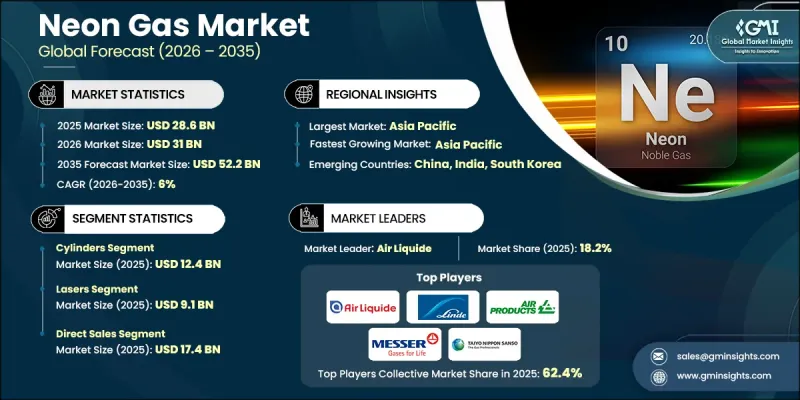
氖是一種惰性氣體,主要透過低溫分離液態空氣提取,因其化學惰性和獨特的螢光而備受青睞。即使在極端條件下,氖也能保持穩定,這使其成為眾多工業領域不可或缺的材料,包括電子製造、雷射技術和商業標誌。氖氣鮮豔的橘子紅色螢光,加上其惰性,使其成為精密應用的理想選擇。先進的低溫蒸餾和膜分離等生產技術的進步,提高了氖的純度並降低了成本。這些技術進步促使氖在半導體製造、高精度雷射應用和其他先進工業流程中得到更廣泛的應用,推動其在許多需要可靠、高品質材料的領域中得到廣泛應用。電子、工業和商業用戶日益成長的需求,持續推動全球市場的擴張。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 286億美元 |
| 預計金額 | 522億美元 |
| 複合年成長率 | 6% |
預計到2025年,鋼瓶市場規模將達到124億美元。由於其便攜性,鋼瓶為小規模工業、實驗室和科研需求提供了便捷的解決方案。鋼瓶設計的技術進步,包括耐高壓和耐用材料,確保了氖氣的安全處理和運輸。此外,大容量和微容量鋼瓶解決方案也已出現,可為需要持續供應氖氣的大規模半導體工廠和製造流程提供不間斷的供應。
預計到2025年,雷射產業規模將達到91億美元。氖氣在雷射技術中的應用日益廣泛,用於實現精確波長、最佳化光束品質並確保穩定輸出。商業標牌和節能照明等領域的應用不斷拓展,進一步推動了市場需求。電子製造商依靠高純度氖氣來維持微影術刻製程中半導體生產的良率,而測繪和低溫應用則需要穩定、高品質的氣體來滿足嚴格的冷卻效率性能標準。
預計到2025年,北美氖氣市場規模將達到75億美元,主要受半導體產業對高純度氣體的需求以及供應鏈多元化努力的推動。國內對精煉廠和生產設施的投資也支撐著市場成長。由於政府扶持計畫促進了半導體製造業的發展,以及先進雷射系統在醫療、工業和精密製造領域的應用日益廣泛,美國市場需求尤其強勁。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章業界考察
- 生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 市場機遇
- 成長潛力分析
- 監理情勢
- 波特五力分析
- PESTEL 分析
- 價格趨勢
- 按地區
- 未來市場趨勢
- 科技與創新趨勢
- 當前技術趨勢
- 新興技術
- 專利趨勢
- 貿易統計(HS編碼)
- 主要進口國
- 主要出口國
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 環保意識的舉措
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 按地區
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係與合作
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依供應類型分類,2022-2035年
- 圓柱
- 散裝和微散裝
- 桶罐
- 現場
第6章 市場估計與預測:依應用領域分類,2022-2035年
- 雷射
- 標識和照明
- 霓虹燈
- 建築霓虹燈照明
- 霓虹藝術和裝飾照明
- 電子和半導體行業
- 電漿顯示器(PDP)
- 氖指示燈
- 氣體雷射
- 低溫應用
- 超低溫冷凍
- 低溫泵浦系統
- 其他
第7章 市場估價與預測:依通路分類,2022-2035年
- 直銷
- 銷售代理商和批發商
- 線上零售
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲地區
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 亞太其他地區
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲地區
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 阿拉伯聯合大公國
- 其他中東和非洲地區
第9章:公司簡介
- Air Liquide
- Linde PLC
- Messer Group GmbH
- Matheson Tri-Gas, Inc
- Taiyo Nippon Sanso Corporation
- Air Products*Iceblick Ltd
- Airgas, Inc.
- Ingas
- Proton Gases
- Universal Industrial Gases, Inc
- Electronic Fluorocarbons LLC
The Global Neon Gas Market was valued at USD 28.6 billion in 2025 and is estimated to grow at a CAGR of 6% to reach USD 52.2 billion by 2035.
Neon is a noble gas extracted primarily through cryogenic separation of liquid air and is highly valued for its chemical inertness and unique luminescent properties. Its ability to maintain stability under extreme conditions makes it indispensable in multiple industrial sectors, including electronics manufacturing, laser technology, and commercial signage. The gas's bright orange-red glow, combined with its non-reactive nature, makes it ideal for precision applications. Advancements in production methods, such as enhanced cryogenic distillation and membrane separation, have increased purity levels while reducing costs. These technological improvements have elevated neon's use in semiconductor fabrication, high-precision laser applications, and other advanced industrial processes, supporting broader adoption across sectors requiring reliable, high-quality materials. Growing demand from electronics, industrial, and commercial users continues to drive market expansion globally.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $28.6 Billion |
| Forecast Value | $52.2 Billion |
| CAGR | 6% |
In 2025, the cylinders segment reached USD 12.4 billion. Cylinders are favored for their portability, offering convenient solutions for small-scale industrial, laboratory, and research needs. Technological upgrades in cylinder design, including high-pressure, durable materials, have ensured safer handling and transportation of neon gas. Bulk and micro-bulk solutions have also emerged, providing uninterrupted supply to large-scale semiconductor facilities and manufacturing operations that require continuous neon availability for production.
The lasers segment reached USD 9.1 billion in 2025. Neon gas is increasingly used in laser technology to achieve precise wavelengths, optimize beam quality, and ensure consistent output. Its growing application in commercial signage and energy-efficient lighting has strengthened demand further. Electronics manufacturers rely on high-purity neon to maintain semiconductor production yields during photolithography, while research and cryogenic applications depend on stable, high-quality gas to meet strict performance standards for cooling efficiency.
North America Neon Gas Market reached USD 7.5 billion in 2025, driven by the semiconductor sector's need for high-purity gases and initiatives to diversify supply chains. Domestic investments in purification plants and production facilities are supporting market growth. In the U.S., demand is particularly strong due to increased semiconductor fabrication under government-backed programs and higher utilization of advanced laser systems for medical, industrial, and precision manufacturing applications.
Key players in the Global Neon Gas Market include Linde PLC, Messer Group GmbH, Air Products, Taiyo Nippon Sanso Corporation, Air Liquide, Matheson Tri-Gas, Inc., Iceblick Ltd, Airgas, Inc., Proton Gases, Ingas, Universal Industrial Gases, Inc., and Electronic Fluorocarbons LLC. Companies in the neon gas market strengthen their presence by investing heavily in R&D to improve purification and extraction technologies, ensuring higher gas purity and cost efficiency. Strategic partnerships with semiconductor and laser manufacturers allow firms to secure long-term contracts and consistent demand. Expanding production capacities, including bulk and cylinder supply chains, supports growing global requirements. Marketing efforts focus on highlighting reliability, stability, and versatility for industrial applications. Companies also pursue geographic expansion, targeting emerging markets, and implement advanced logistics solutions to ensure the timely delivery of high-purity neon, creating a competitive edge and reinforcing their market foothold.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Product
- 2.2.2 Application
- 2.2.3 Source
- 2.2.4 Regional
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls and challenges
- 3.2.3 Market opportunities
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Price trends
- 3.7.1 By region
- 3.8 Future market trends
- 3.9 Technology and Innovation landscape
- 3.9.1 Current technological trends
- 3.9.2 Emerging technologies
- 3.10 Patent Landscape
- 3.11 Trade statistics (HS code)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New Product Launches
- 4.5.4 Expansion Plans
Chapter 5 Market Estimates and Forecast, By Supply Mode, 2022-2035 (USD Billion) (Kilo Tons)
- 5.1 Key trends
- 5.2 Cylinders
- 5.3 Bulk & micro bulk
- 5.4 Drum tanks
- 5.5 On-site
Chapter 6 Market Estimates and Forecast, By Application, 2022-2035 (USD Billion) (Kilo Tons)
- 6.1 Key trends
- 6.2 Lasers
- 6.3 Signage and lighting
- 6.3.1 Neon signs
- 6.3.2 Neon lighting for architecture
- 6.3.3 Neon art and decorative lighting
- 6.4 Electronics and semiconductor industry
- 6.4.1 Plasma display panels (pdps)
- 6.4.2 Neon indicator lamps
- 6.4.3 Gas lasers
- 6.5 Cryogenic applications
- 6.5.1 Cryogenic refrigeration
- 6.5.2 Cryogenic pumping systems
- 6.6 Others
Chapter 7 Market Estimates and Forecast, By Distribution channel, 2022-2035 (USD Billion) (Kilo Tons)
- 7.1 Key trends
- 7.2 Direct sales
- 7.3 Distributors and wholesalers
- 7.4 Online retail
Chapter 8 Market Estimates and Forecast, By Region, 2022-2035 (USD Billion) (Kilo Tons)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Rest of Europe
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Rest of Asia Pacific
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.5.4 Rest of Latin America
- 8.6 Middle East and Africa
- 8.6.1 Saudi Arabia
- 8.6.2 South Africa
- 8.6.3 UAE
- 8.6.4 Rest of Middle East and Africa
Chapter 9 Company Profiles
- 9.1 Air Liquide
- 9.2 Linde PLC
- 9.3 Messer Group GmbH
- 9.4 Matheson Tri-Gas, Inc
- 9.5 Taiyo Nippon Sanso Corporation
- 9.6 Air Products * Iceblick Ltd
- 9.7 Airgas, Inc.
- 9.8 Ingas
- 9.9 Proton Gases
- 9.10 Universal Industrial Gases, Inc
- 9.11 Electronic Fluorocarbons LLC

 氖氣市場規模、佔有率和趨勢分析報告:按等級、應用、地區和細分市場預測(2026-2033 年)
 氖氣市場:依供應類型、應用、通路和地區分類螢光塗料市場:依產品類型、應用、最終用戶、通路及地區分類。霓虹燈市場:依材料和地區分類
 氖氣市場規模、佔有率和成長分析(按純度、來源、包裝類型、應用、最終用途產業和地區分類)-2026-2033年產業預測
 霓虹燈市場按產品類型、分銷管道、應用和最終用戶產業分類-2026年至2032年全球預測
 氖氣:全球市場佔有率和排名、總收入和需求預測(2025-2031年)
 全球氖氣市場
 2030 年霓虹氣市場預測:按純度、供應類型、應用、最終用戶和地區進行的全球分析