

 |
市場調查報告書
商品編碼
2027467
冬季運動器材市場商機、成長要素、產業趨勢分析及2026-2035年預測。Winter Sports Equipment Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025年全球冬季運動器材市場價值為151億美元,預計2035年將達到199億美元,年複合成長率為2.8%。
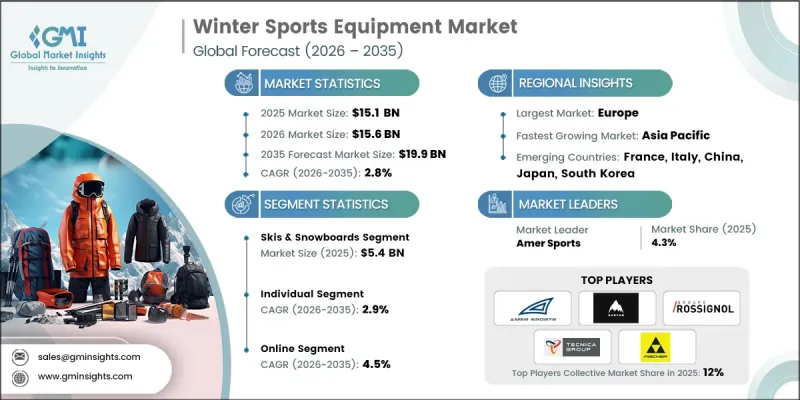
這一上升趨勢反映了消費者對冬季休閒活動日益成長的興趣,以及對注重性能和安全的專業裝備需求的增加。成熟地區和新興地區參與度的提高,以及冬季運動基礎設施的不斷完善,進一步推動了需求成長。材料和產品設計的持續創新提升了裝備的耐用性、效率和使用者體驗,使其對更廣泛的消費者群體更具吸引力。此外,扶持政策和基礎設施投資透過促進旅遊業發展和體育運動參與,加速了產業成長動能。可支配收入的增加、積極生活方式意識的增強以及裝備獲取管道的改善,也推動了市場成長,使該行業走上了長期穩步發展的道路。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 初始市場規模 | 151億美元 |
| 預測金額 | 199億美元 |
| 複合年成長率 | 2.8% |
預計到2025年,滑雪和單板滑雪市場規模將達到54億美元,並在2035年之前保持3.2%的複合年成長率。冬季休閒活動的日益普及和產品性能的不斷提升,推動了該市場持續成長。製造商越來越注重永續的生產方式,從而促進了環保裝備的研發。這種轉變正在影響消費者的購買行為,並豐富產品系列。
預計到2025年,個人用戶市佔率將達到87%,並在2026年至2035年間以2.9%的複合年成長率成長。這一細分市場的成長主要得益於消費者對休閒運動和健康生活方式日益成長的興趣。可支配收入的增加以及人們對健身益處的認知不斷提高,正在推動個人對冬季運動裝備的投資。此外,旅遊目的地的擴張和價格較親民的裝備的日益普及,也進一步促進了這個細分市場的成長。
預計到2025年,美國冬季運動裝備市場將佔據74%的市場佔有率,市場規模將達到37億美元。美國冬季運動參與率高以及人們對戶外休閒的興趣日益濃厚,是推動美國冬季運動裝備市場擴張的主要因素。完善的基礎設施和穩定的遊客數量也持續推動全部區域對冬季運動裝備的旺盛需求。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章業界考察
- 生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 機會
- 供應鏈分析
- 成長潛力分析
- 未來市場趨勢
- 科技與創新趨勢
- 當前技術趨勢
- 新興技術
- 價格分析(基於初步調查)
- 對過去價格趨勢的分析(基於初步研究)
- 根據業務類型分類的定價策略(高階/價值/成本加成)(基於初步調查)
- 法律規範
- 標準和認證
- 環境法規
- 出口和進口限制
- 貿易數據分析(基於初步調查)
- 進出口數量和價值趨勢(基於初步調查)
- 主要貿易路線及關稅的影響(基於初步調查)
- 人工智慧和生成式人工智慧對市場的影響
- 人工智慧正在改變傳統的經營模式。
- 按客戶群分類的生成式人工智慧用例和實施藍圖
- 風險、限制和監管考量
- 整合人工智慧驅動的智慧家庭生態系統
- 波特五力分析
- PESTEL 分析
- 消費行為分析
- 購買模式
- 偏好分析
- 消費行為的區域差異
- 電子商務對購買決策的影響
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係與合作
- 新產品發布
- 業務拓展計劃
第5章 市場估算與預測:依產品類型分類,2022-2035年
- 滑雪和單板滑雪
- 雪鞋和固定器
- 滑雪靴
- 滑雪靴
- 溜冰
- 滑雪板固定器
- 其他物品(滑雪板固定器等)
- 護具和頭盔
- 頭盔
- 風鏡
- 護具(膝蓋和背部)
- 面罩
- 配件及其他設備
- 滑雪杖
- 手套和連指手套
- 維護用品
- 其他(雪橇、雪橇車、雪鞋等)
第6章 市場估價與預測:依運動項目分類,2022-2035年
- 滑雪
- 單板滑雪
- 冰上曲棍球
- 花式溜冰
- 其他活動(滑雪橇、雪圈等)
第7章 市場估計與預測:依消費者區隔市場分類,2022-2035年
- 男性
- 女士
- 男女通用的
第8章 市場估算與預測:依價格區間分類,2022-2035年
- 低價位
- 中價位
- 高的
第9章 市場估價與預測:依最終用戶分類,2022-2035年
- 個人
- 專業的
- 競技滑雪運動員
- 講師
- 救援專家
- 機構
第10章 市場估價與預測:依通路分類,2022-2035年
- 線上
- 電子商務
- 企業網站
- 離線
- 超級市場/大賣場
- 專業零售店
- 其他(例如獨立經營零售商店)
第11章 市場估價與預測:按地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 荷蘭
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲(MEA)
- 南非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
第12章:公司簡介
- Amer Sports
- Burton Snowboards
- CAPiTA Snowboards
- DPS Skis
- Edea Skates
- Elan
- Fischer Sports
- Graf Skates
- Kessler
- Mervin Manufacturing
- Never Summer
- Riedell Skates
- Rossignol Group
- Tecnica Group
- Volkl Sports
The Global Winter Sports Equipment Market was valued at USD 15.1 billion in 2025 and is estimated to grow at a CAGR of 2.8% to reach USD 19.9 billion by 2035.
This upward trajectory reflects growing consumer enthusiasm for winter-based recreational activities and an increasing preference for specialized gear tailored to performance and safety. Demand is further supported by rising participation levels across established and developing regions, alongside broader access to winter sports infrastructure. Continuous innovation in materials and product engineering is enhancing durability, efficiency, and user experience, making equipment more appealing to a wide consumer base. Additionally, supportive policies and infrastructure investments are accelerating industry momentum by encouraging tourism and sports participation. Expanding disposable incomes, increasing awareness of active lifestyles, and greater accessibility to equipment are also reinforcing market growth, positioning the industry for consistent long-term development.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $15.1 Billion |
| Forecast Value | $19.9 Billion |
| CAGR | 2.8% |
The skis and snowboards segment accounted for USD 5.4 billion in 2025 and is projected to grow at a CAGR of 3.2% throughout 2035. This segment continues to gain traction due to rising engagement in winter recreational activities and ongoing advancements in product performance. Manufacturers are increasingly focusing on sustainable production practices, which is encouraging the development of environmentally responsible equipment options. This shift is influencing purchasing behavior and expanding product portfolios across the category.
The individual user category held an 87% share in 2025 and is expected to grow at a CAGR of 2.9% from 2026 to 2035. Growth in this segment is being driven by increased consumer interest in recreational sports and wellness-focused lifestyles. Higher disposable incomes and improved awareness of fitness benefits are motivating individuals to invest in winter sports gear. Additionally, the expansion of tourism destinations and the availability of more affordable equipment options are further supporting segment growth.
United States Winter Sports Equipment Market accounted for 74% share and generated USD 3.7 billion in 2025. Market expansion in the country is supported by strong participation rates in winter activities and the growing appeal of outdoor recreation. Well-developed infrastructure and consistent tourist inflows continue to contribute to sustained demand for winter sports equipment across the region.
Key companies operating in the Global Winter Sports Equipment Market include Amer Sports, Burton Snowboards, CAPiTA Snowboards, DPS Skis, Edea Skates, Elan, Fischer Sports, Graf Skates, Kessler, Mervin Manufacturing, Never Summer, Riedell Skates, Rossignol Group, Tecnica Group, and Volkl Sports. Companies in the Global Winter Sports Equipment Market are strengthening their market position through a combination of innovation, strategic partnerships, and geographic expansion. Many players are investing heavily in research and development to introduce high-performance and sustainable products that align with evolving consumer preferences. Collaborations with sports organizations and athletes are leveraged to enhance brand visibility and credibility. Firms are also expanding their distribution networks through both online and offline channels to reach a broader customer base. In addition, mergers, acquisitions, and partnerships enable companies to diversify product portfolios and improve operational capabilities. Emphasis on eco-friendly materials and advanced manufacturing techniques is further helping brands differentiate themselves in a competitive landscape while addressing regulatory and consumer sustainability expectations.
Table of Contents
Chapter 1 Methodology and scope
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation for any one approach
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional trends
- 2.2.2 Equipment type trends
- 2.2.3 Sports type trends
- 2.2.4 Consumer group trends
- 2.2.5 Price range trends
- 2.2.6 End user trends
- 2.2.7 Distribution channel trends
Chapter 3 Industry insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls & challenges
- 3.2.3 Opportunities
- 3.3 Supply chain analysis
- 3.4 Growth potential analysis
- 3.5 Future market trends
- 3.6 Technology and innovation landscape
- 3.6.1 Current technological trends
- 3.6.2 Emerging technologies
- 3.7 Pricing analysis (Driven by Primary Research)
- 3.8 Historical price trend analysis (Driven by Primary Research)
- 3.9 Pricing strategy by player type (Premium / Value / Cost-plus) (Driven by Primary Research)
- 3.10 Regulatory framework
- 3.10.1 Standards and certifications
- 3.10.2 Environmental regulations
- 3.10.3 Import export regulations
- 3.11 Trade data analysis (Driven by Primary Research)
- 3.12 Import/export volume & value trends (Driven by Primary Research)
- 3.13 Key trade corridors & tariff impact (Driven by Primary Research)
- 3.14 Impact of AI & generative ai on the market
- 3.14.1 AI-driven disruption of traditional business models
- 3.14.2 GenAI use cases & adoption roadmap by customer segment
- 3.14.3 Risks, limitations & regulatory considerations
- 3.14.4 AI-enabled smart home ecosystem integration
- 3.15 Porter's five forces analysis
- 3.16 PESTEL analysis
- 3.17 Consumer behavior analysis
- 3.17.1 Purchasing patterns
- 3.17.2 Preference analysis
- 3.17.3 Regional variations in consumer behavior
- 3.17.4 Impact of e-commerce on buying decisions
Chapter 4 Competitive landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 Latin America
- 4.2.5 MEA
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New product launches
- 4.6.4 Expansion plans
Chapter 5 Market Estimates & Forecast, By Equipment Type, 2022 - 2035 ($Billion, Thousand Units)
- 5.1 Key trends
- 5.2 Skis & snowboards
- 5.3 Boots & bindings
- 5.3.1 Ski boots
- 5.3.2 Snowboard boots
- 5.3.3 Ice skates
- 5.3.4 Ski bindings
- 5.3.5 Others (snowboard bindings etc.)
- 5.4 Protective gear & helmets
- 5.4.1 Helmets
- 5.4.2 Goggles
- 5.4.3 Pads (Knee, back protectors)
- 5.4.4 Face guards
- 5.5 Accessories & other equipment
- 5.5.1 Ski poles
- 5.5.2 Gloves & mittens
- 5.5.3 Maintenance equipment
- 5.5.4 Others (sleds, toboggans, snowshoes etc.)
Chapter 6 Market Estimates & Forecast, By Sports Type, 2022 - 2035 ($Billion, Thousand Units)
- 6.1 Key trends
- 6.2 Skiing
- 6.3 Snowboarding
- 6.4 Ice hockey
- 6.5 Figure skating
- 6.6 Other (sledding, snow tubing etc.)
Chapter 7 Market Estimates & Forecast, By Consumer Group, 2022 - 2035 ($Billion, Thousand Units)
- 7.1 Key trends
- 7.2 Men
- 7.3 Women
- 7.4 Unisex
Chapter 8 Market Estimates & Forecast, By Price Range, 2022 - 2035 ($Billion, Thousand Units)
- 8.1 Key trends
- 8.2 Low
- 8.3 Medium
- 8.4 High
Chapter 9 Market Estimates & Forecast, By End User, 2022 - 2035 ($Billion, Thousand Units)
- 9.1 Key trends
- 9.2 Individual
- 9.3 Professional
- 9.3.1 Competitive athletes/skiers
- 9.3.2 Instructors
- 9.3.3 Rescue professionals
- 9.3.4 Institutions
Chapter 10 Market Estimates & Forecast, By Distribution Channel, 2022 - 2035 ($Billion, Thousand Units)
- 10.1 Key trends
- 10.2 Online
- 10.2.1 E-commerce
- 10.2.2 Company websites
- 10.3 Offline
- 10.3.1 Supermarkets/hypermarket
- 10.3.2 Specialty retail stores
- 10.3.3 Others (independent retailer etc.)
Chapter 11 Market Estimates & Forecast, By Region, 2022 - 2035 ($Billion, Thousand Units)
- 11.1 Key trends
- 11.2 North America
- 11.2.1 U.S.
- 11.2.2 Canada
- 11.3 Europe
- 11.3.1 Germany
- 11.3.2 UK
- 11.3.3 France
- 11.3.4 Spain
- 11.3.5 Italy
- 11.3.6 Netherlands
- 11.4 Asia Pacific
- 11.4.1 China
- 11.4.2 Japan
- 11.4.3 India
- 11.4.4 Australia
- 11.4.5 South Korea
- 11.5 Latin America
- 11.5.1 Brazil
- 11.5.2 Mexico
- 11.5.3 Argentina
- 11.6 MEA
- 11.6.1 South Africa
- 11.6.2 Saudi Arabia
- 11.6.3 UAE
Chapter 12 Company Profiles
- 12.1 Amer Sports
- 12.2 Burton Snowboards
- 12.3 CAPiTA Snowboards
- 12.4 DPS Skis
- 12.5 Edea Skates
- 12.6 Elan
- 12.7 Fischer Sports
- 12.8 Graf Skates
- 12.9 Kessler
- 12.10 Mervin Manufacturing
- 12.11 Never Summer
- 12.12 Riedell Skates
- 12.13 Rossignol Group
- 12.14 Tecnica Group
- 12.15 Volkl Sports

 分離式滑雪板固定器與冰爪市場:全球市場預測,2026-2032年分離板冰爪市場:2026-2032 年全球市場預測
 分離式雪茄盒市場規模、佔有率和成長分析:按裝訂類型、安裝方法、材料、最終用戶、分銷管道和地區分類-2026年至2033年產業預測
 冬季運動器材市場規模、佔有率、成長、全球產業分析、區域趨勢及2026年至2034年預測。冬季運動裝備市場:2026-2032年全球市場預測(依產品類型、防護裝備及配件、材料種類、設備類型、應用及通路分類)
 冬季運動器材市場報告:趨勢、預測及競爭分析(至2035年)
 冬季運動用品市場-全球產業規模、佔有率、趨勢、機會及預測(依產品類型、運動項目、銷售管道、地區及競爭格局分類,2021-2031年)
 全球冬季運動器材市場,市場規模研究與預測:按運動項目、器材類別、最終用戶、分銷管道和地區分類的預測(2025-2035 年)
 全球雪地Scooter市場