


 |
市場調查報告書
商品編碼
1913420
太空著陸器和探測車市場機會、成長促進因素、產業趨勢分析及預測(2026-2035)Space lander and Rover Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

全球太空登陸器和探測車市場預計到 2025 年價值 20 億美元,到 2035 年達到 50 億美元,年複合成長率為 9.7%。
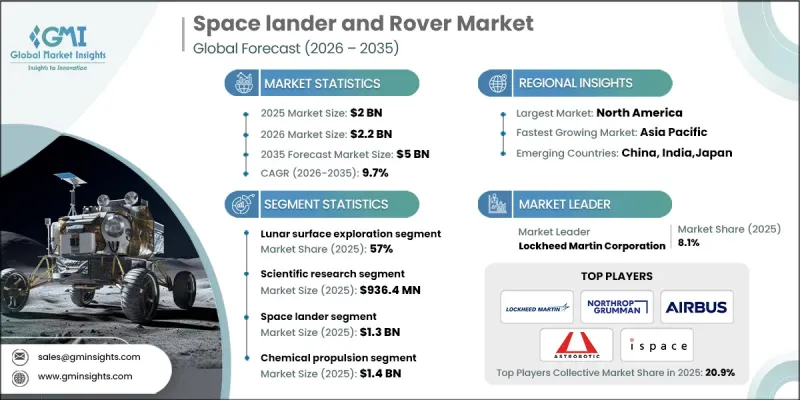
全球對行星探勘任務日益成長的興趣以及自主移動、導航和機器人系統的持續進步推動了這一成長。各國政府和私人機構正在增加對地外探勘目標的長期投入,從而推動了對先進地表探勘平台的需求。私部門參與度的提高正在加速創新週期,促進更輕、更強大、更經濟高效的登陸器和探測車的研發。機載智慧、耐久性和能源效率的技術進步進一步增強了市場動力。隨著探勘目標不再局限於短期任務,對能夠在惡劣環境下運作的可靠系統的需求與日俱增。這種不斷變化的市場格局正促使製造商開發適應性強的平台,以支援長期任務和未來的基礎設施建設,從而推動全球市場的穩定成長。
| 市場覆蓋範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測年份 | 2026-2035 |
| 起始金額 | 20億美元 |
| 預測金額 | 50億美元 |
| 複合年成長率 | 9.7% |
到2025年,月球探勘領域將佔據57%的市場。該領域受益於對能夠在惡劣地表環境下高效運作的自主系統日益成長的需求。製造商正優先開發先進的行動平台和資源利用技術,旨在支援持續的月球任務,同時保持成本效益和運作可靠性。
預計到2025年,科學研究領域的市場規模將達到9.364億美元。該領域的成長主要得益於對探勘任務投資的增加以及對行星表面精確科學數據日益成長的需求。製造商正致力於開發高精度測量儀器、可靠的資料收集系統和適應性強的任務架構,以滿足不斷變化的研究目標。
預計到 2025 年,北美太空登陸器和探測車市場將佔 48% 的佔有率。這個區域主導地位得益於強大的公共資金支持、與私人航太公司日益密切的合作,以及旨在提高任務表現和降低營運成本的自主技術的快速發展。
目錄
第1章調查方法和範圍
第2章執行摘要
第3章業界考察
- 產業生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段的附加價值
- 影響價值鏈的因素
- 中斷
- 產業影響因素
- 成長促進因素
- 全球對月球和火星探勘任務的興趣日益濃厚
- 自主導航和移動系統的技術進步
- 私部門對太空探勘技術的投資與擴張
- 政府為制定殖民月球和火星的長期計劃所做的努力
- 發展本土資源利用(ISRU)能力以進行太空探勘
- 產業潛在風險與挑戰
- 開發成本高且技術複雜
- 惡劣的太空環境導致任務失敗的風險
- 市場機遇
- 開發永續的太空住家周邊設施
- 自主探勘技術的進步
- 成長促進因素
- 成長潛力分析
- 監管環境
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 波特分析
- PESTEL 分析
- 科技與創新趨勢
- 當前技術趨勢
- 新興技術
- 新興經營模式
- 合規要求
- 國防預算分析
- 全球國防費用趨勢
- 區域國防預算分配
- 北美洲
- 歐洲
- 亞太地區
- 中東和非洲
- 拉丁美洲
- 主要國防現代化項目
- 預算預測(2026-2035 年)
- 對產業成長的影響
- 各國國防預算
- 國防預算按部門分配
- 人員
- 運作/維護
- 採購
- 研究與發展、測試與評估
- 基礎設施和建築
- 技術與創新
- 供應鏈韌性
- 地緣政治分析
- 勞動力分析
- 數位轉型
- 併購和策略聯盟
- 風險評估與管理
- 重大合約授予(2022-2025)
第4章 競爭情勢
- 介紹
- 公司市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要企業的競爭標竿分析
- 財務績效比較
- 收入
- 利潤率
- 研究與開發
- 產品系列比較
- 產品線豐富
- 科技
- 創新
- 地理分佈比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 重大進展
- 併購
- 夥伴關係與合作
- 技術進步
- 業務拓展與投資策略
- 永續發展計劃
- 數位轉型計劃
- 新興/Start-Ups競賽的趨勢
第5章 依任務類型分類的市場估算與預測(2022-2035 年)
- 月亮探勘
- 火星表面探勘
- 小行星和彗星探勘
第6章 依車輛類型分類的市場估計與預測(2022-2035 年)
- 太空著陸器
- 太空探測車
第7章 市場估計與預測:以推進方式分類(2022-2035 年)
- 化學推廣
- 電/離子推進
- 混合動力推進系統
第8章 市場估算與預測:依應用領域分類(2022-2035 年)
- 化學推廣
- 電/離子推進
- 混合動力推進系統
第9章 依最終用途分類的市場估算與預測(2022-2035 年)
- 政府和國防機構
- 太空探勘機構
- 民用航太公司
- 研究所
第10章 各地區市場估計與預測(2022-2035 年)
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 荷蘭
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
第11章 公司簡介
- 主要企業
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- NASA
- Roscosmos
- Airbus SE
- 主要企業
- 北美洲
- Blue Origin
- Canadian Space Agency
- 亞太地區
- ISRO
- Japan Aerospace Exploration Agency(JAXA)
- China Academy of Space Technology
- 歐洲
- European Space Agency
- Spacebit Technologies
- 北美洲
- 小眾公司/顛覆者
- Astrobotic Technology
- ispace, inc.
The Global Space lander and Rover Market was valued at USD 2 billion in 2025 and is estimated to grow at a CAGR of 9.7% to reach USD 5 billion by 2035.
Growth is supported by rising worldwide focus on planetary exploration missions and continuous progress in autonomous mobility, navigation, and robotic systems. Governments and private organizations are increasingly committing long-term funding toward off-Earth exploration goals, which is driving demand for advanced surface exploration platforms. Expanding private sector participation is accelerating innovation cycles, encouraging the development of lighter, more capable, and cost-efficient landers and rovers. Technological improvements in onboard intelligence, durability, and energy efficiency are further strengthening market momentum. As exploration ambitions extend beyond short-term missions, the need for reliable systems capable of operating in extreme environments continues to increase. This evolving landscape is pushing manufacturers to develop adaptable platforms that support extended missions and future infrastructure development, reinforcing steady growth across the global market.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $2 Billion |
| Forecast Value | $5 Billion |
| CAGR | 9.7% |
The lunar surface exploration segment accounted for 57% share in 2025. This segment benefits from the growing demand for autonomous systems capable of operating efficiently in harsh surface conditions. Manufacturers are prioritizing advanced mobility platforms and resource utilization technologies designed to support sustained lunar missions while maintaining cost efficiency and operational reliability.
The scientific research segment generated USD 936.4 million in 2025. Growth in this segment is driven by increased investment in exploration missions and the expanding need for accurate scientific data from planetary surfaces. Manufacturers are focusing on high-precision instruments, robust data collection systems, and adaptable mission architectures to meet evolving research objectives.
North America Space lander and Rover Market held a 48% share in 2025. Regional dominance is supported by strong public funding, increasing collaboration with private space companies, and rapid development of autonomous technologies aimed at improving mission performance and lowering operational expenses.
Key players operating in the Global Space lander and Rover Market include Lockheed Martin Corporation, Airbus SE, Northrop Grumman Corporation, Blue Origin, Roscosmos, ISRO, European Space Agency, Canadian Space Agency, Japan Aerospace Exploration Agency (JAXA), China Academy of Space Technology, Spacebit Technologies, Astrobotic Technology, ispace, inc., and NASA. Companies in the Global Space lander and Rover Market strengthen their competitive position through sustained investment in advanced robotics, autonomous navigation, and modular spacecraft design. Manufacturers focus on developing versatile platforms that can support multiple mission profiles while reducing overall system weight and complexity. Strategic collaboration with government agencies and private partners helps secure long-term project pipelines. Firms also prioritize durability and reliability to ensure performance in extreme extraterrestrial environments.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 3600 synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Mission type trends
- 2.2.2 Vehicle type trends
- 2.2.3 Propulsion type trends
- 2.2.4 Application trends
- 2.2.5 End use trends
- 2.2.6 Regional
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.4.1 Executive decision points
- 2.4.2 critical success factors
- 2.5 Future outlook and strategic recommendations
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Surging global interest in lunar and martian exploration missions
- 3.2.1.2 Technological advancements in autonomous navigation and mobility systems
- 3.2.1.3 Private sector investment and expansion in space exploration technologies
- 3.2.1.4 Governmental commitments to long-term lunar and mars colonization plans
- 3.2.1.5 Development of In-Situ resource utilization (isru) capabilities for space exploration
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High development costs and technological complexity
- 3.2.2.2 Risks of mission failures due to harsh extraterrestrial environments
- 3.2.3 Market opportunities
- 3.2.3.1 Development of sustainable space habitats
- 3.2.3.2 Advancements in autonomous technology for exploration
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Emerging business models
- 3.9 Compliance requirements
- 3.10 Defense Budget Analysis
- 3.11 Global Defense Spending Trends
- 3.12 Regional Defense Budget Allocation
- 3.12.1 North America
- 3.12.2 Europe
- 3.12.3 Asia Pacific
- 3.12.4 Middle East and Africa
- 3.12.5 Latin America
- 3.13 Key Defense Modernization Programs
- 3.14 Budget Forecast (2026-2035)
- 3.14.1 Impact on Industry Growth
- 3.14.2 Defense Budgets by Country
- 3.14.3 Defense Budget Allocation by Segment
- 3.14.3.1 Personnel
- 3.14.3.2 Operations and Maintenance
- 3.14.3.3 Procurement
- 3.14.3.4 Research, Development, Test and Evaluation
- 3.14.3.5 Infrastructure and Construction
- 3.14.3.6 Technology and Innovation
- 3.15 Supply Chain Resilience
- 3.16 Geopolitical Analysis
- 3.17 Workforce Analysis
- 3.18 Digital Transformation
- 3.19 Mergers, Acquisitions, and Strategic Partnerships Landscape
- 3.20 Risk Assessment and Management
- 3.21 Major Contract Awards (2022-2025)
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market Concentration Analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Sustainability initiatives
- 4.4.6 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Mission Type, 2022 - 2035 (USD Million)
- 5.1 Key trends
- 5.2 Lunar surface exploration
- 5.3 Mars surface exploration
- 5.4 Asteroids and comet exploration
Chapter 6 Market Estimates and Forecast, By Vehicle Type, 2022 - 2035 (USD Million)
- 6.1 Key trends
- 6.2 Space landers
- 6.3 Space rovers
Chapter 7 Market Estimates and Forecast, By Propulsion Type, 2022 - 2035 (USD Million)
- 7.1 Key trends
- 7.2 Chemical propulsion
- 7.3 Electric/Ion propulsion
- 7.4 Hybrid propulsion systems
Chapter 8 Market Estimates and Forecast, By Application, 2022 - 2035 (USD Million)
- 8.1 Key trends
- 8.2 Chemical propulsion
- 8.3 Electric/Ion propulsion
- 8.4 Hybrid propulsion systems
Chapter 9 Market Estimates and Forecast, By End Use, 2022 - 2035 (USD Million)
- 9.1 Key trends
- 9.2 Government and defense
- 9.3 Space exploration organizations
- 9.4 Private aerospace companies
- 9.5 Research institutions
Chapter 10 Market Estimates and Forecast, By Region, 2022 - 2035 (USD Million)
- 10.1 Key trends
- 10.2 North America
- 10.2.1 U.S.
- 10.2.2 Canada
- 10.3 Europe
- 10.3.1 Germany
- 10.3.2 UK
- 10.3.3 France
- 10.3.4 Spain
- 10.3.5 Italy
- 10.3.6 Netherlands
- 10.4 Asia Pacific
- 10.4.1 China
- 10.4.2 India
- 10.4.3 Japan
- 10.4.4 Australia
- 10.4.5 South Korea
- 10.5 Latin America
- 10.5.1 Brazil
- 10.5.2 Mexico
- 10.5.3 Argentina
- 10.6 Middle East and Africa
- 10.6.1 South Africa
- 10.6.2 Saudi Arabia
- 10.6.3 UAE
Chapter 11 Company Profiles
- 11.1 Global Key Players
- 11.1.1 Lockheed Martin Corporation
- 11.1.2 Northrop Grumman Corporation
- 11.1.3 NASA
- 11.1.4 Roscosmos
- 11.1.5 Airbus SE
- 11.2 Regional key players
- 11.2.1 North America
- 11.2.1.1 Blue Origin
- 11.2.1.2 Canadian Space Agency
- 11.2.2 Asia Pacific
- 11.2.2.1 ISRO
- 11.2.2.2 Japan Aerospace Exploration Agency (JAXA)
- 11.2.2.3 China Academy of Space Technology
- 11.2.3 Europe
- 11.2.3.1 European Space Agency
- 11.2.3.2 Spacebit Technologies
- 11.2.1 North America
- 11.3 Niche Players/Disruptors
- 11.3.1 Astrobotic Technology
- 11.3.2 ispace, inc.


