


 |
市場調查報告書
商品編碼
1876468
全球空間感測器和致動器市場(至2030年)按產品類型(感測器和致動器)、平台(衛星、太空艙/貨物艙、星際太空船和探勘、運載火箭)、應用、最終用戶和地區分類Space Sensors and Actuators Market by Product Type (Sensors, Actuators), Platform (Satellites, Capsules/Cargo, Interplanetary Spacecraft and Probes, Launch Vehicles), Application, End User, Region - Global Forecast to 2030 |
||||||


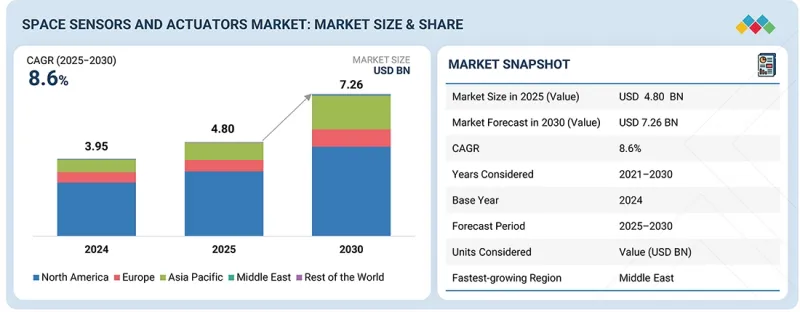
預計空間感測器和致動器市場將從 2025 年的 48 億美元成長到 2030 年的 72.6 億美元,複合年成長率為 8.6%。
| 調查範圍 | |
|---|---|
| 調查期 | 2021-2030 |
| 基準年 | 2024 |
| 預測期 | 2025-2030 |
| 單元 | 金額(美元) |
| 部分 | 產品類型、平台、應用程式、最終用戶、地區 |
| 目標區域 | 北美、歐洲、亞太地區及其他地區 |
對太空感測器和致動器的需求不斷成長,這主要得益於對商業航太營運、國防監視和科學探勘的投資不斷增加,從而加速了全球任務中採用先進、小型化和人工智慧賦能的組件。
“通訊指向和射頻交換應用佔據最大的市場佔有率”
按應用領域分類,通訊指向和射頻切換領域預計將在預測期內佔據最大佔有率,這主要得益於高速衛星通訊和精密訊號調理系統需求的不斷成長。隨著低地球軌道 (LEO) 和中地球軌道 (MEO)衛星星系數量的不斷增加,感測器和致動器在維持天線定向、訊號穩定性和資料傳輸精度方面發揮著至關重要的作用。採用電子機械致動器和精密回授感測器進行動態指向和波束控制,正在提升衛星網路的效率。隨著寬頻連接、地球觀測和國防通訊投資的不斷增加,該子系統對於實現可靠的衛星間鏈路和網路同步至關重要,從而確立了其作為市場關鍵應用領域的地位。
“按平台分類,行星際探勘和探探勘測器領域的複合年成長率將最高。”
這主要得益於深空探勘和行星科學任務的增加。美國國家航空暨太空總署(NASA)、歐洲太空總署(ESA)、日本宇宙航空研究開發機構(JAXA)和印度太空研究組織(ISRO)等機構正在加速對月球、火星和小行星探測任務的投資,這些任務需要高度堅固耐用、自主運作且抗輻射的感測和執行系統。這些太空船依靠精密姿態控制致動器、慣性感測器和環境監測設備在極端溫度和輻射環境下運作。不斷擴大的國際合作和私人探勘企業的崛起也推動了下一代感測器和致動器的進一步整合,以支援地球軌道以外的科學任務的自適應導航、著陸控制和原位樣本處理。
預計亞太地區在預測期內將佔據第二大市場佔有率。
預計亞太地區在預測期內將佔據第二大市場佔有率,這主要得益於包括印度、日本和中國在內的主要國家國家航太計劃的快速發展以及私營部門參與度的不斷提高。政府主導的航太任務正在推動對先進空間感測器和致動器的需求。該地區的製造商正致力於自主研發小型衛星系統和微型化控制技術,旨在增強自主能力並降低進口依賴。此外,對衛星通訊、遙感探測和國防監視領域投資的不斷增加,也進一步鞏固了市場成長勢頭,使亞太地區成為下一代太空技術研發和部署的關鍵樞紐。
本報告調查了全球空間感測器和致動器市場,並提供了市場概況、影響市場成長的各種因素分析、技術和專利趨勢、法律制度、案例研究、市場規模趨勢和預測、按各個細分市場、地區/主要國家/地區進行的詳細分析、競爭格局以及主要企業的概況。
目錄
第1章 引言
第2章調查方法
第3章執行摘要
第4章重要考察
第5章 市場概覽
- 市場動態
- 促進要素
- 抑制因素
- 機會
- 任務
- 空間感測器和致動器市場中尚未滿足的需求和空白領域
- 互聯市場與跨產業機遇
- 一級/二級/三級公司的策略性舉措
第6章 產業趨勢
- 總體經濟指標
- 價值鏈分析
- 生態系分析
- 貿易數據
- 重大會議和活動
- 影響您業務的趨勢和顛覆性因素
- 投資和資金籌措方案
- 定價分析
- 用例分析
第7章:透過科技、專利、數位化和人工智慧應用實現策略顛覆
- 關鍵新興技術
- 互補技術
- 技術藍圖
- 新興科技趨勢
- 專利分析
- 未來應用
- 人工智慧/生成式人工智慧對空間感測器和致動器市場的影響
- 成功案例和實際應用
第8章:顧客狀況與購買行為
- 決策流程
- 主要相關利益者和採購評估標準
- 招募障礙和內部挑戰
第9章永續性和監管環境
- 關稅和監管狀況
- 法規結構
- 對永續性的承諾
- 永續性影響和監管政策舉措
- 認證、標籤和環境標準
10. 按產品類型分類的空間感測器和致動器市場
- 用例分析
- 地球觀測與環境監測
- 機器人操作與樣品處理(NASA 的火星毅力號探測車)
- 感應器
- 姿態和導航感應器
- 環境感測器
- 影像感測器
- 接近感測器、位置感測器和距離感測器
- 科學感測器
- 其他
- 致動器
- 線性致動器
- 旋轉致動器
11. 按平台分類的空間感測器和致動器市場
- 用例分析
- 鴿子行星立方衛星衛星群
- 歐洲太空總署的哨兵中型衛星平台
- 空中巴士防務與航太公司的Skynet小型衛星平台
- Maxar Technologies 的 WorldView 大型衛星平台
- 波音公司的星際客機載人太空船平台
- SpaceX的龍飛船無人太空船平台
- 歐洲太空總署的JUICE深空探勘平台
- 德國航空航太中心(DLR)的菲萊著陸器平台
- Rocket Lab 的 Electron 迷你火箭
- 衛星
- 立方衛星
- 小型衛星
- 中型衛星
- 大型衛星
- 膠囊/貨物
- 行星際探勘
- 探測車/太空船著陸器
- 發射火箭
- 小型火箭(小於350,000公斤)
- 中型至大型火箭(超過 35 萬公斤)
12. 按應用分類的空間感測器和致動器市場
- 姿態和軌道控制系統
- 通訊指向和射頻切換
- 觀測設備指向和光電機構
- 部署和分離系統
- 熱控制系統
- 推進和流體系統
- 鄰近性、結合和對接系統
- 地面機動與導航系統
- 機械臂/機械手臂系統
- 推力向量控制系統
- 太陽能電池陣列驅動機構
- 其他
13. 按最終用戶分類的空間感測器和致動器市場
- 商業的
- 衛星和運載火箭製造商
- 在軌服務供應商
- 有效載荷提供者
- 商業經營者和所有者
- 政府/國防
- 國家航太局
- 國防部
- 學術研究
14. 各區域空間感測器和致動器市場
- 北美洲
- 美國
- 加拿大
- 歐洲
- 俄羅斯
- 德國
- 法國
- 英國
- 義大利
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 澳洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他
- 其他地區
- 拉丁美洲
- 非洲
第15章 競爭格局
- 主要參與企業的策略/優勢
- 收入分析
- 市佔率分析
- 品牌對比
- 估值和財務指標
- 公司評估矩陣:主要企業
- 公司估值矩陣:Start-Ups/中小企業
- 競爭場景
- 產品發布
- 交易
- 其他
第16章:公司簡介
- 主要企業
- HONEYWELL INTERNATIONAL INC.
- TELEDYNE TECHNOLOGIES INCORPORATED
- MOOG INC.
- SAFRAN GROUP
- AIRBUS
- L3HARRIS TECHNOLOGIES, INC.
- RTX
- VANTOR
- TEXAS INSTRUMENTS INCORPORATED
- AMETEK.INC.
- RUAG GROUP
- ANALOG DEVICES, INC.
- BAE SYSTEMS
- STMICROELECTRONICS
- BLUE ORIGIN
- TE CONNECTIVITY
- 其他公司
- INNALABS
- COMAT
- SPACE-LOCK GMBH
- NEWSPACE SYSTEMS
- VEOWARE
- CEDRAT TECHNOLOGIES SA
- CUBESPACE SATELLITE SYSTEMS
- MAGSON GMBH
- ISP SYSTEM
- BARTINGTON INSTRUMENTS LTD
第17章附錄
The space sensors and actuators market is estimated at USD 4.80 billion in 2025 and is projected to reach USD 7.26 billion by 2030 at a CAGR of 8.6%.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2030 |
| Base Year | 2024 |
| Forecast Period | 2025-2030 |
| Units Considered | Value (USD Billion) |
| Segments | By Product Type, Platform, Application, End User and Region |
| Regions covered | North America, Europe, APAC, RoW |
The rising demand for space sensors and actuators is driven by the increasing investments in commercial space ventures, defense surveillance, and scientific exploration, accelerating the adoption of advanced, miniaturized, and AI-enabled components across global missions.
"The communication pointing & RF switching application segment is expected to hold the largest market share."
Based on application, the communication pointing & RF switching segment is expected to hold the largest share in the space sensors and actuators market during the forecast period, primarily driven by the increasing demand for high-speed satellite communication and precise signal alignment systems. As the number of LEO and MEO satellite constellations grows, sensors and actuators are playing a critical role in maintaining antenna orientation, signal stability, and data transmission accuracy. The adoption of electromechanical actuators and precision feedback sensors for dynamic pointing and beam steering is enhancing satellite network efficiency. With rising investments in broadband connectivity, Earth observation, and defense communication satellites, this subsystem is becoming integral to achieving reliable inter-satellite links and network synchronization, positioning it as the leading application segment of the market.
"The interplanetary spacecraft and probes platform segment is projected to register the highest CAGR."
Based on platform, the interplanetary spacecraft and probes segment is projected to register the highest CAGR during the forecast period, propelled by an increasing number of deep space exploration and planetary science missions. Agencies such as NASA, ESA, JAXA, and ISRO are accelerating investments in lunar, Mars, and asteroid missions that require highly durable, autonomous, and radiation-hardened sensing and actuation systems. These spacecraft rely on precision attitude control actuators, inertial sensors, and environmental monitoring instruments to operate under extreme temperature and radiation conditions. The growth of international collaborations, coupled with the emergence of private exploration ventures, is further driving the integration of next-generation sensors and actuators that support adaptive navigation, landing control, and in-situ sample handling for scientific missions beyond Earth orbit.
"The Asia Pacific is expected to account for the second-largest market share."
The Asia Pacific is expected to account for the second-largest market share during the forecast period, driven by the rapid expansion of national space programs and increased private participation across key countries, including India, Japan, and China. Government-led missions are fueling demand for advanced space sensors and actuators. Regional manufacturers are focusing on the indigenous development of small-satellite systems and miniaturized control technologies to strengthen self-reliance and reduce import dependency. Additionally, growing investments in satellite communication, remote sensing, and defense surveillance are enhancing the market's growth trajectory, positioning the Asia Pacific as a critical hub for next-generation space technology production and deployment.
The break-up of the profile of primary participants in the space sensors and actuators market:
- By Company Type: Tier 1 - 35%, Tier 2 - 45%, and Tier 3 - 20%
- By Designation: Directors- 25%, Managers - 35%, Others - 40%
- By Region: North America - 30%, Europe - 10%, Asia Pacific - 40%, Middle East-15%, Latin America-3%, Africa-2%
Honeywell International Inc. (US), Teledyne Technologies Incorporated. (US), Airbus (France), Moog Inc. (US), and Safran (France). These key players offer connectivity applicable to various sectors and have well-equipped and strong distribution networks across North America, Europe, the Asia Pacific, the Middle East, and the Rest of the World.
Research Coverage:
The study covers the space sensors and actuators market across various segments and subsegments. It aims to estimate the size and growth potential of this market across different segments based on product type, application, platform, end user, and region. This study also includes an in-depth competitive analysis of the key players in the market, along with their company profiles, key observations related to their solutions and business offerings, recent developments undertaken by them, and key market strategies adopted by them.
This report segments the space sensors and actuators market across five key regions: North America, Europe, the Asia Pacific, the Middle East, and the Rest of the World, and their respective key countries. The report's scope includes in-depth information on significant factors, such as drivers, restraints, challenges, and opportunities that influence the growth of the market.
A comprehensive analysis of major industry players has been conducted to provide insights into their business profiles, solutions, and services. This analysis also covers key aspects like agreements, collaborations, product launches, contracts, expansions, acquisitions, and partnerships associated with the space sensors and actuators market.
Reasons to buy this report:
This report serves as a valuable resource for market leaders and new entrants in the space sensors and actuators market, offering data that closely approximates revenue figures for both the overall market and its subsegments. It equips stakeholders with a comprehensive understanding of the competitive landscape, facilitating informed decisions to enhance their market positioning and formulate effective go-to-market strategies. The report imparts valuable insights into the market dynamics, offering information on crucial factors such as drivers, restraints, challenges, and opportunities, enabling stakeholders to gauge the market's pulse.
The report provides insights into the following pointers:
- Analysis of key drivers and factors, such as the rapid growth of satellite constellations, exploration missions, and autonomous spacecraft operations requiring precise navigation and control
- Market Penetration: Comprehensive information on space sensor and actuator solutions offered by the top players in the market
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product launches in the space sensors and actuators market
- Market Development: Comprehensive information about lucrative markets (the report analyzes the space sensors and actuators market across varied regions)
- Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the space sensors and actuators market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players in the space sensors and actuators market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 YEARS CONSIDERED
- 1.3.3 INCLUSIONS AND EXCLUSIONS
- 1.4 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 SUMMARY OF CHANGES
2 RESEARCH METHODOLOGY
- 2.1 RESEARCH DATA
- 2.1.1 SECONDARY DATA
- 2.1.1.1 List of secondary sources
- 2.1.2 PRIMARY DATA
- 2.1.2.1 Key data from primary sources
- 2.1.2.2 Breakdown of primaries: By company type, designation, and region
- 2.1.1 SECONDARY DATA
- 2.2 FACTOR ANALYSIS
- 2.2.1 INTRODUCTION
- 2.2.2 DEMAND-SIDE INDICATORS
- 2.2.3 SUPPLY-SIDE INDICATORS
- 2.3 MARKET SIZE ESTIMATION
- 2.3.1 BOTTOM-UP APPROACH
- 2.3.2 TOP-DOWN APPROACH
- 2.4 DATA TRIANGULATION
- 2.5 RESEARCH ASSUMPTIONS
- 2.6 RESEARCH LIMITATIONS
- 2.7 RISK ASSESSMENT
3 EXECUTIVE SUMMARY
- 3.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 3.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 3.3 HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS
- 3.4 SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
- 3.5 BUSINESS MODELS
4 PREMIUM INSIGHTS
- 4.1 ATTRACTIVE GROWTH OPPORTUNITIES FOR PLAYERS IN SPACE SENSORS AND ACTUATORS MARKET
- 4.2 SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE
- 4.3 SPACE SENSORS AND ACTUATORS MARKET, BY END USER
- 4.4 SPACE SENSORS AND ACTUATORS MARKET, BY PLATFORM
5 MARKET OVERVIEW
- 5.1 INTRODUCTION
- 5.2 MARKET DYNAMICS
- 5.2.1 DRIVERS
- 5.2.1.1 Surge in satellite deployments and constellations
- 5.2.1.2 Technological innovation and miniaturization
- 5.2.1.3 Growing need for precise sensing, actuation, and adaptive control
- 5.2.2 RESTRAINTS
- 5.2.2.1 Stringent regulatory and certification requirements
- 5.2.2.2 Legacy system integration complexity
- 5.2.3 OPPORTUNITIES
- 5.2.3.1 Expanding demand from deep space and lunar exploration programs
- 5.2.3.2 Rising adoption of sensors and actuators in small satellite platforms
- 5.2.3.3 Integration of AI and sensor fusion for autonomous spacecraft
- 5.2.4 CHALLENGES
- 5.2.4.1 Long development cycles and technology obsolescence risk
- 5.2.4.2 Overcoming integration and interference complexities
- 5.2.1 DRIVERS
- 5.3 UNMET NEEDS AND WHITE SPACES IN SPACE SENSORS AND ACTUATORS MARKET
- 5.4 INTER-CONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 5.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
6 INDUSTRY TRENDS
- 6.1 INTRODUCTION
- 6.2 MACROECONOMIC INDICATORS
- 6.2.1 INTRODUCTION
- 6.2.2 GDP TRENDS AND FORECAST
- 6.2.3 TRENDS IN GLOBAL SPACE INDUSTRY
- 6.3 VALUE CHAIN ANALYSIS
- 6.4 ECOSYSTEM ANALYSIS
- 6.4.1 PROMINENT COMPANIES
- 6.4.2 PRIVATE AND SMALL ENTERPRISES
- 6.4.3 END USERS
- 6.5 TRADE DATA
- 6.5.1 IMPORT SCENARIO (HS CODE 880260)
- 6.5.2 EXPORT SCENARIO (HS CODE 880260)
- 6.6 KEY CONFERENCES AND EVENTS, 2025-2026
- 6.7 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 6.8 INVESTMENT AND FUNDING SCENARIO
- 6.9 PRICING ANALYSIS
- 6.9.1 INDICATIVE PRICING ANALYSIS, BY PRODUCT TYPE
- 6.9.2 AVERAGE SELLING PRICE TREND, BY REGION
- 6.10 USE CASE ANALYSIS
- 6.10.1 SODERN DEVELOPED STAR TRACKER SENSORS FOR ULTRA-ACCURATE ATTITUDE DETERMINATION FOR SATELLITES
- 6.10.2 US AIR FORCE AND BALL AEROSPACE CONDUCTED RADIATION HARDNESS TEST ON ELECTRO-OPTICAL SENSORS
- 6.10.3 PHYSIK INSTRUMENTE SUPPLIED SPACE-QUALIFIED PIEZOELECTRIC ACTUATORS FOR NASA'S PERSEVERANCE ROVER SUPERCAM INSTRUMENT
7 STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTIONS
- 7.1 KEY EMERGING TECHNOLOGIES
- 7.1.1 MINIATURIZED MEMS-BASED SENSORS AND ACTUATORS
- 7.1.2 AI-ENABLED AUTONOMOUS SENSING SYSTEMS
- 7.1.3 QUANTUM AND PHOTONIC SENSOR PLATFORMS
- 7.2 COMPLEMENTARY TECHNOLOGIES
- 7.2.1 ADVANCED ONBOARD DATA PROCESSING (EDGE COMPUTING)
- 7.2.2 ADDITIVE MANUFACTURING OF SENSOR AND ACTUATOR COMPONENTS
- 7.2.3 RADIATION-HARDENED ELECTRONICS AND MATERIALS
- 7.3 TECHNOLOGY ROADMAP
- 7.4 EMERGING TECHNOLOGY TRENDS
- 7.5 PATENT ANALYSIS
- 7.6 FUTURE APPLICATIONS
- 7.7 IMPACT OF AI/ GENERATIVE AI ON SPACE SENSORS AND ACTUATORS MARKET
- 7.7.1 TOP USE CASES AND MARKET POTENTIAL
- 7.7.2 BEST PRACTICES IN SPACE SENSORS AND ACTUATORS MARKET
- 7.7.3 CASE STUDIES OF AI IMPLEMENTATION IN SPACE SENSORS AND ACTUATORS MARKET
- 7.7.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 7.7.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN SPACE SENSORS AND ACTUATORS MARKET
- 7.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 7.8.1 HONEYWELL AEROSPACE: ADVANCING AI-DRIVEN NAVIGATION AND ACTUATION SYSTEMS
- 7.8.2 LOCKHEED MARTIN: PIONEERING AUTONOMOUS SENSOR-ACTUATOR INTEGRATION
- 7.8.3 TELEDYNE TECHNOLOGIES: DELIVERING PRECISION IMAGING AND ACTUATION FOR DEEP SPACE MISSIONS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
9 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 9.1 TARIFF AND REGULATORY LANDSCAPE
- 9.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 9.2 REGULATORY FRAMEWORK
- 9.2.1 NORTH AMERICA
- 9.2.2 EUROPE
- 9.2.3 ASIA PACIFIC
- 9.2.4 MIDDLE EAST
- 9.2.5 LATIN AMERICA AND AFRICA
- 9.2.6 INDUSTRY STANDARDS
- 9.3 SUSTAINABILITY INITIATIVES
- 9.4 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 9.5 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
10 SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE
- 10.1 INTRODUCTION
- 10.2 USE CASE ANALYSIS
- 10.2.1 EARTH OBSERVATION AND ENVIRONMENTAL MONITORING
- 10.2.2 ROBOTIC MANIPULATION AND SAMPLE HANDLING (NASA'S MARS PERSEVERANCE ROVER)
- 10.3 SENSORS
- 10.3.1 ATTITUDE & NAVIGATION SENSORS
- 10.3.1.1 Need for precise orientation, stabilization, and trajectory control in satellites and spacecraft to drive growth
- 10.3.1.2 Magnetometers
- 10.3.1.3 Sun sensors
- 10.3.1.4 Earth horizon sensors
- 10.3.1.5 Star sensors
- 10.3.1.6 Gyroscopes
- 10.3.1.7 Accelerometers
- 10.3.1.8 GNSS receivers
- 10.3.2 ENVIRONMENTAL SENSORS
- 10.3.2.1 Increase in long-duration missions to drive growth
- 10.3.2.2 Temperature sensors
- 10.3.2.3 Flow meters
- 10.3.2.4 Radiation dosimeters
- 10.3.2.5 Electrical current/voltage sensors
- 10.3.2.6 Atmospheric/gas sensors
- 10.3.2.7 Pressure sensors
- 10.3.3 IMAGE SENSORS
- 10.3.3.1 Small satellites and exploration programs to drive growth
- 10.3.3.2 Electro-optical sensors
- 10.3.3.3 Thermal imaging sensors
- 10.3.3.4 Radar imaging sensors
- 10.3.4 PROXIMITY, POSITION, AND RANGING SENSORS
- 10.3.4.1 Increasing use of autonomous and cooperative satellite missions to drive growth
- 10.3.4.2 Hall-effect sensors
- 10.3.4.3 Inductive non-contact position sensors
- 10.3.4.4 Limit/proximity switches
- 10.3.4.5 Force sensors
- 10.3.4.6 Encoders
- 10.3.4.7 Resolvers/Linear variable differential transformers (LVDTs)/ Rotary variable differential transformers (RVDTs)
- 10.3.4.8 LiDAR sensors
- 10.3.4.9 Rendezvous/docking radar sensors
- 10.3.5 SCIENTIFIC SENSORS
- 10.3.5.1 Use in satellites, probes, and landers to obtain direct measurements from planetary environments to drive growth
- 10.3.5.2 Spectrometer sensors
- 10.3.5.3 Vacuum-ultraviolet (UV) photodetectors
- 10.3.5.4 Gravity sensors
- 10.3.6 OTHERS
- 10.3.1 ATTITUDE & NAVIGATION SENSORS
- 10.4 ACTUATORS
- 10.4.1 LINEAR ACTUATORS
- 10.4.1.1 Rising number of small satellites and modular spacecraft to drive growth
- 10.4.1.2 Electric
- 10.4.1.3 Hydraulic
- 10.4.1.4 Pneumatic
- 10.4.1.5 Smart materials
- 10.4.2 ROTARY ACTUATORS
- 10.4.2.1 Electric
- 10.4.2.2 Hydraulic
- 10.4.2.3 Pneumatic
- 10.4.2.4 Smart Materials
- 10.4.1 LINEAR ACTUATORS
11 SPACE SENSORS AND ACTUATORS MARKET, BY PLATFORM
- 11.1 INTRODUCTION
- 11.2 USE CASE ANALYSIS
- 11.2.1 PLANET DOVE CUBESAT CONSTELLATION
- 11.2.2 SENTINEL MEDIUM SATELLITE PLATFORM BY ESA
- 11.2.3 SKYNET SMALL SATELLITE PLATFORM BY AIRBUS DEFENCE AND SPACE
- 11.2.4 WORLDVIEW LARGE SATELLITE PLATFORM BY MAXAR TECHNOLOGIES
- 11.2.5 STARLINER CREWED SPACECRAFT PLATFORM BY BOEING
- 11.2.6 DRAGON UNCREWED SPACECRAFT PLATFORM BY SPACEX
- 11.2.7 JUICE INTERPLANETARY SPACECRAFT PLATFORM BY ESA
- 11.2.8 PHILAE LANDER PLATFORM BY DLR
- 11.2.9 ELECTRON SMALL LAUNCH VEHICLE BY ROCKET LAB
- 11.3 SATELLITES
- 11.3.1 GROWING DEMAND FOR ACCURATE EARTH OBSERVATION, COMMUNICATION, AND SCIENTIFIC APPLICATIONS TO DRIVE GROWTH
- 11.3.2 CUBESATS
- 11.3.2.1 Surge in use for Earth observation, remote sensing, and technology demonstrations to drive growth
- 11.3.3 SMALL SATELLITES
- 11.3.3.1 Growing use for Earth observation, environmental monitoring, and defense applications to drive market
- 11.3.3.2 Nano satellites
- 11.3.3.3 Mini satellites
- 11.3.3.4 Macro satellites
- 11.3.4 MEDIUM SATELLITES
- 11.3.4.1 Increasing requirements for regional connectivity, surveillance, and data relay functions to drive growth
- 11.3.5 LARGE SATELLITES
- 11.3.5.1 Ability to manage multiple instruments and complex mission profiles to drive growth
- 11.3.6 CAPSULES/CARGO
- 11.3.6.1 Increasing orbital logistics to drive growth
- 11.3.6.2 Crewed spacecraft
- 11.3.6.3 Uncrewed spacecraft
- 11.4 INTERPLANETARY SPACECRAFT AND PROBES
- 11.4.1 DEEP SPACE EXPLORATIONS TO DRIVE GROWTH
- 11.5 ROVERS/SPACECRAFT LANDERS
- 11.5.1 OPERATE AUTONOMOUSLY OR WITH LIMITED GROUND CONTROL, USING IMAGING, THERMAL, AND SPECTROSCOPIC INSTRUMENTS
- 11.6 LAUNCH VEHICLES
- 11.6.1 INCREASE IN LAUNCH ACTIVITIES BY GOVERNMENT AND COMMERCIAL OPERATORS TO DRIVE GROWTH
- 11.6.2 SMALL LAUNCH VEHICLES (<350,000 KG)
- 11.6.3 MEDIUM-TO-HEAVY LAUNCH VEHICLES (>350,000 KG)
12 SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION
- 12.1 INTRODUCTION
- 12.2 ATTITUDE & ORBITAL CONTROL SYSTEMS
- 12.2.1 CONTROL ATTITUDE AND POSITION OF SATELLITES
- 12.3 COMMUNICATION POINTING & RF SWITCHING
- 12.3.1 RAPID DEPLOYMENT OF LEO CONSTELLATIONS AND INTER-SATELLITE LINK ARCHITECTURE TO DRIVE GROWTH
- 12.4 INSTRUMENT POINTING & OPTO-MECHANISMS
- 12.4.1 NEED FOR PRECISE ALIGNMENT AND STABILITY IN ADVANCED IMAGING AND SCIENTIFIC PAYLOADS TO DRIVE GROWTH
- 12.5 DEPLOYMENT & SEPARATION SYSTEMS
- 12.5.1 GROWING NUMBER OF RIDESHARE LAUNCHES AND CUBESAT MISSIONS TO DRIVE DEMAND
- 12.6 THERMAL CONTROL SYSTEMS
- 12.6.1 MAINTAIN TEMPERATURES OF SPACECRAFT, LAUNCH VEHICLES, AND ROVERS
- 12.7 PROPULSION & FLUID SYSTEMS
- 12.7.1 ENABLE PRECISE CONTROL OF SPACECRAFT THRUST AND FLUID FLOW
- 12.8 PROXIMITY, BERTHING, AND DOCKING SYSTEMS
- 12.8.1 GROWING FOCUS ON REUSABLE SPACECRAFT AND MODULAR STRUCTURES TO DRIVE GROWTH
- 12.9 SURFACE MOBILITY AND NAVIGATION SYSTEMS
- 12.9.1 PROVIDE NAVIGATIONAL SUPPORT
- 12.10 ROBOTIC ARMS/MANIPULATOR SYSTEMS
- 12.10.1 IN-ORBIT ASSEMBLY DRIVES ROBOTIC ARM AND MANIPULATOR INTEGRATION
- 12.11 THRUST VECTOR CONTROL SYSTEMS
- 12.11.1 CONTROL ATTITUDE OR ANGULAR VELOCITY
- 12.12 SOLAR ARRAY DRIVE MECHANISMS
- 12.12.1 DEVELOPMENT OF SOLAR ARRAY DRIVE ASSEMBLIES FOR CUBESATS TO DRIVE GROWTH
- 12.13 OTHERS
13 SPACE SENSORS AND ACTUATORS MARKET, BY END USER
- 13.1 INTRODUCTION
- 13.2 COMMERCIAL
- 13.2.1 INVESTMENT BY PRIVATE PLAYERS TO INCREASE EXPLORATION MISSIONS
- 13.2.2 SATELLITE AND LAUNCH VEHICLE MANUFACTURERS
- 13.2.3 IN-ORBIT SERVICE PROVIDERS
- 13.2.4 PAYLOAD PROVIDERS
- 13.2.5 COMMERCIAL OPERATORS & OWNERS
- 13.3 GOVERNMENT & DEFENSE
- 13.3.1 EMPHASIS ON IMPROVING SPACECRAFT EFFICIENCY AND REDUCING MANUAL INTERVENTION TO DRIVE GROWTH
- 13.3.2 NATIONAL SPACE AGENCIES
- 13.3.3 DEPARTMENTS OF DEFENSE
- 13.3.4 ACADEMIA & RESEARCH
14 SPACE SENSORS AND ACTUATORS MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 US
- 14.2.1.1 Increasing number of satellite launches by commercial space sector to drive growth
- 14.2.2 CANADA
- 14.2.2.1 Expansion of satellite constellations, in-orbit servicing missions, and robotic systems to drive growth
- 14.2.1 US
- 14.3 EUROPE
- 14.3.1 RUSSIA
- 14.3.1.1 Focus on domestic production of space-qualified components to drive growth
- 14.3.2 GERMANY
- 14.3.2.1 Shift toward smaller satellite constellations and reusable platforms to drive growth
- 14.3.3 FRANCE
- 14.3.3.1 Focus on domestic capability in spacecraft component production to drive growth
- 14.3.4 UK
- 14.3.4.1 Increase in small satellites, commercial launch platforms, and in-orbit service missions to drive growth
- 14.3.5 ITALY
- 14.3.5.1 Programs related to reusable propulsion systems, small satellite constellations, and lunar exploration to drive growth
- 14.3.1 RUSSIA
- 14.4 ASIA PACIFIC
- 14.4.1 CHINA
- 14.4.1.1 Advancements in space missions and space stations to drive growth
- 14.4.2 INDIA
- 14.4.2.1 Indigenization of technologies and participation of private sector in space industry to drive growth
- 14.4.3 JAPAN
- 14.4.3.1 Growing focus of private companies on developing advanced technologies for space systems to drive growth
- 14.4.4 SOUTH KOREA
- 14.4.4.1 Domestic satellite and space launch industry driven by private sector to boost market
- 14.4.5 AUSTRALIA
- 14.4.5.1 Increasing small satellite manufacturing and launch activities to drive growth
- 14.4.1 CHINA
- 14.5 MIDDLE EAST
- 14.5.1 SAUDI ARABIA
- 14.5.1.1 Expansion of Earth observation capabilities to drive growth
- 14.5.2 UAE
- 14.5.2.1 Progress in satellite manufacturing to drive growth
- 14.5.3 REST OF MIDDLE EAST
- 14.5.1 SAUDI ARABIA
- 14.6 REST OF THE WORLD
- 14.6.1 LATIN AMERICA
- 14.6.1.1 Collaborations with foreign space agencies to drive growth
- 14.6.2 AFRICA
- 14.6.2.1 Launch of nanosatellites to drive growth
- 14.6.1 LATIN AMERICA
15 COMPETITIVE LANDSCAPE
- 15.1 INTRODUCTION
- 15.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, 2021-2024
- 15.3 REVENUE ANALYSIS, 2021-2024
- 15.4 MARKET SHARE ANALYSIS, 2024
- 15.5 BRAND COMPARISON
- 15.6 COMPANY VALUATION AND FINANCIAL METRICS
- 15.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2024
- 15.7.1 STARS
- 15.7.2 EMERGING LEADERS
- 15.7.3 PERVASIVE PLAYERS
- 15.7.4 PARTICIPANTS
- 15.7.5 COMPANY FOOTPRINT
- 15.7.5.1 Company footprint
- 15.7.5.2 Region footprint
- 15.7.5.3 Product type footprint
- 15.7.5.4 End user footprint
- 15.7.5.5 Platform footprint
- 15.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2024
- 15.8.1 PROGRESSIVE COMPANIES
- 15.8.2 RESPONSIVE COMPANIES
- 15.8.3 DYNAMIC COMPANIES
- 15.8.4 STARTING BLOCKS
- 15.8.5 COMPETITIVE BENCHMARKING
- 15.8.5.1 List of startups/SMEs
- 15.8.5.2 Competitive benchmarking of startups/SMEs
- 15.9 COMPETITIVE SCENARIO
- 15.10 PRODUCT LAUNCHES
- 15.11 DEALS
- 15.12 OTHERS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 HONEYWELL INTERNATIONAL INC.
- 16.1.1.1 Business overview
- 16.1.1.2 Products offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Product launches
- 16.1.1.3.2 Deals
- 16.1.1.3.3 Others
- 16.1.1.4 MnM view
- 16.1.1.4.1 Right to win
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses and competitive threats
- 16.1.2 TELEDYNE TECHNOLOGIES INCORPORATED
- 16.1.2.1 Business overview
- 16.1.2.2 Products offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Product launches
- 16.1.2.3.2 Deals
- 16.1.2.3.3 Others
- 16.1.2.4 MnM view
- 16.1.2.4.1 Right to win
- 16.1.2.4.2 Strategic choices
- 16.1.2.4.3 Weaknesses and competitive threats
- 16.1.3 MOOG INC.
- 16.1.3.1 Business overview
- 16.1.3.2 Products offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Expansions
- 16.1.3.3.2 Others
- 16.1.3.4 MnM view
- 16.1.3.4.1 Right to win
- 16.1.3.4.2 Strategic choices
- 16.1.3.4.3 Weaknesses and competitive threats
- 16.1.4 SAFRAN GROUP
- 16.1.4.1 Business overview
- 16.1.4.2 Products offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Deals
- 16.1.4.3.2 Others
- 16.1.4.4 MnM view
- 16.1.4.4.1 Right to win
- 16.1.4.4.2 Strategic choices
- 16.1.4.4.3 Weaknesses and competitive threats
- 16.1.5 AIRBUS
- 16.1.5.1 Business overview
- 16.1.5.2 Products offered
- 16.1.5.3 MnM view
- 16.1.5.3.1 Right to win
- 16.1.5.3.2 Strategic choices
- 16.1.5.3.3 Weaknesses and competitive threats
- 16.1.6 L3HARRIS TECHNOLOGIES, INC.
- 16.1.6.1 Business overview
- 16.1.6.2 Products offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Others
- 16.1.7 RTX
- 16.1.7.1 Business overview
- 16.1.7.2 Products offered
- 16.1.7.3 Recent developments
- 16.1.7.3.1 Others
- 16.1.8 VANTOR
- 16.1.8.1 Business overview
- 16.1.8.2 Products offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Deals
- 16.1.8.3.2 Others
- 16.1.9 TEXAS INSTRUMENTS INCORPORATED
- 16.1.9.1 Business overview
- 16.1.9.2 Products offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Product launches
- 16.1.9.3.2 Expansions
- 16.1.10 AMETEK.INC.
- 16.1.10.1 Business overview
- 16.1.10.2 Products offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Deals
- 16.1.11 RUAG GROUP
- 16.1.11.1 Business overview
- 16.1.11.2 Products offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Others
- 16.1.12 ANALOG DEVICES, INC.
- 16.1.12.1 Business overview
- 16.1.12.2 Products offered
- 16.1.13 BAE SYSTEMS
- 16.1.13.1 Business overview
- 16.1.13.2 Products offered
- 16.1.13.3 Recent developments
- 16.1.13.3.1 Product launches
- 16.1.13.3.2 Deals
- 16.1.13.3.3 Others
- 16.1.14 STMICROELECTRONICS
- 16.1.14.1 Business overview
- 16.1.14.2 Products offered
- 16.1.15 BLUE ORIGIN
- 16.1.15.1 Business overview
- 16.1.15.2 Products offered
- 16.1.15.3 Recent developments
- 16.1.15.3.1 Deals
- 16.1.15.3.2 Others
- 16.1.16 TE CONNECTIVITY
- 16.1.16.1 Business overview
- 16.1.16.2 Products offered
- 16.1.16.3 Recent developments
- 16.1.16.3.1 Deals
- 16.1.1 HONEYWELL INTERNATIONAL INC.
- 16.2 OTHER PLAYERS
- 16.2.1 INNALABS
- 16.2.2 COMAT
- 16.2.3 SPACE-LOCK GMBH
- 16.2.4 NEWSPACE SYSTEMS
- 16.2.5 VEOWARE
- 16.2.6 CEDRAT TECHNOLOGIES SA
- 16.2.7 CUBESPACE SATELLITE SYSTEMS
- 16.2.8 MAGSON GMBH
- 16.2.9 ISP SYSTEM
- 16.2.10 BARTINGTON INSTRUMENTS LTD
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.3 CUSTOMIZATION OPTIONS
- 17.4 RELATED REPORTS
- 17.5 AUTHOR DETAILS
List of Tables
- TABLE 1 SPACE SENSORS AND ACTUATORS MARKET: INCLUSIONS AND EXCLUSIONS
- TABLE 2 USD EXCHANGE RATES, 2020-2024
- TABLE 3 COMPARISON BETWEEN BUSINESS MODELS
- TABLE 4 STRATEGIC MOVES BY TIER 1, 2, AND 3 PLAYERS
- TABLE 5 GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021-2029
- TABLE 6 ROLE OF COMPANIES IN ECOSYSTEM
- TABLE 7 IMPORT DATA FOR HS CODE 880260-COMPLIANT PRODUCTS, BY COUNTRY, 2020-2024 (USD THOUSAND)
- TABLE 8 EXPORT DATA FOR HS CODE 880260-COMPLIANT PRODUCTS, BY COUNTRY, 2020-2024 (USD THOUSAND)
- TABLE 9 KEY CONFERENCES AND EVENTS, 2025-2026
- TABLE 10 INDICATIVE PRICING FOR SPACE SENSORS AND ACTUATORS, BY PRODUCT TYPE
- TABLE 11 LIST OF MAJOR PATENTS FOR SPACE SENSORS AND ACTUATORS (2021-2024)
- TABLE 12 SPACE SENSORS AND ACTUATORS: ENABLING NEXT-GENERATION SPACECRAFT AUTONOMY
- TABLE 13 QUANTUM AND PHOTONIC SENSORS: NEXT-GENERATION NAVIGATION AND SCIENCE MISSIONS
- TABLE 14 TOP USE CASES AND MARKET POTENTIAL
- TABLE 15 BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES
- TABLE 16 SPACE SENSORS AND ACTUATORS MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION
- TABLE 17 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- TABLE 18 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR SPACE SENSORS AND ACTUATORS, BY END USER (%)
- TABLE 19 KEY BUYING CRITERIA FOR SPACE SENSORS AND ACTUATORS MARKET, BY END USER
- TABLE 20 NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 21 EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 22 ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 23 MIDDLE EAST: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 24 REST OF THE WORLD: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- TABLE 25 GLOBAL INDUSTRY STANDARDS IN SPACE SENSORS AND ACTUATORS MARKET
- TABLE 26 CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN SPACE SENSORS AND ACTUATORS MARKET
- TABLE 27 SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 28 SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 29 SPACE SENSORS AND ACTUATORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 30 SPACE SENSORS AND ACTUATORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 31 SPACE SENSORS AND ACTUATORS MARKET, BY ATTITUDE & NAVIGATION SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 32 SPACE SENSORS AND ACTUATORS MARKET, BY ATTITUDE & NAVIGATION SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 33 SPACE SENSORS AND ACTUATORS MARKET, BY ENVIRONMENTAL SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 34 SPACE SENSORS AND ACTUATORS MARKET, BY ENVIRONMENTAL SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 35 SPACE SENSORS AND ACTUATORS MARKET, BY IMAGE SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 36 SPACE SENSORS AND ACTUATORS MARKET, BY IMAGE SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 37 SPACE SENSORS AND ACTUATORS MARKET, BY PROXIMITY, POSITION, AND RANGING SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 38 SPACE SENSORS AND ACTUATORS MARKET, BY PROXIMITY, POSITION, AND RANGING SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 39 SPACE SENSORS AND ACTUATORS MARKET, BY ACTUATOR TYPE, 2021-2024 (USD MILLION)
- TABLE 40 SPACE SENSORS AND ACTUATORS MARKET, BY ACTUATOR TYPE, 2025-2030 (USD MILLION)
- TABLE 41 SPACE SENSORS AND ACTUATORS MARKET, BY LINEAR ACTUATOR TYPE, 2021-2024 (USD MILLION)
- TABLE 42 SPACE SENSORS AND ACTUATORS MARKET, BY LINEAR ACTUATOR TYPE, 2025-2030 (USD MILLION)
- TABLE 43 SPACE SENSORS AND ACTUATORS MARKET, BY ROTARY ACTUATOR TYPE, 2021-2024 (USD MILLION)
- TABLE 44 SPACE SENSORS AND ACTUATORS MARKET, BY ROTARY ACTUATOR TYPE, 2025-2030 (USD MILLION)
- TABLE 45 SPACE SENSORS AND ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 46 SPACE SENSORS AND ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 47 SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 48 SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 49 SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 50 SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 51 SPACE SENSORS MARKET, BY SATELLITE TYPE, 2021-2024 (USD MILLION)
- TABLE 52 SPACE SENSORS MARKET, BY SATELLITE TYPE, 2025-2030 (USD MILLION)
- TABLE 53 SPACE ACTUATORS MARKET, BY SATELLITE TYPE, 2021-2024 (USD MILLION)
- TABLE 54 SPACE ACTUATORS MARKET, BY SATELLITE TYPE, 2025-2030 (USD MILLION)
- TABLE 55 SPACE SENSORS MARKET, BY SMALL SATELLITE TYPE, 2021-2024 (USD MILLION)
- TABLE 56 SPACE SENSORS MARKET, BY SMALL SATELLITE TYPE, 2025-2030 (USD MILLION)
- TABLE 57 SPACE ACTUATORS MARKET, BY SMALL SATELLITE TYPE, 2021-2024 (USD MILLION)
- TABLE 58 SPACE ACTUATORS MARKET, BY SMALL SATELLITE TYPE, 2025-2030 (USD MILLION)
- TABLE 59 SPACE SENSORS MARKET, BY CAPSULE/CARGO TYPE, 2021-2024 (USD MILLION)
- TABLE 60 SPACE SENSORS MARKET, BY CAPSULE/CARGO TYPE, 2025-2030 (USD MILLION)
- TABLE 61 SPACE ACTUATORS MARKET, BY CAPSULE/CARGO TYPE, 2021-2024 (USD MILLION)
- TABLE 62 SPACE ACTUATORS MARKET, BY CAPSULE/CARGO TYPE, 2025-2030 (USD MILLION)
- TABLE 63 SPACE SENSORS MARKET, BY LAUNCH VEHICLE TYPE, 2021-2024 (USD MILLION)
- TABLE 64 SPACE SENSORS MARKET, BY LAUNCH VEHICLE TYPE, 2025-2030 (USD MILLION)
- TABLE 65 SPACE ACTUATORS MARKET, BY LAUNCH VEHICLE TYPE, 2021-2024 (USD MILLION)
- TABLE 66 SPACE ACTUATORS MARKET, BY LAUNCH VEHICLE TYPE, 2025-2030 (USD MILLION)
- TABLE 67 SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 68 SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2025-2030 (USD MILLION)
- TABLE 69 SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 70 SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 71 SPACE SENSORS AND ACTUATORS MARKET, BY COMMERCIAL END USER, 2021-2024 (USD MILLION)
- TABLE 72 SPACE SENSORS AND ACTUATORS MARKET, BY COMMERCIAL END USER, 2025-2030 (USD MILLION)
- TABLE 73 SPACE SENSORS AND ACTUATORS MARKET, BY GOVERNMENT & DEFENSE END USER, 2021-2024 (USD MILLION)
- TABLE 74 SPACE SENSORS AND ACTUATORS MARKET, BY GOVERNMENT & DEFENSE END USER, 2025-2030 (USD MILLION)
- TABLE 75 SPACE SENSORS AND ACTUATORS MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 76 SPACE SENSORS AND ACTUATORS MARKET, BY REGION, 2025-2030 (USD MILLION)
- TABLE 77 NORTH AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY COUNTRY, 2021-2024 (USD MILLION)
- TABLE 78 NORTH AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY COUNTRY, 2025-2030 (USD MILLION)
- TABLE 79 NORTH AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 80 NORTH AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 81 NORTH AMERICA: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 82 NORTH AMERICA: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 83 NORTH AMERICA: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 84 NORTH AMERICA: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 85 NORTH AMERICA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 86 NORTH AMERICA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 87 NORTH AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 88 NORTH AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 89 NORTH AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 90 NORTH AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2025-2030 (USD MILLION)
- TABLE 91 US: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 92 US: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 93 US: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 94 US: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 95 US: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 96 US: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 97 US: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 98 US: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 99 US: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 100 US: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 101 CANADA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 102 CANADA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 103 CANADA: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 104 CANADA: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 105 CANADA: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 106 CANADA: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 107 CANADA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 108 CANADA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 109 CANADA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 110 CANADA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 111 EUROPE: SPACE SENSORS AND ACTUATORS MARKET, BY COUNTRY, 2021-2024 (USD MILLION)
- TABLE 112 EUROPE: SPACE SENSORS AND ACTUATORS MARKET, BY COUNTRY, 2025-2030 (USD MILLION)
- TABLE 113 EUROPE: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 114 EUROPE: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 115 EUROPE: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 116 EUROPE: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 117 EUROPE: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 118 EUROPE: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 119 EUROPE: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 120 EUROPE: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 121 EUROPE: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 122 EUROPE: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 123 EUROPE: SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 124 EUROPE: SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2025-2030 (USD MILLION)
- TABLE 125 RUSSIA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 126 RUSSIA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 127 RUSSIA: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 128 RUSSIA: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 129 RUSSIA: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 130 RUSSIA: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 131 RUSSIA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 132 RUSSIA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 133 RUSSIA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 134 RUSSIA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 135 GERMANY: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 136 GERMANY: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 137 GERMANY: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 138 GERMANY: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 139 GERMANY: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 140 GERMANY: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 141 GERMANY: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 142 GERMANY: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 143 GERMANY: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 144 GERMANY: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 145 FRANCE: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 146 FRANCE: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 147 FRANCE: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 148 FRANCE: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 149 FRANCE: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 150 FRANCE: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 151 FRANCE: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 152 FRANCE: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 153 FRANCE: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 154 FRANCE: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 155 UK: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 156 UK: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 157 UK: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 158 UK: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 159 UK: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 160 UK: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 161 UK: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 162 UK: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 163 UK: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 164 UK: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 165 ITALY: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 166 ITALY: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 167 ITALY: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 168 ITALY: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 169 ITALY: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 170 ITALY: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 171 ITALY: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 172 ITALY: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 173 ITALY: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 174 ITALY: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 175 ASIA PACIFIC: SPACE SENSORS AND ACTUATORS MARKET, BY COUNTRY, 2021-2024 (USD MILLION)
- TABLE 176 ASIA PACIFIC: SPACE SENSORS AND ACTUATORS MARKET, BY COUNTRY, 2025-2030 (USD MILLION)
- TABLE 177 ASIA PACIFIC: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 178 ASIA PACIFIC: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 179 ASIA PACIFIC: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 180 ASIA PACIFIC: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 181 ASIA PACIFIC: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 182 ASIA PACIFIC: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 183 ASIA PACIFIC: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 184 ASIA PACIFIC: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 185 ASIA PACIFIC: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 186 ASIA PACIFIC: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 187 ASIA PACIFIC: SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 188 ASIA PACIFIC: SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2025-2030 (USD MILLION)
- TABLE 189 CHINA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 190 CHINA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 191 CHINA: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 192 CHINA: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 193 CHINA: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 194 CHINA: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 195 CHINA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 196 CHINA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 197 CHINA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 198 CHINA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 199 INDIA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 200 INDIA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 201 INDIA: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 202 INDIA: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 203 INDIA: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 204 INDIA: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 205 INDIA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 206 INDIA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 207 INDIA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 208 INDIA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 209 JAPAN: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 210 JAPAN: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 211 JAPAN: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 212 JAPAN: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 213 JAPAN: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 214 JAPAN: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 215 JAPAN: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 216 JAPAN: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 217 JAPAN: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 218 JAPAN: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 219 SOUTH KOREA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 220 SOUTH KOREA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 221 SOUTH KOREA: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 222 SOUTH KOREA: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 223 SOUTH KOREA: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 224 SOUTH KOREA: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 225 SOUTH KOREA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 226 SOUTH KOREA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 227 SOUTH KOREA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 228 SOUTH KOREA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 229 AUSTRALIA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 230 AUSTRALIA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 231 AUSTRALIA: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 232 AUSTRALIA: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 233 AUSTRALIA: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 234 AUSTRALIA: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 235 AUSTRALIA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 236 AUSTRALIA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 237 AUSTRALIA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 238 AUSTRALIA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 239 MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY COUNTRY, 2021-2024 (USD MILLION)
- TABLE 240 MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY COUNTRY, 2025-2030 (USD MILLION)
- TABLE 241 MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 242 MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 243 MIDDLE EAST: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 244 MIDDLE EAST: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 245 MIDDLE EAST: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 246 MIDDLE EAST: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 247 MIDDLE EAST: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 248 MIDDLE EAST: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 249 MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 250 MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 251 MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 252 MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2025-2030 (USD MILLION)
- TABLE 253 SAUDI ARABIA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 254 SAUDI ARABIA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 255 SAUDI ARABIA: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 256 SAUDI ARABIA: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 257 SAUDI ARABIA: SPACE ACTUATOR MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 258 SAUDI ARABIA: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 259 SAUDI ARABIA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 260 SAUDI ARABIA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 261 SAUDI ARABIA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 262 SAUDI ARABIA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 263 UAE: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 264 UAE: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 265 UAE: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 266 UAE: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 267 UAE: SPACE ACTUATOR MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 268 UAE: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 269 UAE: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 270 UAE: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 271 UAE: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 272 UAE: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 273 REST OF MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 274 REST OF MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 275 REST OF MIDDLE EAST: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 276 REST OF MIDDLE EAST: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 277 REST OF MIDDLE EAST: SPACE ACTUATOR MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 278 REST OF MIDDLE EAST: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 279 REST OF MIDDLE EAST: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 280 REST OF MIDDLE EAST: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 281 REST OF MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 282 REST OF MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 283 REST OF THE WORLD: SPACE SENSORS AND ACTUATORS MARKET, BY REGION, 2021-2024 (USD MILLION)
- TABLE 284 REST OF THE WORLD: SPACE SENSORS AND ACTUATORS MARKET, BY REGION, 2025-2030 (USD MILLION)
- TABLE 285 REST OF THE WORLD: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 286 REST OF THE WORLD: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 287 REST OF THE WORLD: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 288 REST OF THE WORLD: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 289 REST OF THE WORLD: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 290 REST OF THE WORLD: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 291 REST OF THE WORLD: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 292 REST OF THE WORLD: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 293 REST OF THE WORLD: SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2021-2024 (USD MILLION)
- TABLE 294 REST OF THE WORLD: SPACE SENSORS AND ACTUATORS MARKET, BY APPLICATION, 2025-2030 (USD MILLION)
- TABLE 295 REST OF THE WORLD: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 296 REST OF THE WORLD: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 297 LATIN AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 298 LATIN AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 299 LATIN AMERICA: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 300 LATIN AMERICA: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 301 LATIN AMERICA: SPACE ACTUATOR MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 302 LATIN AMERICA: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 303 LATIN AMERICA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 304 LATIN AMERICA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 305 LATIN AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 306 LATIN AMERICA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 307 AFRICA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2021-2024 (USD MILLION)
- TABLE 308 AFRICA: SPACE SENSORS AND ACTUATORS MARKET, BY PRODUCT TYPE, 2025-2030 (USD MILLION)
- TABLE 309 AFRICA: SPACE SENSORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 310 AFRICA: SPACE SENSORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 311 AFRICA: SPACE ACTUATORS MARKET, BY PLATFORM, 2021-2024 (USD MILLION)
- TABLE 312 AFRICA: SPACE ACTUATORS MARKET, BY PLATFORM, 2025-2030 (USD MILLION)
- TABLE 313 AFRICA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2021-2024 (USD MILLION)
- TABLE 314 AFRICA: SPACE SENSORS MARKET, BY SENSOR TYPE, 2025-2030 (USD MILLION)
- TABLE 315 AFRICA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2021-2024 (USD MILLION)
- TABLE 316 AFRICA: SPACE SENSORS AND ACTUATORS MARKET, BY END USER, 2025-2030 (USD MILLION)
- TABLE 317 KEY PLAYER STRATEGIES/RIGHT TO WIN, JANUARY 2020-OCTOBER 2025
- TABLE 318 SPACE SENSORS AND ACTUATORS MARKET: DEGREE OF COMPETITION
- TABLE 319 SPACE SENSORS AND ACTUATORS MARKET: REGION FOOTPRINT
- TABLE 320 SPACE SENSORS AND ACTUATORS MARKET: PRODUCT TYPE FOOTPRINT
- TABLE 321 SPACE SENSORS AND ACTUATORS MARKET: END USER FOOTPRINT
- TABLE 322 SPACE SENSORS AND ACTUATORS MARKET: PLATFORM FOOTPRINT
- TABLE 323 LIST OF KEY STARTUPS/SMES
- TABLE 324 COMPETITIVE BENCHMARKING OF STARTUPS/SMES
- TABLE 325 SPACE SENSORS AND ACTUATORS MARKET: PRODUCT LAUNCHES, JANUARY 2020-OCTOBER 2025
- TABLE 326 SPACE SENSORS AND ACTUATORS MARKET: DEALS, JANUARY 2020- OCTOBER 2025
- TABLE 327 SPACE SENSORS AND ACTUATORS MARKET: OTHERS, JANUARY 2020- OCTOBER 2025
- TABLE 328 HONEYWELL INTERNATIONAL INC.: COMPANY OVERVIEW
- TABLE 329 HONEYWELL INTERNATIONAL INC.: PRODUCTS OFFERED
- TABLE 330 HONEYWELL INTERNATIONAL INC.: PRODUCT LAUNCHES
- TABLE 331 HONEYWELL INTERNATIONAL INC.: DEALS
- TABLE 332 HONEYWELL INTERNATIONAL INC.: OTHERS
- TABLE 333 TELEDYNE TECHNOLOGIES INCORPORATED: COMPANY OVERVIEW
- TABLE 334 TELEDYNE TECHNOLOGIES INCORPORATED: PRODUCTS OFFERED
- TABLE 335 TELEDYNE TECHNOLOGIES INCORPORATED: PRODUCT LAUNCHES
- TABLE 336 TELEDYNE TECHNOLOGIES INCORPORATED: DEALS
- TABLE 337 TELEDYNE TECHNOLOGIES INCORPORATED: OTHERS
- TABLE 338 MOOG INC.: COMPANY OVERVIEW
- TABLE 339 MOOG INC.: PRODUCTS OFFERED
- TABLE 340 MOOG INC.: EXPANSIONS
- TABLE 341 MOOG INC.: OTHERS
- TABLE 342 SAFRAN GROUP: COMPANY OVERVIEW
- TABLE 343 SAFRAN GROUP: PRODUCTS OFFERED
- TABLE 344 SAFRAN GROUP: DEALS
- TABLE 345 SAFRAN GROUP: OTHERS
- TABLE 346 AIRBUS: COMPANY OVERVIEW
- TABLE 347 AIRBUS: PRODUCTS OFFERED
- TABLE 348 L3HARRIS TECHNOLOGIES, INC.: COMPANY OVERVIEW
- TABLE 349 L3HARRIS TECHNOLOGIES, INC.: PRODUCTS OFFERED
- TABLE 350 L3HARRIS TECHNOLOGIES, INC.: OTHERS
- TABLE 351 RTX: COMPANY OVERVIEW
- TABLE 352 RTX: PRODUCTS OFFERED
- TABLE 353 RTX: OTHERS
- TABLE 354 VANTOR: COMPANY OVERVIEW
- TABLE 355 VANTOR: PRODUCTS OFFERED
- TABLE 356 VANTOR: DEALS
- TABLE 357 VANTOR: OTHERS
- TABLE 358 TEXAS INSTRUMENTS INCORPORATED: COMPANY OVERVIEW
- TABLE 359 TEXAS INSTRUMENTS INCORPORATED: PRODUCTS OFFERED
- TABLE 360 TEXAS INSTRUMENTS INCORPORATED: PRODUCT LAUNCHES
- TABLE 361 TEXAS INSTRUMENTS INCORPORATED: EXPANSIONS
- TABLE 362 AMETEK.INC.: COMPANY OVERVIEW
- TABLE 363 AMETEK.INC.: PRODUCTS OFFERED
- TABLE 364 AMETEK.INC.: DEALS
- TABLE 365 RUAG GROUP: COMPANY OVERVIEW
- TABLE 366 RUAG GROUP: PRODUCTS OFFERED
- TABLE 367 RUAG GROUP: OTHERS
- TABLE 368 ANALOG DEVICES, INC.: COMPANY OVERVIEW
- TABLE 369 ANALOG DEVICES, INC.: PRODUCTS OFFERED
- TABLE 370 BAE SYSTEMS: COMPANY OVERVIEW
- TABLE 371 BAE SYSTEMS: PRODUCTS OFFERED
- TABLE 372 BAE SYSTEMS: PRODUCT LAUNCHES
- TABLE 373 BAE SYSTEMS: DEALS
- TABLE 374 BAE SYSTEMS: OTHERS
- TABLE 375 STMICROELECTRONICS: COMPANY OVERVIEW
- TABLE 376 STMICROELECTRONICS: PRODUCTS OFFERED
- TABLE 377 BLUE ORIGIN: PRODUCTS OFFERED
- TABLE 378 BLUE ORIGIN: DEALS
- TABLE 379 BLUE ORIGIN: OTHERS
- TABLE 380 TE CONNECTIVITY: COMPANY OVERVIEW
- TABLE 381 TE CONNECTIVITY: PRODUCTS OFFERED
- TABLE 382 TE CONNECTIVITY: DEALS
- TABLE 383 INNALABS.: COMPANY OVERVIEW
- TABLE 384 COMAT: COMPANY OVERVIEW
- TABLE 385 SPACE-LOCK GMBH: COMPANY OVERVIEW
- TABLE 386 NEWSPACE SYSTEMS: COMPANY OVERVIEW
- TABLE 387 VEOWARE: COMPANY OVERVIEW
- TABLE 388 CABRAT TECHNOLOGIES SA: COMPANY OVERVIEW
- TABLE 389 CUBESPACE SATELLITE SYSTEMS: COMPANY OVERVIEW
- TABLE 390 MAGSON GMBH: COMPANY OVERVIEW
- TABLE 391 ISP SYSTEM: COMPANY OVERVIEW
- TABLE 392 BARTINGTON INSTRUMENTS LTD: COMPANY OVERVIEW
List of Figures
- FIGURE 1 SPACE SENSORS AND ACTUATORS MARKET SEGMENTATION
- FIGURE 2 RESEARCH FLOW
- FIGURE 3 RESEARCH DESIGN
- FIGURE 4 MARKET SIZE ESTIMATION METHODOLOGY: BOTTOM-UP APPROACH
- FIGURE 5 MARKET SIZE ESTIMATION METHODOLOGY: TOP-DOWN APPROACH
- FIGURE 6 DATA TRIANGULATION METHODOLOGY
- FIGURE 7 KEY INSIGHTS AND MARKET HIGHLIGHTS
- FIGURE 8 MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN SPACE SENSORS AND ACTUATORS MARKET (2020-2025)
- FIGURE 9 NORTH AMERICA TO ACCOUNT FOR LEADING MARKET SHARE IN 2025
- FIGURE 10 NORTH AMERICA TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD
- FIGURE 11 INCREASING DEMAND FOR SATELLITE-BASED SERVICES AND DEEP SPACE ACTIVITIES TO DRIVE MARKET
- FIGURE 12 SENSORS SEGMENT TO REGISTER HIGHER CAGR IN 2025-2030
- FIGURE 13 COMMERCIAL END USER SEGMENT TO ACCOUNT FOR DOMINANT MARKET SHARE IN 2025
- FIGURE 14 INTERPLANETARY SPACECRAFT AND PROBES TO GROW AT HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 15 DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES IN SPACE SENSORS AND ACTUATORS MARKET
- FIGURE 16 VALUE CHAIN ANALYSIS
- FIGURE 17 ECOSYSTEM ANALYSIS OF SPACE SENSORS AND ACTUATORS MARKET
- FIGURE 18 IMPORT DATA FOR HS CODE 880260-COMPLIANT PRODUCTS, BY COUNTRY, 2020-2024 (USD THOUSAND)
- FIGURE 19 EXPORT DATA FOR HS CODE 880260-COMPLIANT PRODUCTS, BY COUNTRY, 2020-2024 (USD THOUSAND)
- FIGURE 20 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- FIGURE 21 INVESTMENT AND FUNDING SCENARIO, 2021-2025
- FIGURE 22 AVERAGE SELLING PRICE TREND OF SPACE SENSORS AND ACTUATORS, BY REGION, 2021-2024 (USD MILLION)
- FIGURE 23 TECHNOLOGY ROADMAP (2020-2035)
- FIGURE 24 EMERGING TECHNOLOGY TRENDS
- FIGURE 25 PATENT ANALYSIS
- FIGURE 26 FUTURE APPLICATIONS
- FIGURE 27 SPACE SENSORS AND ACTUATORS MARKET: IMPACT OF AI/GEN AI
- FIGURE 28 SPACE SENSORS AND ACTUATORS MARKET: DECISION-MAKING FACTORS
- FIGURE 29 INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY END USER
- FIGURE 30 KEY BUYING CRITERIA FOR SPACE SENSORS AND ACTUATORS, BY END USER
- FIGURE 31 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- FIGURE 32 SENSORS SEGMENT TO WITNESS HIGHER CAGR THAN ACTUATORS SEGMENT DURING FORECAST PERIOD
- FIGURE 33 INTERPLANETARY SPACECRAFT AND PROBES SEGMENT TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 34 COMMUNICATION POINTING & RF SWITCHING SEGMENT TO RECORD HIGHEST CAGR DURING FORECAST PERIOD
- FIGURE 35 COMMERCIAL SEGMENT TO LEAD SPACE SENSORS AND ACTUATORS MARKET DURING FORECAST PERIOD
- FIGURE 36 SPACE SENSORS AND ACTUATORS MARKET IN NORTH AMERICA TO CAPTURE LARGEST SHARE IN 2025
- FIGURE 37 NORTH AMERICA: SPACE SENSORS AND ACTUATORS MARKET SNAPSHOT
- FIGURE 38 EUROPE: SPACE SENSORS AND ACTUATORS MARKET SNAPSHOT
- FIGURE 39 ASIA PACIFIC: SPACE SENSORS AND ACTUATORS MARKET SNAPSHOT
- FIGURE 40 MIDDLE EAST: SPACE SENSORS AND ACTUATORS MARKET SNAPSHOT
- FIGURE 41 REST OF THE WORLD: SPACE SENSORS AND ACTUATORS MARKET SNAPSHOT
- FIGURE 42 REVENUE ANALYSIS OF TOP 5 PLAYERS, 2021-2024
- FIGURE 43 MARKET SHARE ANALYSIS OF KEY PLAYERS, 2024
- FIGURE 44 BRAND COMPARISON IN SPACE SENSORS AND ACTUATORS MARKET
- FIGURE 45 FINANCIAL METRICS OF PROMINENT PLAYERS, 2025
- FIGURE 46 VALUATION OF PROMINENT PLAYERS, 2025
- FIGURE 47 COMPANY EVALUATION MATRIX (KEY PLAYERS), 2024
- FIGURE 48 SPACE SENSORS AND ACTUATORS MARKET: COMPANY FOOTPRINT
- FIGURE 49 COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2024
- FIGURE 50 HONEYWELL INTERNATIONAL INC.: COMPANY SNAPSHOT
- FIGURE 51 TELEDYNE TECHNOLOGIES INCORPORATED: COMPANY SNAPSHOT
- FIGURE 52 MOOG INC.: COMPANY SNAPSHOT
- FIGURE 53 SAFRAN GROUP: COMPANY SNAPSHOT
- FIGURE 54 AIRBUS: COMPANY SNAPSHOT
- FIGURE 55 L3HARRIS TECHNOLOGIES, INC.: COMPANY SNAPSHOT
- FIGURE 56 RTX: COMPANY SNAPSHOT
- FIGURE 57 TEXAS INSTRUMENTS INCORPORATED: COMPANY SNAPSHOT
- FIGURE 58 AMETEK.INC.: COMPANY SNAPSHOT
- FIGURE 59 RUAG GROUP: COMPANY SNAPSHOT
- FIGURE 60 ANALOG DEVICES, INC.: COMPANY SNAPSHOT
- FIGURE 61 BAE SYSTEMS: COMPANY SNAPSHOT
- FIGURE 62 STMICROELECTRONICS: COMPANY SNAPSHOT
- FIGURE 63 TE CONNECTIVITY: COMPANY SNAPSHOT

 空間感測器與執行器市場-2026-2032年全球市場預測
 2026年全球空間感測器和致動器市場報告
 太空傳感器市場到 2035 年的分析和預測:按類型、產品、技術、組件、應用、最終用戶、功能、安裝配置、解決方案和階段分類。
 空間感測器和執行器市場-全球產業規模、佔有率、趨勢、機會和預測,按產品類型、平台、最終用戶、地區和競爭格局分類,2020-2030 年預測
 宇宙用感測器和致動器的全球市場,各感測器類型,各致動器類型,各用途,各地區,機會,預測,2018年~2032年
 全球空間感測器和致動器市場
 空間感測器市場至2030年的預測:按類型、平台、應用、最終用戶和地區分類的全球分析
 空間感測器和執行器市場機會、成長促進因素、行業趨勢分析和預測 2025 - 2034 年
 宇宙用感測器及致動器的全球市場:2024-2034年